Tag Archives: DepthPR

Strategic Benefits Advisors holds steady as Atlanta’s benefits consultant market shrinks 17%

Firm named one of Atlanta's largest employee benefits companies for eighth consecutive year and adds Operations and People Development Officer Kendra Jeffreys to support continued growth

ATLANTA, Ga., Sept. 23, 2026 (SEND2PRESS NEWSWIRE) — Strategic Benefits Advisors, Inc. (SBA) has been recognized by the Atlanta Business Chronicle as one of Atlanta’s largest employee benefits and compensation companies of 2026. This is the eighth consecutive year SBA has made the Chronicle’s annual list highlighting benefits consultants and brokers. Even as the number of benefits consultants and brokers in Atlanta fell 17% in 2026, according to the Chronicle, SBA held its position and is ensuring readiness for growth with the recent addition of Operations and People Development Officer Kendra Jeffreys.
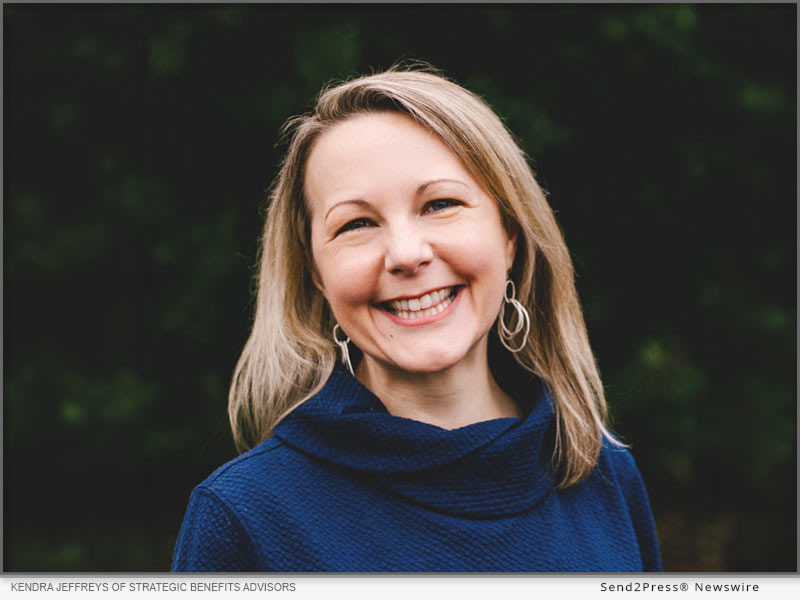
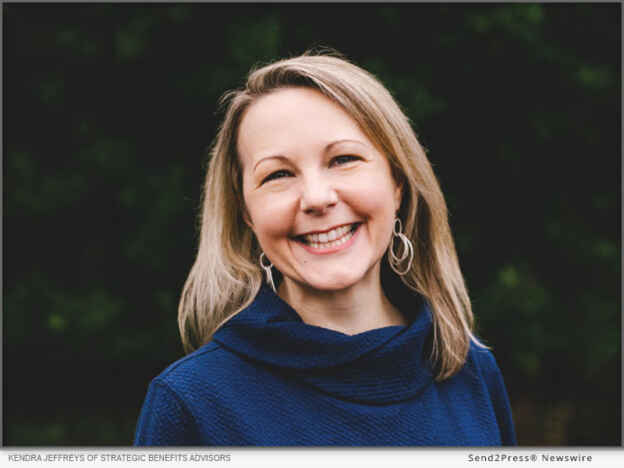
Kendra Jeffreys of Strategic Benefits Advisors
Image caption: Kendra Jeffreys of Strategic Benefits Advisors.

Jeffreys joined SBA in April to lead the design and scaling of the internal systems, processes and talent infrastructure that support SBA’s growth. On the operational side, she guides how SBA deploys AI and automation to improve efficiency while maintaining the judgment, accuracy and client stewardship central to its consulting approach. She also oversees the recruiting, onboarding and leadership development programs that help SBA attract and grow talent.

“The contraction in Atlanta’s benefits consulting market reflects a broader period of consolidation across the industry,” said SBA Founding Principal Mindy Zatto. “Against that backdrop, SBA has continued to grow because our clients across the country value experienced, independent consultants who stay close to the work and can help them navigate increasingly complex benefits decisions. That kind of continuity matters, especially when the market around you is changing.”

“As SBA grows, we also have to be deliberate about how we build the firm behind the client work,” Zatto added. “Kendra is the right person to help us strengthen the systems, processes and talent development practices that support our people today and position SBA for thoughtful, sustainable growth.”

Jeffreys brings more than 20 years of experience in organizational effectiveness, enterprise transformation, project management and people development. Before joining SBA, she held senior operational leadership roles with national and global organizations, where she led large-scale transformation initiatives, systems implementations, process improvement efforts and staff development programs. She earned her master’s degree in public health from Georgia State University and her bachelor’s degree in cultural anthropology from Emory University.

About Strategic Benefits Advisors:

Strategic Benefits Advisors, Inc. (SBA) is an independent, full-service employee benefits consulting firm focused on creatively and effectively solving complex benefits issues for clients ranging from 1,000 to over 300,000 employees. Founded in 2002, SBA provides practical consulting recommendations and expert implementation of solutions for all types of employee benefits programs, including retirement, health and welfare, financial wellness and employee recognition. With an average of more than 20 years in the field, SBA’s team of actuaries, consultants and systems specialists is among the most experienced in the industry. For more information, visit https://www.sba-inc.com/.

NEWS SOURCE: Strategic Benefits Advisors Inc.


This press release was issued on behalf of the news source (Strategic Benefits Advisors Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/strategic-benefits-advisors-holds-steady-as-atlantas-benefits-consultant-market-shrinks-17/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138415 NOREL-3B
 

Friday Harbor adds AI-pre-underwriting support for investor and DSCR loans

New investor-loan capability extends Friday Harbor's non-QM support to a segment representing more than one-third of non-QM production

SEATTLE, Wash., Sept. 23, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, today announced expanded support for investor loans, including debt service coverage ratio (DSCR) loans.

Friday Harbor logo
Image caption: Friday Harbor.

The new capability builds on Friday Harbor’s recently launched non-qualified mortgage support at a time when non-QM loans account for more than one in 10 mortgage originations and investor-focused products make up a significant share of that market. In August, asset-based, fix-and-flip and DSCR loans represented more than 35% of non-QM production, according to Optimal Blue.

Unlike traditional mortgages, DSCR loans qualify borrowers primarily on a property’s rental income rather than personal income or tax returns. Their specialized guidelines can make these loans time-consuming and difficult for loan officers who do not work with them every day, forcing them to stop and consult an underwriter or other specialist when questions arise.

Friday Harbor reviews leases, appraisal-based rent schedules, property information, borrower and entity documentation and other deal details against applicable program guidelines before underwriting, giving loan officers the guidance they need to work through those scenarios themselves.

“DSCR loans can be a great opportunity for lenders, but they are difficult to scale when only a small number of people in the organization know how to structure them,” said Theo Ellis, founder and CEO of Friday Harbor. “By putting that expertise in originators’ hands earlier, Friday Harbor gives more of them the confidence to evaluate these deals, work through questions and compete for a growing share of the market.”

For more information about Friday Harbor’s AI pre-underwriting capabilities, visit https://fridayharbor.ai.

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbor-adds-ai-pre-underwriting-support-for-investor-and-dscr-loans/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138376 NOREL-3B


ACES Quality Management launches ACES Population Testing

New technology applies lender-defined policies at scale across a predetermined loan population for greater risk identification

DENVER, Colo., Sept. 21, 2026 (SEND2PRESS NEWSWIRE) — ACES Quality Management®, the leading provider of enterprise quality management and control software for the financial services industry, announced today the launch of ACES Population Testing™, which evaluates a financial institution’s loan origination pipelines and servicing portfolios against its defined policies and identifies the records that warrant a reviewer’s attention. The platform is built on data quality technology ACES obtained through its acquisition of BaseCap Analytics and already in production at financial institutions.

ACES Quality Management
Image caption: ACES Quality Management launches ACES Population Testing.

A lender selects the population it wants examined and the policies it wants applied, covering its own compliance, operational and data quality requirements across pre-funding, post-closing and servicing reviews and beyond. Lenders can author the policies themselves or draw from ACES Managed Policies, an expanding library of ACES-authored, compliance-vetted policy content. ACES Population Testing runs those policies against every record in that population, reports a pass or fail on each policy for each record and rolls the results into an overall quality score on the dashboard.

“Compliance and quality programs are under constant pressure to extend their reach without expanding their teams, and ACES Population Testing gives those departments at lenders, servicers, banks, credit unions and other financial institutions the ability to evaluate loan portfolios at the population level, identifying risk that would otherwise go unreviewed,” said Trevor Gauthier, chief executive officer of ACES Quality Management. “The engine underneath ACES Population Testing has been running in production at financial institutions for years, and by bringing it under the ACES umbrella, it now becomes the natural complement to our audit technology, directing our clients’ teams to the records that matter most for targeted, human-driven investigation.”

ACES Population Testing operates alongside traditional sampling methodologies by directing auditors to records that a sample may not reach. From there, auditors can use ACES Quality Management & Control® software to examine the flagged records, determine if they are defects, report findings and remediate.

To learn more, visit https://www.acesquality.com/products/population-testing.

About ACES Quality Management

ACES Quality Management is the leading provider of enterprise quality management and control software for the financial services industry. The nation’s most prominent lenders, servicers and financial institutions rely on ACES Quality Management & Control® Software to improve audit throughput and quality while controlling costs, including:

  • Over 70% of the top 20 independent mortgage lenders;
  • 8 of the top 10 loan servicers;
  • 14 of the top 30 banks; and
  • 7 of the top 15 credit unions in the United States.

ACES also supports multiple state housing authorities and mortgage insurers, a government-sponsored enterprise (GSE) and dozens of third-party QC service providers that collectively serve hundreds of financial institutions.

Unlike other quality control platforms, ACES Flexible Audit Technology® enables independent mortgage lenders and financial institutions to easily manage and customize the system to their specific needs, including the ability to evaluate loan risk at scale without relying on IT or outside resources. With ACES’ AI-powered capabilities, audit teams can translate complexity into clear insights and accelerate performance.

Using a customer-centric approach, ACES clients get responsive support and access to our experts to maximize their investment. For more information, visit https://www.acesquality.com/ or call 1-800-858-1598.

LOGO link for media (SVG): https://www.acesquality.com/assets/images/aces-logo.svg

NEWS SOURCE: ACES Quality Management


This press release was issued on behalf of the news source (ACES Quality Management), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/aces-quality-management-launches-aces-population-testing/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138320 NOREL-3B


FirstClose introduces Lender Portal to manage home equity borrower leads in one workspace

AUSTIN, Texas, Sept. 17, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for home equity and mortgage lenders nationwide, announced today the launch of Lender Portal, a new workspace that lets loan officers manage borrower leads in one place, from initial contact through submission.

FirstClose logo
Image caption: FirstClose logo.

Available to lenders using FirstClose’s XpressEquity digital application and borrower portal, Lender Portal covers lead intake, eligibility evaluation and borrower engagement tracking. Loan officers can create leads directly in Lender Portal when taking applications by phone or in-branch. Applications that borrowers start on their own also flow directly into the same pipeline. If the borrower used an application link associated with a specific loan officer, Lender Portal automatically assigns the lead to that individual. Unassigned leads can be claimed by another loan officer or reassigned by a manager.

Lender Portal also verifies borrower eligibility before an application reaches underwriting by comparing a soft-pull credit score against the lender’s configured minimum and measuring the borrower’s home equity against the lender’s limits. From there, the portal presents applicants with eligible loan programs to select from. This early check is designed to reduce application fallout, counteroffers and rework in underwriting.

Within the workspace, a loan officer can check a lead’s status and when the borrower last engaged to time follow-up calls or messages accordingly. Lender Portal also identifies stalled applications and can send automatic reminders to the borrower. Once the borrower re-engages, the loan officer can resume the application from the last completed milestone rather than starting over.

“Loan officers spend a lot of their day hunting for information instead of talking to borrowers, which is both inefficient and costly because that’s how applications stall and borrowers slip away,” said Tedd Smith, chief executive officer of FirstClose. “Lender Portal addresses that challenge head-on so that loan officers can spend more time assisting borrowers and moving applications forward rather than searching between systems.”

Lender Portal is part of FirstClose’s broader platform for mortgage and home equity lenders, which also includes XpressEquity. To learn more about Lender Portal, visit https://www.firstclose.com/lp-lender-portal/.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to home equity and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-introduces-lender-portal-to-manage-home-equity-borrower-leads-in-one-workspace/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138265 NOREL-3B


Analysis: iEmergent’s 2025 U.S. mortgage forecasts closely track HMDA actuals

Precision down to the census tract gives lenders a dependable edge for staffing, expansion and marketing decisions well before final HMDA data arrives

DES MOINES, Iowa, Sept. 16, 2026 (SEND2PRESS NEWSWIRE) — iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today released a new analysis validating its 2025 forecasts against actual Home Mortgage Disclosure Act (HMDA) data. The analysis, which uses final 2025 HMDA data released by the Federal Financial Institutions Examination Council on June 23, 2026, spans every geographic level from national down to individual census tracts, showing the strength of iEmergent’s bottom-up forecasting approach.

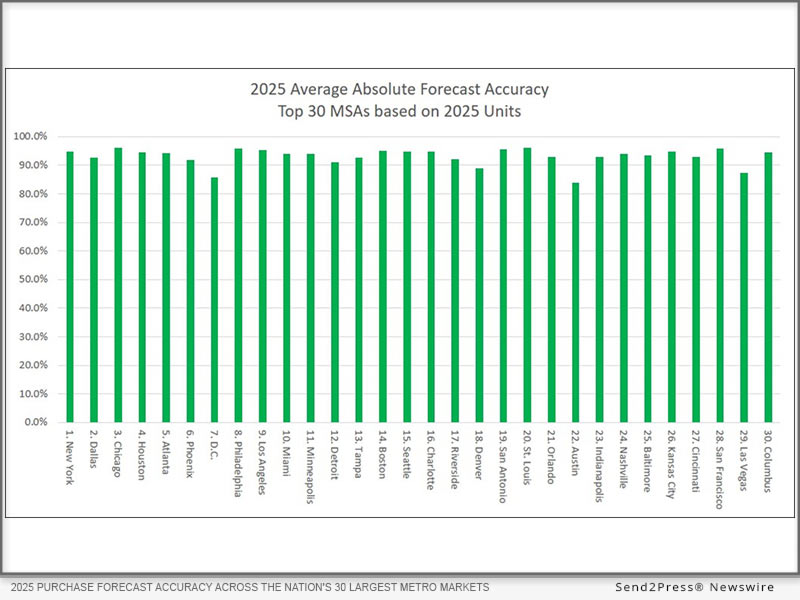
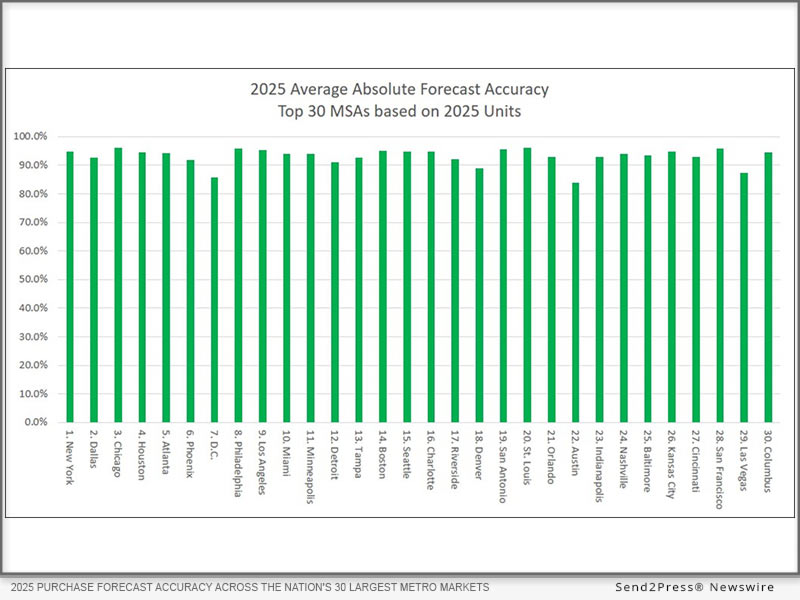
2025 PURCHASE FORECAST ACCURACY ACROSS THE NATION'S 30 LARGEST METRO MARKETS, MEASURED AGAINST HMDA ACTUALS
Image caption: 2025 PURCHASE FORECAST ACCURACY ACROSS THE NATION’S 30 LARGEST METRO MARKETS, MEASURED AGAINST HMDA ACTUALS.

The accuracy of iEmergent’s 2025 purchase loan forecasts for the nation’s top 30 largest metropolitan statistical areas (MSAs) averaged well above 90% when compared against 2025 HMDA actuals. That figure reflects absolute forecast accuracy, which cannot exceed 100%.

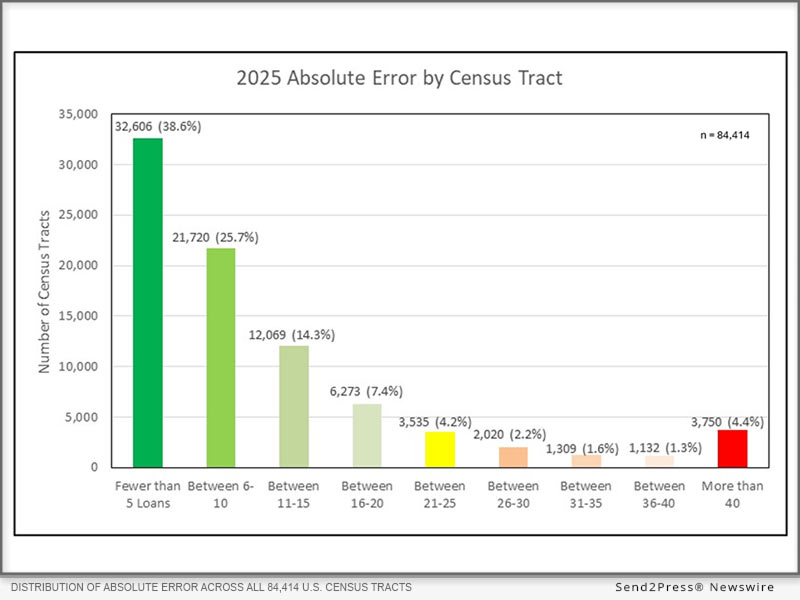
Looking at per-tract loan error by individual census tract, iEmergent’s 2025 forecast was within 10 loans of actual volume in more than 64.3% of the nation’s 84,414 census tracts. Widening that margin to 15 loans, the forecast was accurate for 78.6% of all tracts.

DISTRIBUTION OF ABSOLUTE ERROR ACROSS ALL 84,414 U.S. CENSUS TRACTS FOR 2025 PURCHASE LOANS
Image caption: DISTRIBUTION OF ABSOLUTE ERROR ACROSS ALL 84,414 U.S. CENSUS TRACTS FOR 2025 PURCHASE LOANS.

“Lenders need a dependable line of sight into where mortgage opportunity is forming, market by market — not months after the fact, once HMDA data finally confirms it, but early enough to guide decisions on staffing, branch locations, marketing spend and growth strategy for the year ahead,” iEmergent CEO Laird Nossuli said. “That’s exactly what iEmergent’s proprietary, bottom-up model is built to deliver.”

iEmergent also validated the accuracy of its forecasts against actual HMDA data at the borrower race and ethnicity level. Segment-level accuracy is calculated as the ratio of forecast to actual loan volume, which reflects both the size and direction of the forecast error. A figure above 100% indicates the forecast slightly exceeded actual volume; a figure below 100% indicates it fell short. For 2025, the company’s fourth-quarter 2024 forecast produced the following national-level accuracy rates by borrower segment:

  • Asian borrowers: 107.3% accuracy
  • Black borrowers: 96.3% accuracy
  • Hispanic borrowers: 90.5% accuracy
  • Native American and Pacific Islander borrowers: 83.8% accuracy
  • Non-Hispanic white borrowers: 89.4% accuracy

iEmergent’s forecasts are built on two core concepts: the Purchase Mortgage Generation Rate, which measures the rate at which an individual market produces purchase mortgages, and the Homebuyer Pool, the number of households ready, willing and able to buy a home in a given year. Together, these replace traditional top-down, supply-side forecasting models with a demand-driven approach rooted in how households actually behave. A full overview of iEmergent’s forecasting methodology is available at https://www.iemergent.com/insights/mortgage-opportunity-forecasting.

ABOUT IEMERGENT

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com.

Tags: @iEmergent

Media Kit (PDF): https://www.iemergent.com/docs/default-source/default-document-library/presskit_digitallinked.pdf

NEWS SOURCE: iEmergent


This press release was issued on behalf of the news source (iEmergent), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/analysis-iemergents-2025-u-s-mortgage-forecasts-closely-track-hmda-actuals/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138244 NOREL-3B


Argyle extends its mortgage verification experience to the wholesale channel with the launch of a broker-branded borrower experience

Brokers can now offer proven direct-source income, employment and asset verification under their own name

NEW YORK CITY, N.Y., Sept. 16, 2026 (SEND2PRESS NEWSWIRE) — Argyle, the leading consumer-permissioned verification platform, today announced the launch of a new solution that enables wholesale mortgage lenders to extend income, employment, and asset verification across their broker networks with a broker-branded borrower experience. The solution is available through Argyle’s Verification API as well as through Encompass® TPO Connect from ICE Mortgage Technology®.

argyle logo
Image caption: Argyle logo.

Argyle’s verification experience is already used by retail mortgage lenders to move borrowers through income, employment and asset verification in minutes. Extending that same experience to wholesale requires accounting for a different relationship: the broker, not the lender, is the borrower’s primary point of contact. Argyle’s new solution preserves that relationship by including the broker’s name and contact information in verification invites, so borrowers recognize who the request came from and know exactly who to contact with questions.

While the experience reflects the broker relationship, the process behind it is unchanged. Borrowers share their income, employment and asset data straight from the payroll or bank source, and the lender receives GSE-approved direct-source documentation to underwrite the file. Where payroll and banking connectivity isn’t available, brokers can offer document-based income verification within the same flow.

For wholesale lenders using Argyle’s Verification API or Encompass TPO Connect, the new solution delivers:

  • Faster turn times to clear to close: Standardized, direct-source documentation supports cleaner files, reducing underwriting follow-up and back-and-forth with brokers and borrowers.
  • One setup across the broker channel: A single configuration generates broker-specific invites, eliminating the need to build or maintain a separate setup for each broker.
  • A more competitive offering for brokers — Lenders can offer brokers a lower-cost verification option than they absorb today, with document-based income verification available as a fallback.

For brokers, it delivers:

  • Broker-branded borrower communications: Verification invites include the broker’s name and contact information, so the broker remains the borrower’s point of contact throughout the process.
  • Lower verification costs: Brokers can access consumer-permissioned verification at a lower price point than traditional verification options.
  • Less back-and-forth: Direct-source verification can reduce document collection and follow-up, helping brokers move loans forward faster.

“Wholesale is a part of the mortgage market we’ve wanted to serve well for a long time,” said John Hardesty, chief revenue officer at Argyle. “Brokers have earned the trust and relationships they build with borrowers, and now they can offer the same fast, direct-source verification experience under their own name while wholesale lenders extend Argyle across their broker networks.”

“Consistency creates a smoother path from application to closing,” said Rebecca Erb, AVP product manager at PwrTPO. “When income, employment, and asset documentation comes back the same way every time, our underwriters spend less time on follow-up requests and more time clearing loans. Giving our TPO partners a streamlined validation experience that includes their name in borrower communications, reduces documentation, and comes at a lower cost creates real value for both our partners and their borrowers.”

The broker-branded borrower experience is available now to wholesale mortgage lenders through Argyle’s Verification API or through Encompass TPO Connect. Wholesale lenders can learn more or contact us to get started at argyle.com/contact-sales.

About Argyle

Argyle is the leading consumer-permissioned verification platform empowering consumers to share their income, employment, and asset data through consumer-directed payroll and bank connections. With Argyle, lenders automate verification workflows to save time, reduce fraud and compliance risks, lower costs and build better product experiences. As an authorized supplier for Fannie Mae’s Desktop Underwriter® validation service and an approved service provider supporting Freddie Mac’s Loan Product Advisor® asset and income modeler (AIM), Argyle empowers mortgage lenders to receive the paystubs and W-2s applicants share, understand applicants’ ability to pay and improve loan quality—all at up to 80% less cost. Argyle’s commitment to innovation is backed by investors including Bain Capital Ventures, Checkr, Mastercard and SignalFire.

For more information on Argyle’s industry-leading verification platform, visit https://www.argyle.com/.

Tags: @withArgyle

Logo link for media: https://res.cloudinary.com/argyle-media/image/upload/fl_preserve_transparency/v1769090922/Argyle%20Logo/Argyle%20Logo%202026/logo-white.jpg?_s=public-apps

NEWS SOURCE: Argyle


This press release was issued on behalf of the news source (Argyle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/argyle-extends-its-mortgage-verification-experience-to-the-wholesale-channel-with-the-launch-of-a-broker-branded-borrower-experience/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138201 NOREL-3B


Atlantic Bay builds on Southern growth with expansion into Louisiana

Baton Rouge native Lindsay Barbera to lead Atlantic Bay's Louisiana team as Area Sales Manager

BATON ROUGE, La. and VIRGINIA BEACH, Va., Sept. 15, 2026 (SEND2PRESS NEWSWIRE) — Atlantic Bay Mortgage Group LLC (Atlantic Bay) today announced the opening of its first Louisiana branch in Baton Rouge, extending its’ presence across the South and giving Louisiana homebuyers access to a wide range of mortgage options, local expertise, and the technology and resources of an established lender.

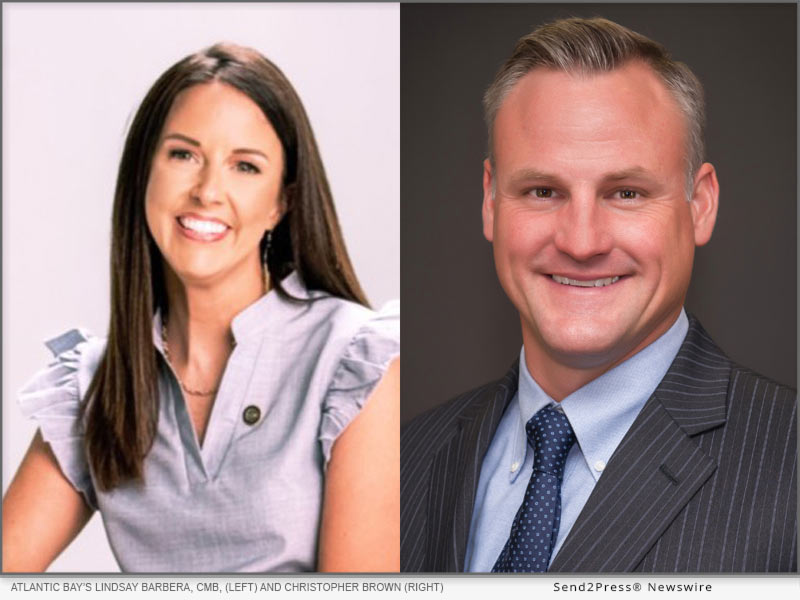
Atlantic Bay's Lindsay Barbera, CMB, (left) and Christopher Brown (right)
Image caption: Atlantic Bay’s Lindsay Barbera, CMB, (left) and Christopher Brown (right).

Lindsay Barbera, CMB, AMP, CMS, will lead Atlantic Bay’s Louisiana team as Area Sales Manager. A Baton Rouge native and LSU graduate, Barbera has spent more than 20 years in Louisiana’s mortgage industry, cultivating relationships across the state’s business and housing communities throughout a career spanning servicing, operations, product development, and sales. She will report to Atlantic Bay’s EVP and Southern Regional Manager, Christopher Brown.

“Growing in Louisiana isn’t about showing up with a playbook. It’s about understanding the people, earning trust and being part of the community,” said Barbera. “Atlantic Bay brings an incredible culture and support system that gives our team more ways to serve homebuyers and industry partners. Put that together with a team that understands Louisiana, and I think we have a strong foundation for long-term success.”

“Louisiana is a natural next step in Atlantic Bay’s growth across the South,” shared Brown. “We want our Mortgage Bankers to have the infrastructure and resources to compete at a high level without losing the local relationships and personal approach that have made them successful in the first place. Lindsay knows this market, knows its people and knows what it takes to grow here.”

Founded in Virginia Beach in 1996, Atlantic Bay has grown from a four-person startup to an award-winning, multi-state mortgage lender with more than 100 branches, 600-plus employees and a footprint that now stretches across much of the South, including Georgia, Florida, Alabama, Tennessee, North Carolina, South Carolina, Texas and Louisiana. The Louisiana expansion comes amid continued momentum across the region, where Atlantic Bay has added 12 new team members since July, including Justin Atterberry, who leads the company’s growth efforts in Texas.

Atlantic Bay is seeking experienced Mortgage Bankers who want strong operational and marketing support while continuing to build on the relationships and reputation they have established in their markets. Learn more at https://www.joinatlanticbay.com/.

About Atlantic Bay Mortgage Group

Atlantic Bay Mortgage Group LLC is a privately held, full-service mortgage lender headquartered in Virginia Beach, Virginia. Atlantic Bay offers a wide range of residential mortgage products, including Conventional, FHA, VA, USDA and jumbo loans, serving homebuyers and homeowners across multiple states. Known for its customer-first culture and commitment to service excellence, Atlantic Bay combines local lending expertise with innovative technology to deliver a personalized mortgage experience. The company is consistently recognized as a top workplace and is deeply committed to giving back to the communities it serves through charitable initiatives and partnerships. To learn more, visit https://www.atlanticbay.com/.

Atlantic Bay Mortgage Group L.L.C. NMLS #72043 (nmlsconsumeraccess.org) provides Equal Employment Opportunities and is an Equal Opportunity Lender located at 600 Lynnhaven Parkway Suite 100 Virginia Beach, Virginia, 23452.

Tags: @AtlanticBay #mortgage

NEWS SOURCE: Atlantic Bay Mortgage Group LLC


This press release was issued on behalf of the news source (Atlantic Bay Mortgage Group LLC), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/atlantic-bay-builds-on-southern-growth-with-expansion-into-louisiana/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138186 NOREL-3B


Atlantic Bay builds on Southern growth with expansion into Louisiana

Baton Rouge native Lindsay Barbera to lead Atlantic Bay's Louisiana team as Area Sales Manager

BATON ROUGE, La. and VIRGINIA BEACH, Va., Sept. 15, 2026 (SEND2PRESS NEWSWIRE) — Atlantic Bay Mortgage Group LLC (Atlantic Bay) today announced the opening of its first Louisiana branch in Baton Rouge, extending its’ presence across the South and giving Louisiana homebuyers access to a wide range of mortgage options, local expertise, and the technology and resources of an established lender.

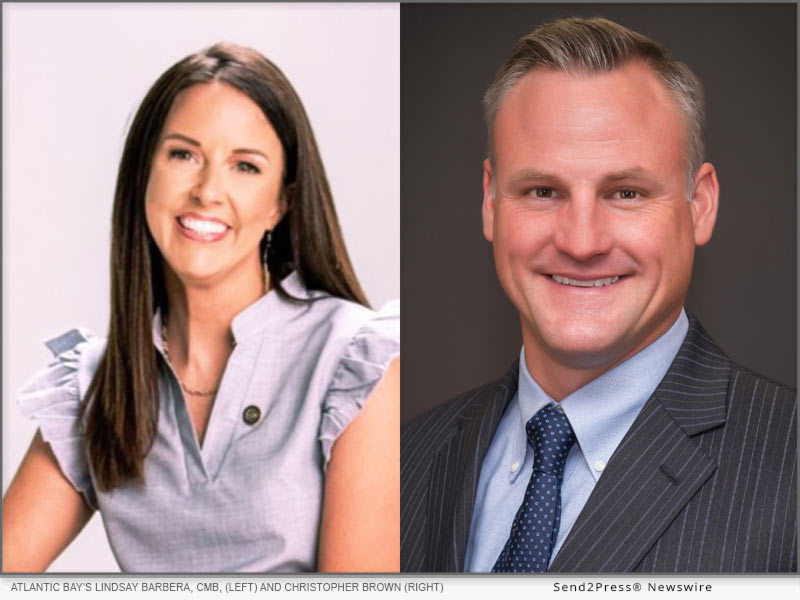
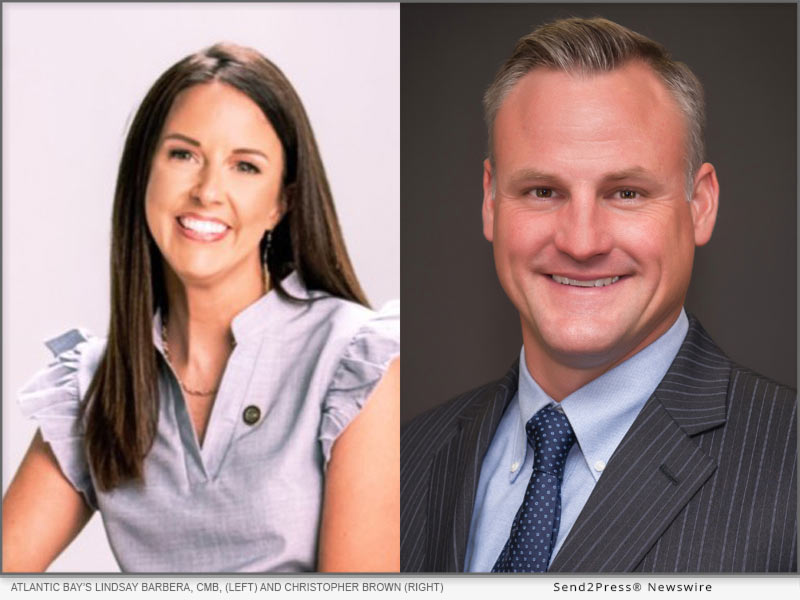
Atlantic Bay's Lindsay Barbera, CMB, (left) and Christopher Brown (right)
Image caption: Atlantic Bay’s Lindsay Barbera, CMB, (left) and Christopher Brown (right).

Lindsay Barbera, CMB, AMP, CMS, will lead Atlantic Bay’s Louisiana team as Area Sales Manager. A Baton Rouge native and LSU graduate, Barbera has spent more than 20 years in Louisiana’s mortgage industry, cultivating relationships across the state’s business and housing communities throughout a career spanning servicing, operations, product development, and sales. She will report to Atlantic Bay’s EVP and Southern Regional Manager, Christopher Brown.

“Growing in Louisiana isn’t about showing up with a playbook. It’s about understanding the people, earning trust and being part of the community,” said Barbera. “Atlantic Bay brings an incredible culture and support system that gives our team more ways to serve homebuyers and industry partners. Put that together with a team that understands Louisiana, and I think we have a strong foundation for long-term success.”

“Louisiana is a natural next step in Atlantic Bay’s growth across the South,” shared Brown. “We want our Mortgage Bankers to have the infrastructure and resources to compete at a high level without losing the local relationships and personal approach that have made them successful in the first place. Lindsay knows this market, knows its people and knows what it takes to grow here.”

Founded in Virginia Beach in 1996, Atlantic Bay has grown from a four-person startup to an award-winning, multi-state mortgage lender with more than 100 branches, 600-plus employees and a footprint that now stretches across much of the South, including Georgia, Florida, Alabama, Tennessee, North Carolina, South Carolina, Texas and Louisiana. The Louisiana expansion comes amid continued momentum across the region, where Atlantic Bay has added 12 new team members since July, including Justin Atterberry, who leads the company’s growth efforts in Texas.

Atlantic Bay is seeking experienced Mortgage Bankers who want strong operational and marketing support while continuing to build on the relationships and reputation they have established in their markets. Learn more at https://www.joinatlanticbay.com/.

About Atlantic Bay Mortgage Group

Atlantic Bay Mortgage Group LLC is a privately held, full-service mortgage lender headquartered in Virginia Beach, Virginia. Atlantic Bay offers a wide range of residential mortgage products, including Conventional, FHA, VA, USDA and jumbo loans, serving homebuyers and homeowners across multiple states. Known for its customer-first culture and commitment to service excellence, Atlantic Bay combines local lending expertise with innovative technology to deliver a personalized mortgage experience. The company is consistently recognized as a top workplace and is deeply committed to giving back to the communities it serves through charitable initiatives and partnerships. To learn more, visit https://www.atlanticbay.com/.

Atlantic Bay Mortgage Group L.L.C. NMLS #72043 (nmlsconsumeraccess.org) provides Equal Employment Opportunities and is an Equal Opportunity Lender located at 600 Lynnhaven Parkway Suite 100 Virginia Beach, Virginia, 23452.

Tags: @AtlanticBay #mortgage

NEWS SOURCE: Atlantic Bay Mortgage Group LLC


This press release was issued on behalf of the news source (Atlantic Bay Mortgage Group LLC), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/atlantic-bay-builds-on-southern-growth-with-expansion-into-louisiana/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138186 NOREL-3B


Vice Capital Markets expands bid tape capabilities to include VantageScore data

New capability comes as FHFA directs Fannie Mae and Freddie Mac to approve VantageScore 4.0 for all lenders

NOVI, Mich., Sept. 10, 2026 (SEND2PRESS NEWSWIRE) — Vice Capital Markets, a leading mortgage hedge advisory firm for independent lenders, banks and credit unions, today announced that its capital markets platform now supports the inclusion of VantageScore® credit scores on mortgage bid tapes, providing lenders and investors with greater visibility into loan-level credit characteristics during the secondary market execution process.

Vice Capital Markets
Image caption: Vice Capital Markets.

Lenders can now include VantageScore data, along with other loan-level characteristics, in the bid packages they provide investors. The score moves through the existing bid-tape process, so no separate submission is required. Lenders can also compare completed bid results against the credit profile of the loans they sold.

The announcement comes as the mortgage industry enters a new era of credit scoring competition. On Sept. 4, Federal Housing Finance Agency (FHFA) Director Bill Pulte announced that Fannie Mae and Freddie Mac would immediately approve all lenders to use VantageScore 4.0, following what Pulte described as a successful initial rollout in which 50 lenders had already delivered loans using VantageScore.

“Bill Pulte’s announcement is a significant moment for the mortgage industry,” said Chris Bennett, chairman of Vice Capital Markets. “If a lender is going to originate with VantageScore, the score shouldn’t disappear the moment the loan goes out for bid. We’ve been focused on ensuring our clients have the data and tools they need to make better secondary market decisions. Putting the score on the tape keeps it in front of the people pricing the loan.”

Vice Capital Markets continues to invest in technology and data integrations designed to help mortgage lenders improve their secondary market execution, manage interest rate risk and gain greater visibility into the factors driving investor valuations. Learn more at www.vicecapitalmarkets.com.

About Vice Capital Markets

Since 2001, Vice Capital Markets has expertly navigated interest rate risk and driven profitability on over $1 trillion in MBS trades and mortgage-related transactions for a diverse range of financial institutions. Utilizing proprietary risk-management models and an advanced investor and agency platform, Vice Capital has enabled clients to enhance their secondary market strategies and achieve optimal sales gains.

The company’s Vice Execution Portal™ (ViceEx) is an all-inclusive, whole-loan trading platform that enables lenders and secondary market managers to seamlessly send and receive aggregator bulk bids, compare agency executions with customizable retained or co-issue servicing values while guaranteeing the best execution that might otherwise be missed in a manual process.

With traders averaging over a decade of experience, Vice Capital brings the expertise necessary to tackle market challenges and consistently deliver secure and effective profit growth for its clients. For further information, visit www.vicecapitalmarkets.com or call 248-869-8100.

NEWS SOURCE: Vice Capital Markets


This press release was issued on behalf of the news source (Vice Capital Markets), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vice-capital-markets-expands-bid-tape-capabilities-to-include-vantagescore-data/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138064 NOREL-3B


Friday Harbor’s AI pre-underwriting platform integrates to the Freddie Mac Income Calculator API

Lenders can now calculate qualifying income for wage earners with variable income more efficiently

SEATTLE, Wash., Sept. 10, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, today announced its integration to the Freddie Mac Income Calculator API. Lenders can now determine calculated monthly income for wage earners, including borrowers with variable income, in minutes while helping preserve eligibility for certain representation and warranty (R&W) relief tied to the income calculation.

Friday Harbor logo
Image caption: Friday Harbor.

The Friday Harbor product, which automatically digitizes borrower paystubs and W-2s from loan origination system (LOS) integrations or direct upload, generates and updates loan conditions as new documents are added and attaches them to the loan file through its dynamic needs list and Income & Asset Sandbox. Using the digitized borrower paystub and W-2 data, Freddie Mac’s Income Calculator API determines a calculated monthly income while Friday Harbor flags potential issues and provides findings tied to Freddie Mac Single-Family Seller/Servicer Guide requirements. The Freddie Mac Income Calculator Certificate is retained with the loan file to help preserve eligibility for applicable R&W relief.

“Having the Freddie Mac Income Calculator available inside Friday Harbor changes the conversation with borrowers,” said Rob Jewett, chief operating officer at NewFed Mortgage Corp. “We can give borrowers a straight answer sooner, keep files moving and avoid surprises later in the process.”

“Variable wage income remains one of the more complicated income scenarios loan production teams face,” said Theo Ellis, CEO and Founder of Friday Harbor. “We’re proud to bring the new Freddie Mac Income Calculator API to pre-underwriting, giving originators reliable qualifying income calculations earlier in the origination process. That means fewer surprises later, cleaner files for underwriting and greater confidence that loans are ready for sale.”

The Freddie Mac Income Calculator API uses borrower paystubs and W-2s to determine calculated monthly income for wage-earning borrowers, including borrowers with variable income. The resulting income calculation can be submitted through Loan Product Advisor® (LPA®), Freddie Mac’s automated underwriting system (AUS), to support eligibility for R&W relief related to the income calculation.

Friday Harbor now supports automated calculated monthly income assessments for loans delivered to both Freddie Mac and Fannie Mae. Lenders can learn more about Friday Harbor’s integrations or request a demo at https://fridayharbor.ai.

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech @FreddieMac

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbors-ai-pre-underwriting-platform-integrates-to-the-freddie-mac-income-calculator-api/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138057 NOREL-3B


Optimal Blue announces initial speaker lineup for 2027 Summit

Registration now open for premier event bringing together industry leaders, leading economists, and Optimal Blue innovators to shape what's next in mortgage

PLANO, Texas, Sept. 9, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced its initial speaker lineup for its 2027 Optimal Blue Summit, including Analyst, ESPN Monday Night Football, 3-Time Super Bowl-Winning Quarterback, Pro Football Hall of Famer Troy Aikman. The third annual event shaping what’s next in mortgage will take place February 1–3, 2027 at the JW Marriott Phoenix Desert Ridge Resort and Spa in Scottsdale, Ariz., and bring together the industry’s leading executives, economists and innovators. Registration is now open at Summit.OptimalBlue.com, with early-bird pricing available for a limited time.

Optimal Blue logo.
Image caption: Optimal Blue.

As a leader in AI-driven innovation and the industry’s only end-to-end capital markets platform, Optimal Blue’s annual conference is designed to help mortgage leaders and professionals navigate a rapidly changing market. It will provide more than 500 attendees from across the mortgage ecosystem with access to actionable insights, best-in-class technologies, leading experts and professional networks to help optimize their performance and profitability, all in one Scottsdale destination. Attendees will benefit from a comprehensive agenda featuring to-be-announced speakers and breakout sessions focused on market dynamics, lender trends, rate conditions, secondary-market strategy, product intelligence, and peer insight, plus a front-row view of Optimal Blue innovation, to help them navigate the year ahead.

Ahead of serving as announcer for The Big Game in February, Troy Aikman will take the stage in Scottsdale for a fireside chat with Optimal Blue Chief Executive Officer Joe Tyrrell. The legendary quarterback, Emmy-nominated broadcaster, entrepreneur, and philanthropist will inspire and motivate attendees through lessons learned from his storied career leading high-performing teams on and off the field.

Highlighted industry experts planned to speak at the 2027 Optimal Blue Summit include:

  • Robert (Bob) Broeksmit, CMB, president and chief executive officer, Mortgage Bankers Association
    One of the mortgage industry’s most recognizable and trusted voices, Bob Broeksmit is a senior finance executive with over 35 years of experience across mortgage operations, secondary marketing and servicing. With deep knowledge across all aspects of mortgage lending activities, Bob advocates for more than 2,000 member companies on issues of critical importance and has served as an expert witness in complex mortgage underwriting cases.
  • Michael Fratantoni, Ph.D., chief economist, Mortgage Bankers Association
    Michael Fratantoni oversees MBA’s economic forecasts, industry surveys and benchmarking studies, as well as leads its award-winning economics team. He also serves on the board of CONVERGENCE Collaborative. A leading economist and expert on the trends shaping the mortgage market, Michael delivers data-driven insights to inform and educate mortgage professionals.
  • Joe Tyrrell, chief executive officer, Optimal Blue
    Joe Tyrrell leads Optimal Blue’s strategy to empower lenders with modern technology, actionable data, and AI-driven innovation across the mortgage capital markets lifecycle. With more than 25 years of fintech leadership experience touching all aspects of origination and secondary marketing technologies, he is accelerating the company’s AI-first vision that combines trusted intelligence, automation, and emerging technologies to help lenders make better decisions, operate more efficiently, and unlock new competitive advantages, no matter the market.
  • Erin Wester, chief product officer, Optimal Blue
    Erin Wester oversees product strategy and innovation across Optimal Blue’s mortgage capital markets platform, driving AI-powered solutions that help lenders make smarter decisions, reduce complexity, and improve performance. A mortgage fintech leader with more than 15 years of industry experience, she is known for combining customer-centric innovation, deep industry expertise, and responsible AI leadership to help shape the future of mortgage lending.

“The Optimal Blue Summit is where the conversations shaping the future of mortgage lending turn into action,” said Sara Holtz, chief marketing officer at Optimal Blue. “By bringing together industry and executive voices, emerging technologies and market intelligence, we’re helping lenders navigate change, uncover opportunity, and make better decisions so they can move forward with greater confidence. And this is only the beginning as we continue to add to our lineup.”

In addition to a robust expert speaker roster, the event will feature:

  • Reveals of the latest AI-driven innovations, powered by the new Optimal Blue AI Labs
  • Hands-on trainings, product demonstrations, and client feedback forums that shape future product direction
  • Meaningful connections and networking opportunities with leaders and decision-makers from across the mortgage ecosystem

To learn more about Optimal Blue Summit 2027 and to take advantage of early bird pricing before it ends Oct. 31, visit Summit.OptimalBlue.com.

About Optimal Blue

Optimal Blue powers strategic performance across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes optimize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue helps deliver measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-announces-initial-speaker-lineup-for-2027-summit/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138048 NOREL-3B


Down Payment Resource identifies 2,746 homeownership programs nationwide in Q2 2026

Program count rises to a new high, with notable growth in grants, multi-unit and manufactured housing options as affordability pressures persist

ATLANTA, Ga., July 22, 2026 (SEND2PRESS NEWSWIRE) — Down Payment Resource (DPR), the housing industry’s leading technology for connecting homebuyers with homeownership programs, today released its Q2 2026 Homeownership Program Index (HPI) report, identifying 2,746 programs nationwide. The total represents an increase of 67 programs from Q1 2026, reflecting continued expansion of resources designed to improve affordability and access to homeownership, and is a new survey high.

Down Payment Resource
Image caption: Down Payment Resource (DPR).

Homeownership programs like down payment assistance (DPA) provide meaningful financial support that strengthens borrower profiles. By reducing loan-to-value ratios and covering upfront costs such as down payments, closing costs and rate buydowns, these programs help convert qualified demand into successful homeownership outcomes.

One standout finding this quarter is the growing number of grant programs, which require no repayment. Grant programs rose 6% from Q1 to Q2, with 234 programs representing 9% of all program types.

The Q2 findings also reveal a broad span in the type of assistance available. Of the 2,746 programs identified, 80% support new construction and 93% support existing construction, meaning builders and their lending partners have a wide range of programs to offer buyers regardless of whether they are purchasing a newly built home or an existing one.

Additionally, with 62% of programs allowing income limits above $100,000, and 291 programs carrying no income restrictions at all, down payment programs are not “niche resources” for a narrow audience. They are mainstream financial tools that the housing industry has historically undersold and an opportunity for homebuilders, lenders and real estate professionals to differentiate themselves by presenting every qualified buyer with options.

“Quarter after quarter, the universe of available programs keeps expanding, and so does the flexibility they offer,” said Rob Chrane, founder and CEO of Down Payment Resource. “The surge in grant programs is a good example. These aren’t resources for a narrow slice of buyers. They’re mainstream financial strategies that lenders and real estate professionals should be putting in front of every qualified borrower.”

KEY HPI REPORT FINDINGS

An examination of the 2,746 homeownership programs on July 1, 2026, resulted in the following key findings:

  • Count reaches new high: The total number of programs increased to 2,746, up from 2,679 in Q1 2026. Active and funded programs total 2,114 (77%), providing immediate opportunities for homebuyers across the country.
  • Grants surge: Grant programs increased 6% during Q2 to 234 programs. Grants now represent 9% of all program types, offering significant value for buyers seeking assistance that does not add to their debt burden.
  • More support for new and existing construction: 2,209 (80%) of programs support new construction, 2,544 (93%) support existing construction and 2,209 (80%) support both, giving homebuilders and lenders broad coverage regardless of what a buyer is purchasing.
  • Multi-unit programs expand: Programs supporting multi-unit properties (2–4 units) increased to 962, up 3% from Q1. Multi-unit eligibility expands access for buyers seeking rental income potential alongside homeownership, which is a growing consideration in today’s affordability environment.
  • Support for manufactured housing grows: Programs supporting manufactured homes increased to 1,089, representing 40% of all programs, a gain of 3% from Q1. Manufactured housing continues to be one of the most accessible lower-cost homeownership pathways, and expanded program support broadens options for buyers in markets where site-built homes remain out of reach.
  • Second mortgages remain dominant: Second-mortgage programs make up 56% of all program types, offering flexible structures such as deferred or forgivable loans that reduce upfront costs for buyers. Combined assistance programs account for 10% of programs and first-mortgage programs represent 9%.
  • More programs with no income limits: 291 programs (11%) carry no income restrictions, 2% higher than the previous quarter. These programs give lenders greater flexibility to qualify a broader range of borrowers including higher-income households.
  • Support for first-time and first-generation buyers expands: 1,696 programs (62%) are available to first-time homebuyers, a 2% increase from Q1. 35 programs support first-generation buyers, up 6% from Q1, continuing to expand access for those entering the market without family homeownership history.
  • Local providers lead program availability: Municipalities account for the largest share of programs at 39% (1,068), followed by nonprofits at 22% (601) and state housing finance agencies at 18% (485). Local HFAs represent an additional 8% (207 programs). Tribal organizations grew to 56 programs, up 4% from the previous quarter, reflecting expanding community-based program delivery.

A more detailed analysis of the Q2 2026 HPI findings, including infographics and examples of the programs described in this release, can be found on DPR’s website at: https://downpaymentresource.com/professional-resource/down-payment-assistance-continues-to-expand-in-q2-2026-reaching-2746-programs-nationwide/

For a complete list of homebuyer assistance programs by state, visit (PDF): https://downpaymentresource.com/wp-content/uploads/2026/07/HPI-state-by-state-data.Q22026.pdf

Members of the media are encouraged to contact DPR for data specific to their reporting needs.

METHODOLOGY:

Published quarterly, DPR’s HPI surveys the funding status, eligibility rules and benefits of U.S. homeownership programs administered by state and local housing finance agencies, municipalities, nonprofits and other housing organizations. DPR communicates with over 1,400 program providers throughout the year to track and update the country’s wide range of homeownership programs, including down payment and closing cost programs, Mortgage Credit Certificates (MCCs) and affordable first mortgages, in the DOWN PAYMENT RESOURCE® database.

ABOUT DOWN PAYMENT RESOURCE:

Down Payment Resource (DPR) is the mortgage industry’s affordability intelligence platform, operationalizing down payment assistance (DPA) at scale for lenders, MLSs and API users. Its embedded intelligence helps automate DPA eligibility, decisioning and delivery, connecting homebuyers with the assistance they need through a national database of over 2,700 programs. DPR’s technology is used by seven of the top 25 mortgage lenders, two of the largest real estate listing websites and 600,000 real estate agents. For more information, visit https://www.downpaymentresource.com/.

X: @DwnPmtResource #downpaymentassistance #downpayment

LOGO link for media: https://www.Send2Press.com/300dpi/26-0722-s2p-dpresc-300dpi.webp

NEWS SOURCE: Down Payment Resource


This press release was issued on behalf of the news source (Down Payment Resource), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/down-payment-resource-identifies-2746-homeownership-programs-nationwide-in-q2-2026/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136959 NOREL-3B


Argyle and The BIG Point of Sale named 2026 Connections Award winners by PROGRESS in Lending

Recognized for embedding payroll-based VOIE directly into the mortgage origination workflow through ICE Mortgage Technology's Encompass Partner Connect

NEW YORK CITY, N.Y., July 22, 2026 (SEND2PRESS NEWSWIRE) — Argyle, the leading consumer-permissioned verification platform, and The BIG Point of Sale today announced they have been named winners of the 2026 Connections Award by PROGRESS in Lending. The award honors the most impactful partnerships, integrations and acquisitions advancing the mortgage industry, recognizing the companies for an integration that embeds verification of income and employment (VOIE) directly into the loan origination process through ICE Mortgage Technology’s Encompass Partner Connect® framework.

argyle logo
Image caption: argyle logo.

“Being named a Connections Award winner alongside Argyle validates the approach we’ve taken from day one: verification should happen where the loan is actually originated, not as a separate step borrowers and processors have to manage on the side,” said Jerry Melia, president at The BIG Point of Sale. “This recognition reflects the work our team has put into making that experience feel seamless for lenders and borrowers alike.”

“Argyle empowers consumers to securely share data directly from their payroll and other income-related accounts with authorized lenders,” said John Hardesty, senior vice president of revenue at Argyle. “Lenders can embed income and employment verification directly into The BIG Point of Sale, accessing direct-source data earlier in the process and eliminating the manual back-and-forth that has historically slowed things down for borrowers and operations teams.”

Income and employment verification has historically been one of the more manual, time-consuming and expensive parts of the mortgage process. Borrowers are typically required to locate and upload paystubs, W-2s and other documentation, while lenders spend additional time chasing missing information, following up and re-entering data across systems.

With Argyle, The BIG Point of Sale integration changes that by making verification a natural part of the borrower application experience. Loan officers can initiate VOIE requests from The BIG Point of Sale on any device during or after the application process. Borrowers can easily share their real-time income and employment data through consumer-directed payroll connections— no document uploads required. After completing the Argyle connection flow, required data including VOIE, paystubs and W-2s is returned in real time and automatically posted to the Encompass eFolder through native Encompass Partner Connect functionality and workflow automation rules.

The integration also supports GSE-eligible verification data and reference IDs within the same workflow. As an authorized supplier for Fannie Mae’s Desktop Underwriter® validation service and an approved service provider for Freddie Mac’s Loan Product Advisor® asset and income modeler (AIM), Argyle enables lenders to access direct-source data and GSE reference IDs without leaving the point-of-sale environment or reordering a VOIE through separate systems.

The business impact of the integration is already visible in the field. Since embedding Argyle into the borrower workflow within The BIG Point of Sale, Absolute Home Mortgage increased its automated verification success rate from 10% to 48%. The lender reduced reliance on processor intervention and manual borrower follow-up while improving file completeness entering underwriting—with nearly half of loans submitted for underwriting already including paystubs and W-2s synced through Fannie Mae’s Day 1 Certainty® framework.

Key benefits lenders gain through the integration:

  • Speed: Payroll-connected VOIE data arrives in Encompass in real time, reducing delays between application and underwriting.
  • Cost reduction: Automated payroll-based VOIE can significantly reduce verification costs compared to legacy database-driven services.
  • GSE support: Lenders can qualify for representations and warranties relief through the same workflow, helping reduce repurchase risk exposure.
  • Better borrower experience: Borrowers complete verification from a mobile device in minutes rather than gathering and submitting paper documents.

ABOUT ARGYLE

Argyle is the leading consumer-permissioned verification platform empowering consumers to share their income, employment, and asset data through consumer-directed payroll and bank connections. With Argyle, lenders automate verification workflows to save time, reduce fraud and compliance risks, lower costs and build better product experiences. As an authorized supplier for Fannie Mae’s Desktop Underwriter® validation service and an approved service provider supporting Freddie Mac’s Loan Product Advisor® asset and income modeler (AIM), Argyle empowers mortgage lenders to receive the paystubs and W-2s applicants share, understand applicants’ ability to pay and improve loan quality—all at up to 80% less cost. Argyle’s commitment to innovation is backed by investors including Bain Capital Ventures, Checkr, Mastercard and SignalFire. For more information, visit https://www.argyle.com/

ABOUT THE BIG POINT OF SALE

The BIG Point of Sale, a Mortgage Automation Technologies solution, is a configurable point-of-sale platform built to help mortgage lenders simplify and automate the loan origination process. Through native integrations with ICE Mortgage Technology’s Encompass Partner Connect framework and verification partners like Argyle, The BIG Point of Sale embeds verification, disclosures and workflow automation directly into the borrower application experience, helping lenders reduce cycle times and manual work from application through closing. The BIG Point of Sale is based in Fairfield, New Jersey. For more information, visit www.thebigpos.com

Tags: @withArgyle

NEWS SOURCE: Argyle


This press release was issued on behalf of the news source (Argyle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/argyle-and-the-big-point-of-sale-named-2026-connections-award-winners-by-progress-in-lending/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136953 NOREL-3B


Informative Research names Ajay Trilokeshwaran chief technology officer

GARDEN GROVE, Calif., July 21, 2026 (SEND2PRESS NEWSWIRE) — Informative Research (IR), a leading technology provider of data-driven credit and verification solutions for the lending industry, today announced the promotion of Ajay Trilokeshwaran to chief technology officer (CTO). In his new role, Trilokeshwaran will lead the company’s product and technology execution, overseeing platform development, application engineering, infrastructure and cloud strategy to support business growth.

Ajay Trilokeshwaran of Informative Research
Image caption: Ajay Trilokeshwaran of Informative Research.

Trilokeshwaran brings more than 20 years of enterprise technology experience to the role, with deep expertise in platform modernization, large-scale system integrations and DevOps strategy. Since joining Informative Research, he has been the driving force behind the company’s core verification infrastructure, building systems that help lenders meet investor guidelines and capture GSE incentive programs through Fannie Mae and Freddie Mac.

Trilokeshwaran’s work has turned what was once a set of separate capabilities into something greater than the sum of its parts. IR’s verification platform operates as a unified system where credit, income, employment and asset data flow together intelligently, giving lenders a single infrastructure they can build on. His contributions have helped lenders across the industry manage verification costs and develop consistent, reliable verification processes.

“Ajay has been instrumental in shaping what Informative Research is today,” said President Matt Orlando. “His technical vision, his ability to build and lead high-performing teams, and his deep understanding of what lenders need have made him the right person to take the reins as we continue to grow.”

Trilokeshwaran was recognized as a 2024 HousingWire Tech Trendsetter for his leadership in advancing scalable technology in the mortgage industry. His work has also contributed to IR’s recognition on the HousingWire Tech100 list over multiple years.

“I’m motivated to build things that actually move the needle for the people using them,” said Trilokeshwaran. “Our team has and continues to pursue that goal, and there’s still more to do. I’m grateful for the trust and recognition, and I’m looking forward to what comes next.”

About Informative Research

Informative Research, a Stewart company, is a premier technology provider delivering data-driven credit and verification solutions to the lending community. The solutions provider currently serves mortgage companies, banks and lenders throughout the United States. The company is recognized for streamlining the loan process with its straightforward service model, progressive solutions and cutting-edge technology. To learn more, visit https://www.informativeresearch.com.

NEWS SOURCE: Informative Research


This press release was issued on behalf of the news source (Informative Research), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/informative-research-names-ajay-trilokeshwaran-chief-technology-officer/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136942 NOREL-3B


Friday Harbor adds USDA loans to its AI pre-underwriting platform

Lenders can identify USDA eligibility issues and GUS evaluation requirements before files reach underwriting

SEATTLE, Wash., July 21, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, today announced support for USDA loans. The new capability enables lenders to identify documentation gaps, eligibility issues and changes that require updated Guaranteed Underwriting System (GUS) findings before loan files reach underwriting, helping reduce rework and deliver a more predictable path to closing for both lending teams and borrowers.

Friday Harbor logo
Image caption: Friday Harbor.

“USDA loans have always required a level of expertise that many production teams simply don’t encounter every day,” said Theo Ellis, co-founder and CEO of Friday Harbor. “We’ve built that expertise directly into the hands of loan officers, so they know when a file needs attention before it reaches underwriting. That means underwriters spend less time working through preventable conditions, production teams keep loans moving and borrowers get to closing with fewer surprises.”

Friday Harbor continuously evaluates USDA loan files as they evolve, identifying documentation gaps, eligibility issues and changes that require updated GUS findings as new information is added to the file. Instead of relying on manual judgment or institutional knowledge, production teams receive real-time guidance that helps resolve issues before the loan reaches underwriting. The result is cleaner loan files, fewer underwriting touches and more predictable production timelines, while borrowers benefit from fewer avoidable delays and clearer expectations throughout the mortgage process.

Backed by the U.S. Department of Agriculture’s Rural Development program, USDA loans expand access to homeownership by allowing eligible borrowers to purchase homes with no down payment. Because the program has unique eligibility and documentation requirements, lenders rely on GUS, an automated underwriting system (AUS), to evaluate borrower qualifications and program eligibility before returning underwriting findings.

Those findings can change throughout the origination process. Updates to borrower information, income, assets or property details may require another GUS evaluation, yet it is not always clear when one is needed. Loan officers often rerun files unnecessarily or risk delaying underwriting when required evaluations are overlooked. Friday Harbor helps production teams determine when updated GUS findings are needed, reducing unnecessary reruns while helping ensure required evaluations aren’t missed.

Lenders can learn more about USDA loan support in Friday Harbor or request a demo at https://fridayharbor.ai.

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech #USDA

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbor-adds-usda-loans-to-its-ai-pre-underwriting-platform/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136935 NOREL-3B


Volume growth from existing staff ranks as lenders’ top priority for the second half of 2026, The Mortgage Collaborative’s survey finds

Lenders also focused on early-stage AI adoption and reducing cost-per-loan

SAN DIEGO, Calif., July 20, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s largest independent cooperative network for mortgage lenders, today released results from its June 2026 Pulse of the Network survey. The biannual survey gathered input from mortgage lenders, including independent mortgage banks, credit unions and depository institutions, on strategic priorities heading into the second half of 2026.

The Mortgage Collaborative - TMC
Image caption: The Mortgage Collaborative.

According to the survey results, lenders are focused on growth heading into the second half of 2026 and intend to rely mostly on existing staff to achieve that goal. Three-quarters of respondents said their primary growth strategy is to increase production from their current sales team, while 64% plan to recruit experienced loan officers. Overall, 83% said their companies are focused on growth, and 89% expect origination volume to climb in the second half of the year. Most are projecting moderate gains of 5% to 20%, though 17% anticipate a significant jump. Elevated interest rates, tight housing inventory and margin compression remain the biggest obstacles.

Technology ranked second on lenders’ priority lists, though most are still in the exploration phase with AI. While 83% said they are evaluating AI tools across their businesses, only 17% have deployed the technology in live production workflows. The most frequently cited barrier to AI adoption is trust, with a quarter of respondents saying their organizations aren’t yet confident in AI-generated outputs.

Operational efficiency rounded out lenders’ top three priorities, with an emphasis on making better use of existing investments and talent. Reducing loan production costs was the top operational priority for 86% of respondents, followed by vendor and technology consolidation at 64% and reduction in turn times at 56%. Personnel-wise, three-quarters of respondents say they are investing in technology to improve loan officer productivity, and 72% plan to improve compensation and incentive structures to keep top performers.

Borrower retention/recapture ranked as the top secondary market priority by 75% of respondents, in light of the growing opportunity in this area due to gradually declining interest rates. Nearly as many, 72%, are working to broaden their investor and agency relationships, while 69% are strengthening their post-close processes. From a product perspective, respondents identified conventional purchase loans and non-QM lending as the two largest opportunities for volume growth in the second half of the year.

Lenders’ caution around AI also extends to their compliance departments, where automated decisioning now consumes more resources than any other area of compliance, according to 75% of respondents. Nearly half expressed concerns about fair lending risk tied to AI decisioning, and 22% say they haven’t yet fully assessed it. State-level regulatory complexity remains a burden as well, with 53% calling it a meaningful drain on resources.

“The results show a membership that is more confident about volume in the second half of the year, but still disciplined about how they get there,” said Jodi Hall, president and CEO of The Mortgage Collaborative. “Members are prioritizing production from their current teams and technology investment over expansion, and they are asking specific questions about AI governance and per-loan costs.”

TMC conducts the Pulse of the Network survey twice a year to identify what lender members are navigating and where they are seeking support. Results inform programming for TMC’s working groups, lender-only collaboration labs, TMC Insight benchmarking initiatives and conference programming. The survey results are provided at https://mailchi.mp/mtgcoop/pulse-of-the-network.

About The Mortgage Collaborative

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders across the United States through networking, education and advocacy. TMC fosters an environment of collaboration and innovation, ensuring its members succeed regardless of market conditions. For more information, visit mortgagecollaborative.com.

LOGO link for media: https://mortgagecollaborative.com/wp-content/uploads/2025/12/Color-Logo-The-Mortgage-Collaborative-scaled-1.png

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/volume-growth-from-existing-staff-ranks-as-lenders-top-priority-for-the-second-half-of-2026-the-mortgage-collaboratives-survey-finds/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136920 NOREL-3B


Click n’ Close named one of USDA’s Top Wholesale Lenders for 2026

ADDISON, Texas, July 16, 2026 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, received a USDA 2026 Top Wholesale Lender award. The award was presented today at USDA Rural Development’s National Lender of the Year Awards Ceremony in Washington, D.C.

Click n' Close, Inc.
Image caption: Click n’ Close named one of USDA’s Top Wholesale Lenders for 2026.

The USDA National Lender of the Year Awards recognize top lending partners supporting rural homeownership through USDA Rural Development’s Single Family Housing Guaranteed Loan Program. Click n’ Close ranked second nationally in the Top Wholesale Lender category, behind United Wholesale Mortgage.

Click n’ Close offers USDA loans through its wholesale and correspondent channels, including a forgivable second-lien down payment assistance option that can be applied toward closing costs, escrows and prepaids. The company also supports manufactured home financing under the USDA program, expanding the range of eligible property types available to rural homebuyers.

“Rural borrowers often get overlooked by lenders chasing volume in metro markets,” said Jeff Bode, chief executive officer of Click n’ Close. “We built our wholesale platform to serve the brokers working in those communities, and this ranking tells us that approach is paying off for the families they’re helping get into homes.”

The USDA National Lender of the Year Awards Ceremony was held June 17 in Washington, D.C. Soliman Martinez, division manager, accepted the award on Click n’ Close’s behalf. More information on the ceremony is available in the USDA’s news release at https://www.rd.usda.gov/newsroom/news-release/usda-holds-national-lenders-year-award-ceremony-0.

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1959, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at www.clicknclose.com.

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-named-one-of-usdas-top-wholesale-lenders-for-2026/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136847 NOREL-3B


NotaryCam President Brian Webster named a 2026 Inman Best in Finance honoree

HOUSTON, Texas, July 16, 2026 (SEND2PRESS NEWSWIRE) — NotaryCam®, a Stewart-owned company and a pioneering provider of remote online notarization (RON) and identity verification/authentication technology for real estate and legal transactions, today announced that President Brian Webster has been recognized as a 2026 Inman Best in Finance award winner. The award honors mortgage and finance professionals who have advanced innovation and raised industry standards for excellence. Webster is recognized for his enduring role in modernizing the mortgage process and normalizing remote online notarization as a trusted, compliant component of digital closings.

NotaryCam President Brian Webster
Image caption: NotaryCam President Brian Webster.

With more than 25 years of experience in mortgage and financial services, Webster has helped transform RON from an emerging concept into a mainstream element of the homebuying experience. He has guided the expansion of NotaryCam’s secure, compliant RON and identity verification solutions across newly approved states while deepening integrations with leading eClosing and document providers.

Prior to leading NotaryCam, his work at the Consumer Financial Protection Bureau, Wells Fargo and Freedom Mortgage contributed to early eMortgage initiatives that laid the groundwork for today’s paperless closing ecosystem. He has also played an active role in shaping industry standards through collaboration with regulatory and trade organizations.

“Being recognized by Inman alongside so many outstanding professionals in mortgage and finance is a tremendous honor,” said Webster. “This recognition reflects the work of the entire NotaryCam team and the partners who trust us to deliver a better closing experience. We remain committed to making remote online notarization more accessible, more secure and more seamless for everyone involved in a transaction.”

Explore the full list of 2026 Inman Best in Finance honorees at https://www.inman.com/best-of-finance-awards/.

About NotaryCam, a Stewart Company

NotaryCam, a Stewart-owned company, is the leader in online notarization and mortgage eClosing solutions, having notarized documents worldwide for more than two million customers across the United States and more than 146 countries. The company’s eClose360® platform delivers the “perfect” online mortgage closing in every jurisdiction where RON is allowed and supports all eClosing scenarios with a flexible workflow for document recording and unparalleled identity verification, security and customer convenience. In addition to real estate transactions, NotaryCam provides RON services to many Fortune 500 companies as well as small and midsize businesses. The company also proudly maintains an industry-leading 99.8 percent customer satisfaction rating and the highest Net Promoter Score (NPS) amongst the best global tech brands.

Visit https://www.notarycam.com for additional information or to get a document notarized today.

NEWS SOURCE: NotaryCam Inc.


This press release was issued on behalf of the news source (NotaryCam Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/notarycam-president-brian-webster-named-a-2026-inman-best-in-finance-honoree/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136869 NOREL-3B


LodeStar Integrates with Dark Matter Technologies’ Empower® LOS Platform

CONSHOHOCKEN, Pa., July 14, 2026 (SEND2PRESS NEWSWIRE) — LodeStar Software Solutions (LodeStar), the leading provider of mortgage closing cost and fee data, today announced that it is integrated with Dark Matter Technologies (Dark Matter®). LodeStar’s Closing Cost Calculator is now available in Empower® loan origination system (Empower), developed in conjunction with the Dark Matter Developer Platform.

LodeStar Integrates with Dark Matter Technologies' Empower LOS Platform
Image caption: LodeStar Integrates with Dark Matter Technologies’ Empower LOS Platform.

The Dark Matter Developer Platform enables third-party technology providers to connect their solutions to the Empower® ecosystem, expanding the capabilities available to lenders across the mortgage lifecycle. Through the Developer Platform, LodeStar will deliver fully integrated fee reliance and fee-related compliance tools to lenders using Dark Matter’s technology ecosystem.

Founded in 2013 and utilized by thousands of originators nationwide, LodeStar helps mortgage originators effectively manage their third-party closing costs to save both time and money as well as maintaining TRID (TILA-RESPA Integrated Disclosure Rule) compliance.

“LodeStar is proud to be the first integration partner to use the new Dark Matter Developer Platform,” said LodeStar CEO and Co-Founder, Jim Paolino. “Connectivity is one of our core values, and we’re excited to launch this new partnership.”

“At Dark Matter, we are focused on delivering intelligent, configurable technology that strengthens lenders across the mortgage lifecycle,” said Sean Dugan, CEO of Dark Matter Technologies. “By welcoming LodeStar to the Dark Matter Developer Platform, we’re expanding the range of capabilities available to lenders seeking to strengthen risk management and compliance across the loan origination process.”

For more information about LodeStar or Dark Matter Technologies, please visit their websites.

ABOUT LODESTAR SOFTWARE SOLUTIONS

Founded by Jim Paolino and David Spektor in 2013 in response to the complexities of closing cost disclosures, LodeStar is a privately held firm specializing exclusively in mortgage closing costs. From statewide transfer taxes to granular township-level fees, LodeStar ensures accurate, compliant fee disclosures for every loan, serving as a trusted partner in fee management. Driven by its core values of clarity, community and connectivity, the company helps mortgage lenders across the country drive down mortgage production costs through precise disclosures and reliable services. Learn more at https://www.lodestarss.com/.

ABOUT DARK MATTER TECHNOLOGIES

Operating with the nimble nature of a startup and the disciplined maturity of one of the industry’s leading providers, Dark Matter Technologies delivers powerful technology with unparalleled automation and relentless innovation to leading mortgage lenders, servicers and companies nationwide. For more information, visit https://www.dmatter.com.

X: @dmattertech #fintech #mortgage #HousingWire #HWAwards

NEWS SOURCE: LodeStar Software Solutions


This press release was issued on behalf of the news source (LodeStar Software Solutions), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/lodestar-integrates-with-dark-matter-technologies-empower-los-platform/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136793 NOREL-3B


Vice Capital Markets names Terry Aikin, CMB as executive vice president, strategic growth

NOVI, Mich., July 14, 2026 (SEND2PRESS NEWSWIRE) — Vice Capital Markets, a leading mortgage hedge advisory firm for independent lenders, banks and credit unions, today announced the appointment of Terry Aikin as executive vice president, strategic growth.

Vice Capital Markets names Terry Aikin, CMB as executive vice president, strategic growth
Image caption: Vice Capital Markets names Terry Aikin, CMB as executive vice president, strategic growth.

With more than three decades of experience across mortgage banking, risk management and capital markets, Aikin will focus on expanding Vice Capital’s customer base, strengthening existing client relationships and identifying new market opportunities.

“Vice Capital’s success has been built on a foundation of relationships, integrity and expertise,” said Chris Bennett, chairman at Vice Capital Markets. “Throughout his career, Terry has followed that same philosophy, and I can think of no better candidate to help us expand our offerings and enhance our ability to optimize lenders’ secondary market strategies and maximize their profitability.”

In his leadership roles at MGIC, Synergy Appraisal Services, Mortgage Cadence, Solidifi and United Guaranty Corporation, Aikin has helped financial institutions navigate market challenges while driving sustainable growth. A 15-year instructor in the Mortgage Bankers Association (MBA) School of Mortgage Banking, Aikin also holds the MBA’s Certified Mortgage Banker (CMB) designation and was a 2025 recipient of the association’s E. Michael Rosser Lifetime Achievement Award. Outside the industry, Aikin serves as founder and president of the Fuel The Drive Foundation, a nonprofit organization dedicated to providing golf and tennis opportunities for underserved youth.

“Over the past 25 years, Vice Capital Markets’ commitment to delivering personalized service and expert guidance has been the key to its clients’ long-term success,” Aikin said. “I look forward to helping more financial institutions realize the benefits of working with Vice Capital and cementing its position as the industry’s most reputable capital markets, hedging and mortgage banking advisory firm.”

About Vice Capital Markets

Since 2001, Vice Capital Markets has expertly navigated interest rate risk and driven profitability on over $1 trillion in MBS trades and mortgage-related transactions for a diverse range of financial institutions. Utilizing proprietary risk-management models and an advanced investor and agency platform, Vice Capital has enabled clients to enhance their secondary market strategies and achieve optimal sales gains.

The company’s Vice Execution Portal™ (ViceEx) is an all-inclusive, whole-loan trading platform that enables lenders and secondary market managers to seamlessly send and receive aggregator bulk bids, compare agency executions with customizable retained or co-issue servicing values while guaranteeing the best execution that might otherwise be missed in a manual process.

With traders averaging over a decade of experience, Vice Capital brings the expertise necessary to tackle market challenges and consistently deliver secure and effective profit growth for its clients. For further information, visit www.vicecapitalmarkets.com or call 248-869-8100.

NEWS SOURCE: Vice Capital Markets


This press release was issued on behalf of the news source (Vice Capital Markets), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vice-capital-markets-names-terry-aikin-cmb-as-executive-vice-president-strategic-growth/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136776 NOREL-3B


Class Valuation verified by Fannie Mae and Freddie Mac to support new Uniform Property Data Report specification

Leading appraisal management company verified to support next-generation property data report standard

TROY, Mich., July 9, 2026 (SEND2PRESS NEWSWIRE) — Class Valuation, a leading real estate appraisal management company (AMC), has been verified by Fannie Mae® and Freddie Mac (the government-sponsored enterprises, or GSEs) to support the Uniform Property Data Report (UPDR) specification under Uniform Property Dataset (UPD) Version 1.0. Use of the UPDR is mandatory for mortgages with applications received on or after June 30, 2026.

Class Valuation
Class Valuation logo.

The UPDR is a standardized report template introduced jointly by the GSEs as part of the Uniform Mortgage Data Program (UMDP) to bring greater efficiency and consistency to the underwriting and review process. The GSEs developed the report in direct response to industry feedback about the challenges of working with varying property data output formats. The standardized format is designed to streamline review processes, simplify training across the industry and enable automated data validation while delivering a cleaner, more consistent data delivery mechanism for underwriters and operations teams.

Class Valuation has provided property data collection services to clients delivering loans to the GSEs for more than 16 years. This verification reflects the company’s ongoing commitment to meeting evolving GSE requirements and positions its clients for a smooth transition to the new standardized report format.

“This verification reflects our team’s ongoing commitment to staying ahead of industry modernization rather than catching up to it,” said Chris Flynn, chief operating officer of Class Valuation. “As property data collection continues to evolve and UAD 3.6 approaches, the industry can count on Class Valuation to be ready with solutions that meet Fannie Mae and Freddie Mac’s new data standards and help clients move forward with confidence.”

ABOUT CLASS VALUATION:

Class Valuation is a leading nationwide appraisal management company (AMC) renowned for its commitment to fast turn times, exceptional quality and unparalleled client service. The company leverages a powerful combination of skilled professionals, innovative products, optimized processes and advanced technology to empower lenders in fulfilling homeownership dreams. Consistently recognized by top mortgage lenders for its outstanding performance, Class Valuation has also earned accolades as a top workplace and received numerous industry awards. Founded in 2009, Class Valuation is headquartered in Troy, Michigan. For more information, please visit https://www.classvaluation.com.

X: @ClassValuation #appraisal #valuation #lending

NEWS SOURCE: Class Valuation


This press release was issued on behalf of the news source (Class Valuation), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/class-valuation-verified-by-fannie-mae-and-freddie-mac-to-support-new-uniform-property-data-report-specification/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136728 NOREL-3B


Dovenmuehle’s Amber Cowan named a Mortgage Stars honoree by Mortgage Women Magazine

LAKE ZURICH, Ill., July 9, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (DMI), a leading mortgage subservicing company, announced today that Amber Cowan, first vice president of Default Operations, has been named a Mortgage Stars honoree by Mortgage Women Magazine. The program recognizes women making significant contributions to the mortgage industry through innovation, leadership and impact on colleagues and clients. Cowan is honored for modernizing default operations through data-driven innovation, her borrower-focused servicing strategies and her sustained commitment to building high-performing teams.

Dovenmuehle's Amber Cowan, 2026 Mortgage Star
Image caption: Dovenmuehle’s Amber Cowan, 2026 Mortgage Star.

Cowan oversees 600 employees across collections, foreclosure, loss mitigation, REO, bankruptcy and property preservation. Over the past year, she led the integration of default operations KPI and SLA ecosystems into dynamic dashboards, giving leadership and operational teams the ability to measure performance trends against benchmarks and drill down to loan-level detail. She further expanded performance analytics by introducing geographic, loan type and seasonality data into performance monitoring, fundamentally shifting how non-performing assets are governed throughout their lifecycle.

Through automation initiatives including bulk processing workflows for borrower assistance milestones, Cowan’s team achieved a significant reduction in review timelines and related expenses. She helped expand Dovenmuehle’s capabilities to service HELOC and junior lien portfolios and collaborated across departments to improve claim recoverability reporting and operational visibility. She also modernized the borrower experience by supporting expanded omni-channel engagement, mobile notary services and remote online notarization.

“I’m honored to be recognized for work that I believe is moving the industry forward,” said Cowan. “But I’m most proud of the team behind these results. Every efficiency gain, every performance milestone reflects the dedication of the people I get to work alongside every day. This recognition belongs to them as much as it does to me.”

Beyond operational results, Cowan is recognized for her commitment to developing people. She introduced staff training initiatives in multiple formats, including video, interactive manuals and outside vendor trainings, and meets regularly with indirect reports to discuss their goals and professional growth.

Explore the full list of honorees: https://nationalmortgageprofessional.com/news/written-stars-2026-mortgage-star-awards.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehles-amber-cowan-named-a-mortgage-stars-honoree-by-mortgage-women-magazine/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136702 NOREL-3B


Dovenmuehle’s Amber Cowan named a Mortgage Stars honoree by Mortgage Women Magazine

LAKE ZURICH, Ill., July 9, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (DMI), a leading mortgage subservicing company, announced today that Amber Cowan, first vice president of Default Operations, has been named a Mortgage Stars honoree by Mortgage Women Magazine. The program recognizes women making significant contributions to the mortgage industry through innovation, leadership and impact on colleagues and clients. Cowan is honored for modernizing default operations through data-driven innovation, her borrower-focused servicing strategies and her sustained commitment to building high-performing teams.

Dovenmuehle's Amber Cowan, 2026 Mortgage Star
Image caption: Dovenmuehle’s Amber Cowan, 2026 Mortgage Star.

Cowan oversees 600 employees across collections, foreclosure, loss mitigation, REO, bankruptcy and property preservation. Over the past year, she led the integration of default operations KPI and SLA ecosystems into dynamic dashboards, giving leadership and operational teams the ability to measure performance trends against benchmarks and drill down to loan-level detail. She further expanded performance analytics by introducing geographic, loan type and seasonality data into performance monitoring, fundamentally shifting how non-performing assets are governed throughout their lifecycle.

Through automation initiatives including bulk processing workflows for borrower assistance milestones, Cowan’s team achieved a significant reduction in review timelines and related expenses. She helped expand Dovenmuehle’s capabilities to service HELOC and junior lien portfolios and collaborated across departments to improve claim recoverability reporting and operational visibility. She also modernized the borrower experience by supporting expanded omni-channel engagement, mobile notary services and remote online notarization.

“I’m honored to be recognized for work that I believe is moving the industry forward,” said Cowan. “But I’m most proud of the team behind these results. Every efficiency gain, every performance milestone reflects the dedication of the people I get to work alongside every day. This recognition belongs to them as much as it does to me.”

Beyond operational results, Cowan is recognized for her commitment to developing people. She introduced staff training initiatives in multiple formats, including video, interactive manuals and outside vendor trainings, and meets regularly with indirect reports to discuss their goals and professional growth.

Explore the full list of honorees: https://nationalmortgageprofessional.com/news/written-stars-2026-mortgage-star-awards.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehles-amber-cowan-named-a-mortgage-stars-honoree-by-mortgage-women-magazine/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136702 NOREL-3B


Optimal Blue report: Mortgage demand strengthens as purchase activity and pull-through rebound

Purchase locks reached their highest level since early spring as pull-through rates rebounded and non-conforming lending climbed to a multi-year high

PLANO, Texas, July 9, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its June 2026 Market Advantage mortgage data report, which found that mortgage activity strengthened month over month (MoM), with purchase lock volume climbing to its highest level since early spring and pull-through rates rebounding across both purchase and refinance pipelines. Total rate-lock volume rose 10% MoM and 15% year over year (YoY). June also extended recent shifts in product mix, with non-conforming lending reaching its highest share in several years as conforming volume remained below 49% for the second consecutive month.

Optimal Blue's June 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s June 2026 Market Advantage mortgage data report.

Mortgage rates were mixed in June. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, edged up 1 basis point (bp) MoM to 6.45%, remaining 22 bps lower than June 2025. The 10-year Treasury yield closed the month at 4.44%, down 1 bp MoM, while the spread between the 10-year Treasury and the OBMMI 30-year conforming rate widened to 201 bps.

“June wasn’t defined by a single headline number. Purchase demand strengthened, refinance activity held up and pull-through improved after softening in May,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Together, those trends point to a market that is battle tested and that has adapted to a higher-for-longer rate environment.”

On the secondary side, lenders continued to balance execution options as agency mortgage-backed security (MBS) executions declined for the second consecutive month to 40% of funded loan sales, while best-efforts activity increased to 3%. Execution spreads also moved in different directions, with conventional 30-year best-efforts-to-mandatory spreads tightening to 31 bps and government 30-year spreads widening to 18 bps. Mortgage servicing rights (MSRs) for conforming 30-year loans declined to 1.33% in June.

“We saw lenders continue to fine-tune execution strategy in June,” Vough said. “Agency MBS executions declined again while best-efforts activity increased showing that lenders are evaluating all potential loan sale options, and best efforts-mandatory pricing spreads moved in opposite directions for conventional and government loans. It shows lenders must continue to evaluate execution opportunities on a product-by-product basis.”

KEY FINDINGS FROM THE MARKET ADVANTAGE REPORT, DERIVED FROM DIRECT-SOURCE MORTGAGE LOCK AND SECONDARY MARKET DATA, INCLUDE:

Volume trends and market composition

  • Refis hold steady: Refinance share remained essentially unchanged at 19% of total lock volume in June, materially higher than levels seen throughout much of 2025. Cash-out refinance volume grew 11% MoM and 10% YoY. Rate-and-term refinance volume increased 6% MoM and 32% YoY.
  • Purchase momentum builds: Purchase lock volume increased 10% MoM and 14% YoY, reaching its highest level since early spring. Purchase loans accounted for more than 81% of total lock volume in June.
  • Conforming stays below 49%: Conforming share declined to 49% of total production in June, extending the decline that first pushed it below 50% in April. Non-conforming lending expanded to more than 19% of volume, its highest share in several years. FHA represented nearly 19% of production, while VA loans accounted for almost 13%.
  • Non-QM remains elevated: Non-qualified mortgage loans accounted for 9% of total lock volume in June, 1.4 percentage points higher than a year ago.
  • New construction strengthens: Planned unit developments (PUDs), a proxy for new construction activity, increased to 28% of total volume. Single-family detached homes remained the dominant property type at 64% of production. Condo share held at 6%.

Rates and pricing

  • Mortgage spread tops 200 bps: The OBMMI 30-year conforming fixed rate increased 1 bp MoM to 6.45%, down 22 bps YoY. The 10-year Treasury yield closed at 4.44%, down 1 bp MoM. The spread between the 10-year Treasury and the OBMMI 30-year conforming rate widened to 201 bps, remaining above long-term averages despite narrowing from year-ago levels.
  • MSRs edge lower: MSRs for conforming 30-year loans declined 3 bps to 1.33%, representing a 5.32 multiple.
  • Conventional and government spreads split: Best-efforts-to-mandatory spreads for conventional 30-year products tightened 9 bps to 31 bps. Government 30-year spreads widened 6 bps to 18 bps.
  • Top-tier executions increase: The share of loans sold at the highest price tier increased 78 bps to 78%. Loans sold at the second- and third-ranked price tiers each declined 93 bps and 25 bps to 12% and 3%, respectively. Fourth-tier-or-lower executions increased 40 bps to 7%.

Channel and execution

  • Agency MBS executions decline for second consecutive month: Hedged loan sales to agency MBS declined 1 percentage point to 40% of funded loan sales.
  • Best-efforts activity picks up: Cash and bulk aggregator executions held flat while best-efforts executions increased from 2% to 3% of funded loan sales.
  • Investor count plateaus: Investor participation held at 14 for the second consecutive month after reaching 15 in April.

Product mix and borrower profiles                          

  • First-time buyers regain ground: First-time homebuyers accounted for 45% of conforming purchase locks in June, nearly 3 percentage points above year-ago levels. FHA first-time homebuyer share remained elevated at 69%.
  • DTI ratios remain below year-ago levels: Purchase debt-to-income ratios held below 2025 levels across all major products: conforming borrowers at 36.6%, FHA at 43.5% and VA at 43.0%, suggesting affordability has modestly improved relative to last year despite higher home prices.
  • Borrower credit quality holds steady: The average credit score held at 731, ranging from 757 in the San Francisco Bay Area to 716 in San Antonio. Conforming borrowers averaged a score of 753.
  • Pull-through stays strong: Purchase pull-through increased to 81.4% in June, recovering from May’s decline. Refinance pull-through also climbed to 71.1%.
  • Loan amounts near $400K again: The average locked loan amount increased to just over $399,000 in June, near record highs as home prices continue to appreciate and purchase activity remains concentrated in higher-cost markets. Average loan-to-value (LTV) ratios nationwide were 81.4%, ranging from 71.0% in the greater Los Angeles area to 88.8% in San Antonio.

To view the full June 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Alexandra Kreuter to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

IMAGE link for media: https://www.Send2Press.com/300dpi/26-0709-s2popbluchart-300dpi.webp

Image caption: Optimal Blue’s June 2026 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-mortgage-demand-strengthens-as-purchase-activity-and-pull-through-rebound/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136714 NOREL-3B


The Mortgage Collaborative launches TMC Healthcare Cooperative to give lender members and preferred partners control over rising healthcare costs

SAN DIEGO, Calif., July 1, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s largest independent cooperative network for mortgage lenders, has launched the TMC Healthcare Cooperative, a self-funded medical program open to all TMC lender members and preferred partners. Developed in partnership with CCIG, a Colorado-based employee benefits firm, the program gives vendors, community banks, credit unions and independent mortgage bankers a way to fund their own health claims as a group, share risk through a captive structure and access institutional-grade stop-loss coverage, replacing the fully insured carrier model where rate increases arrive at renewal with no explanation and no recourse.

TMC - The Mortgage Collaborative
Image caption: TMC – The Mortgage Collaborative.

“Mortgage lenders have for too long been paying into a system that offers nothing in return when claims run well,” said Jodi Hall, president and CEO of The Mortgage Collaborative. “For an IMB without the scale of a large institution, for example, that means absorbing rate increases year after year with no transparency into what’s driving costs and no path to a better outcome. The TMC Healthcare Cooperative changes that equation for our entire network, giving members and partners the purchasing power, the claims visibility and the risk-sharing structure that large employers take for granted, delivered through the trust and community TMC has already built.”

In a fully insured plan, premiums go to a national carrier regardless of healthcare usage. The TMC Healthcare Cooperative replaces this with a group captive model: participants pool risk and fund their claims, so money stays within the group. A captive layer spreads risk; a tough claims year for one participant doesn’t necessarily raise that participant’s renewal cost. Stop-loss coverage caps big claims, protecting members from high costs. Surpluses from better-than-expected claims are returned to participants rather than retained by an insurance carrier.

For depository institutions like community banks and credit unions, the program covers all employees, not just mortgage staff. It pairs this with plan partners for administration, pharmacy and stop-loss coverage, selected through evaluation. A committee of TMC lender members vetted these partners to ensure the program matches industry-specific costs, workforce traits and business cycles. Participants see their claims data, control plan design and share best practices with peers.

The TMC Healthcare Cooperative is for organizations with 51+ employees; smaller options are upcoming. Members should start 180 days before renewal with a short interest form, then a 30-minute intro. Interested parties share census and claims data for cost comparison. Participation is exclusive to the TMC community.

Lender members and preferred partners can complete the interest form at https://benefits.thinkccig.com/ or contact their TMC member benefits advocate. Organizations interested in joining TMC may contact referrals@mtgcoop.com.

About The Mortgage Collaborative

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders across the United States through networking, education and advocacy. TMC fosters an environment of collaboration and innovation, ensuring its members succeed regardless of market conditions. For more information, visit https://mortgagecollaborative.com/.

About CCIG

Founded in Greenwood Village, Colo., in 1985, CCIG has won repeated recognition as one of the nation’s leading independent insurance brokers, offering personal and commercial property and casualty insurance, as well as risk engineering services and health benefit plans for employers.

CCIG’s 80 personal and business insurance professionals take pride in designing custom-tailored solutions to protect our clients’ property, valuables and all of their exposures to risk. CCIG’s Private Client Services group concentrates exclusively on the specialized needs of individuals and families with substantial assets.

LOGO link for media: https://mortgagecollaborative.com/wp-content/uploads/2025/12/Color-Logo-The-Mortgage-Collaborative-scaled-1.png

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/the-mortgage-collaborative-launches-tmc-healthcare-cooperative-to-give-lender-members-and-preferred-partners-control-over-rising-healthcare-costs/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136595 NOREL-3B


LodeStar report shows nominal year-over-year decline in national average mortgage closing costs

Decrease closely correlates with national home price trends, illustrating how closing costs impact housing affordability

CONSHOHOCKEN, Pa., June 30, 2026 (SEND2PRESS NEWSWIRE) — LodeStar Software Solutions (LodeStar), the leading provider of mortgage closing cost and fee data, today announced the release of its Year-Over-Year Mortgage Closing Cost Report covering 2024 versus 2025. The report analyzes distinct mortgage quotes across all 50 states and the District of Columbia (D.C.), drawn from the company’s closing cost calculator platform. Nationally, purchase loan closing costs declined by 2.9%, driven largely by falling home prices, which reduced transfer tax burdens across many markets. In total, 28 states saw closing costs decrease, while 23 states experienced increases.

LodeStar Software Solutions
Image caption: LodeStar Software Solutions.

The most dramatic single-market shift occurred in D.C., where closing costs dropped 21.1%. Because D.C. has one of the highest transfer tax rates in the country, the significant decrease in the average purchase price here had a compounding effect on closing costs, though the area still has the highest dollar-value closing costs nationally. Conversely, home prices in Delaware rose modestly, pushing closing costs up by 4.5%, keeping it the most expensive state as a percentage of sale price at 3.06%.

Other key findings from LodeStar’s 2024 v. 2025: Year-Over-Year Mortgage Closing Cost Report include:

  • An 7.8% surge in refinance volume, with refi closing costs averaging less than half of purchase closing costs;
  • Higher-than-average refinance closing costs for New York and Florida borrowers, driven by taxes structured around the loan or note amount, rather than a property transfer, which then applies to both purchase and refinance transactions; and
  • A growing trend of recording fees being redirected to fund non-real-estate programs, such as affordable housing and homelessness services, with little to no borrower visibility.

“The connection between closing costs and housing affordability is often overshadowed by other components to the equation, like interest rates and down payments,” said Ron Carvalho, director of data operations at LodeStar. “However, our data shows that decisions made at the state level on recording taxes and document fees have a direct impact on borrowers’ total financial ability to purchase or refinance their home. Knowing what’s happening with these costs helps lenders provide accurate guidance to their borrowers in their homeownership journey.”

Methodology

LodeStar’s dataset is drawn from the company’s closing cost calculator platform, which serves mortgage lenders across the United States. Each record represents a distinct quote (not a funded loan), identified by a unique search ID. Where lenders run multiple quotes for the same loan, only distinct transactions are counted.

Closing costs are reported both inclusive and exclusive of recording fees and transfer taxes, as these components are highly jurisdiction-specific and can create misleading cross-state comparisons when included without context. The report presents averages by state; individual market results may vary based on loan amount, property value, transaction type and title provider selection.

Average figures in this report represent the average of state-level averages and should be interpreted as a benchmark rather than a population-weighted national mean.

View the full report: https://www.lodestarss.com/2026/06/30/2024-vs-2025-year-over-year-mortgage-closing-cost-report/.

About LodeStar Software Solutions

Founded by Jim Paolino and David Spektor in 2013 in response to the complexities of closing cost disclosures, LodeStar is a privately held firm specializing exclusively in mortgage closing costs. From statewide transfer taxes to granular township-level fees, LodeStar ensures accurate, compliant fee disclosures for every loan, serving as a trusted partner in fee management. Driven by its core values of clarity, community and connectivity, the company helps mortgage lenders across the country drive down mortgage production costs through precise disclosures and reliable services. Learn more at https://www.lodestarss.com/.

NEWS SOURCE: LodeStar Software Solutions


This press release was issued on behalf of the news source (LodeStar Software Solutions), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/lodestar-report-shows-nominal-year-over-year-decline-in-national-average-mortgage-closing-costs/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136572 NOREL-3B


Dovenmuehle names Ann Morey its head of product

LAKE ZURICH, Ill., June 30, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (DMI), a leading mortgage subservicing company, announced today that Ann Morey has been named Head of Product. In this role, Morey will lead DMI’s product management function, which includes establishing strategic product vision, driving outcome-oriented roadmaps that address stakeholder expectations, increasing internal cross-functional alignment and building agile, high-performing teams.

Ann Morey of Dovenmuehle
Image caption: Ann Morey of Dovenmuehle.

Morey brings more than 15 years of experience leading digital product and technology teams across financial services, logistics and government sectors. She most recently served as vice president of product delivery at Tria (formerly Softrams), managing a team of more than 200, $70 million in annual revenue and profit-and-loss responsibility for three large-scale enterprise software contracts. Before that, she was a director of product for cloud platforms with the U.S. Air Force (Kessel Run) and previously served in product management roles at XPO Logistics and First Data.

“Ann brings exactly the kind of product leadership we need as we continue to evolve our platform and capabilities,” said Senior Vice President Matt Budy. “Her track record of cultivating high-performing teams, driving measurable outcomes and translating complex client needs into effective technology solutions makes her exceptionally well-suited to lead this function at Dovenmuehle.”

Known for bringing discipline to product processes, Morey has introduced rigorous discovery and prioritization frameworks throughout her career. As a talent developer, she significantly reduced employee turnover and launched a high-value mentorship program at a previous employer. She holds an MBA in management from Boston University.

“I’ve spent my career at the intersection of complex operations and digital products, and Dovenmuehle sits squarely in that space,” said Morey. “The company has built an impressive legacy, and I’m looking forward to building on that foundation with modern product practices alongside a team focused on continuous improvement and client value.”

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehle-names-ann-morey-its-head-of-product/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136566 NOREL-3B


Friday Harbor and NewFed Mortgage honored with PROGRESS in Lending’s 2026 Connections Award

Award recognizes collaboration that cut cycle times, boosted capacity and drove $170 million in additional volume

SEATTLE, Wash., June 29, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, has been named a recipient of PROGRESS in Lending’s 2026 Connections Award alongside NewFed Mortgage Corp. (NewFed), a full-service residential mortgage lender operating in more than 20 states. The recognition honors a partnership that allowed NewFed to grow production without the hiring cycles and overhead that typically accompany scale.

NewFed Mortgage leverages Friday Harbor to boost fulfillment productivity by 35%
Image caption: Friday Harbor and NewFed Mortgage honored with PROGRESS in Lending’s 2026 Connections Award.

NewFed rolled out Friday Harbor across its origination and fulfillment teams with a straightforward premise: catch problems before they reach an underwriter. The platform evaluates loan files against automated underwriting system (AUS) findings, investor guidelines and NewFed’s own credit overlays early in the process, so processors and loan officers can resolve issues while borrowers are still engaged.

The results have been significant. Since implementing Friday Harbor, NewFed processors have increased monthly file capacity by 36%, while underwriters review 35% more loans. Application-to-funded cycle times have dropped from 32 days to 26 days, and NewFed funded approximately $170 million more in loans during 2025 than the prior year without adding a single fulfillment hire.

“NewFed came to us with a clear-eyed goal: grow production without the headcount increases that erode margin,” said Theo Ellis, CEO of Friday Harbor. “What made this partnership work was their willingness to give us a real look at how their operation actually runs: the workflows, the friction points, the edge cases. The results speak to what’s possible when a technology partner understands your operation from the inside out.”

Now in its third year, the Connections Award honors partnerships and integrations that are advancing mortgage lending through collaboration, innovation and measurable business results. The collaboration extended well beyond a typical lender-vendor relationship. NewFed joined Friday Harbor as an early design partner, contributing feedback on real production workflows and loan scenarios that directly shaped the platform’s development.

For a full list of 2026 Connections Award winners, visit https://mymortgagemindset.com/

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbor-and-newfed-mortgage-honored-with-progress-in-lendings-2026-connections-award/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136555 NOREL-3B


DocMagic and Truliant Federal Credit Union earn PROGRESS in Lending’s 2026 Connections Award for industry-first eHELOC milestone

Recognition marks the latest chapter in a yearslong collaboration that has produced three landmark milestones in digital mortgage lending

TORRANCE, Calif., June 29, 2026 (SEND2PRESS NEWSWIRE) — DocMagic® was honored today with PROGRESS in Lending’s 2026 Connections Award alongside Truliant Federal Credit Union, a North Carolina-based credit union serving more than 300,000 members. The recognition honors a yearslong partnership that culminated in the mortgage industry’s first electronic home equity line of credit (eHELOC) registered with the MERS® eRegistry.

DocMagic, Inc.
Image caption: DocMagic, Inc.

Since 2020, Truliant and DocMagic have worked together to build the credit union’s digital closing capabilities from the ground up. In June 2025, that partnership extended into home equity lending, where DocMagic’s SmartSAFE™ eVault made the eHELOC registration possible.

The eHELOC milestone is the third time the two organizations have broken new ground together. In March 2020, DocMagic helped Truliant become the first credit union in North Carolina to complete a full eClosing. A year later, working with DocMagic, Truliant became the first credit union to transfer an eNote to the Federal Home Loan Bank of Atlanta and just the second in the entire 11-member FHLBank system to do so, opening a wider path for member financial institutions to pledge eNotes. In the months that followed, the shift to eNotes cut six to eight days from Truliant’s loan delivery timeline.

“Truliant has been a tremendous partner in advancing digital lending across the credit union space,” said Pat Theodora, CEO of DocMagic. “Every milestone we’ve reached together over the years has been built on a shared belief that the next frontier is always worth pursuing.”

“DocMagic has helped us move lending forward with greater speed, efficiency and ease for consumers,” said Beth Eller, senior vice president of mortgage lending at Truliant. “Their innovative, forward-thinking approach has been instrumental to our progress, and we’re honored to celebrate this achievement together.”

Now in its third year, the Connections Award honors partnerships and integrations that are advancing mortgage lending through collaboration, innovation and measurable business results. For a full list of 2026 winners, visit https://mymortgagemindset.com/.

About DocMagic:

DocMagic® provides a complete digital mortgage platform for the mortgage industry, delivering proprietary document generation, automated compliance, eSignature, eClosing, eNotarization, eNote and eVault technology in one unified solution. Built on nearly 40 years of innovation, DocMagic helps lenders, settlement service providers and investors move loans from application through post-closing with greater speed, accuracy and confidence. AI deepens that foundation through the company’s Intelligent Agentic Network. For more information, visit www.docmagic.com.

About Truliant Federal Credit Union:

Truliant is a mission-driven, not-for-profit financial institution based in Winston-Salem, N.C. It improves lives by providing great service and straightforward financial solutions. Truliant was chartered in 1952 and serves 333,000+ members. A top 100 U.S. credit union, Truliant has more than 35 branches in North Carolina, South Carolina, and Virginia. For more information, visit www.truliant.org.

Logo link for media:
https://www.docmagic.com/sites/default/files/img/logo/docmagic-logo-reg.png

* * *
UPDATED: 1:40 p.m. PDT to fix an inadvertent error in the text as originally provided.

NEWS SOURCE: DocMagic, Inc.


This press release was issued on behalf of the news source (DocMagic, Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/docmagic-and-truliant-federal-credit-union-earn-progress-in-lendings-2026-connections-award-for-industry-first-eheloc-milestone/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136549 NOREL-3B


Click n’ Close names Merv Govender chief information officer

ADDISON, Texas, June 25, 2026 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, today announced the appointment of Merv Govender as chief information officer (CIO). Govender brings more than 27 years of technology leadership across the banking, gaming and healthcare industries. As CIO, he will lead Click n’ Close’s technology development and deployment strategy, with a focus on building and deploying tools that support the company’s lending operations and third-party origination channels. Govender will also oversee cybersecurity, infrastructure and the company’s adoption of artificial intelligence (AI) across its lending operations.

Click n’ Close names Merv Govender chief information officer
Image caption: Click n’ Close names Merv Govender chief information officer.

“Click n’ Close has always viewed technology not just as a competitive advantage but as an operational imperative, and our entrepreneurial mindset means we’re willing to look outside this industry for the talent and ideas that push us forward,” said Ian Kimball, president of Click n’ Close. “We’ve found that leaders who have seen what technology can accomplish in other high-stakes, compliance-driven environments bring a perspective this industry needs. That is precisely where Merv has spent his career, which is why we’re confident his background will directly inform how we build and deploy technology going forward.”

Govender has previously led large-scale technology transformations in industries defined by strict regulatory requirements and complex operational demands. His career spans senior technology leadership roles in banking, gaming and healthcare, where he has focused on aligning technology investment with business strategy, modernizing infrastructure and strengthening cybersecurity programs. More recently, his work has expanded to include helping organizations operationalize AI as a practical tool for efficiency, decision-making and growth, an emphasis he will bring to Click n’ Close’s lending operations.

“Having spent my career in highly regulated industries, I understand the stakes involved in getting technology right, and mortgage is no different,” Govender said. “My focus will be on building the kind of infrastructure and AI capabilities that benefit not just Click n’ Close but also its partners and, ultimately, borrowers.”

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1959, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at clicknclose.com.

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-names-merv-govender-chief-information-officer/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136475 NOREL-3B


iEmergent supports launch of CONVERGENCE Knowledge Hub with Market Profile Dashboard

Longtime CONVERGENCE partner powers interactive resource that helps communities identify opportunities to expand homeownership

DES MOINES, Iowa, June 25, 2026 (SEND2PRESS NEWSWIRE) — iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced its support of the newly launched CONVERGENCE® Knowledge Hub, a centralized resource designed to help lenders, nonprofit organizations, housing counselors, real estate professionals and community leaders expand access to sustainable homeownership.

iEMERGENT
Image caption: iEmergent.

Unveiled earlier this month by the Mortgage Bankers Association (MBA) and the CONVERGENCE Collaborative, the Knowledge Hub brings together field-tested solutions, case studies, practical tools and research developed through years of collaboration among housing stakeholders working to address barriers to homeownership and housing affordability.

As part of the platform, iEmergent powers the Market Profile Dashboard, an interactive resource that allows users to explore local demographics, homeownership patterns, affordability challenges, mortgage credit access and housing supply trends across hundreds of U.S. markets. The dashboard helps communities identify homeownership gaps, understand local market dynamics and develop strategies tailored to the needs of their residents.

“The launch of the Knowledge Hub is exciting because it takes lessons that have emerged from years of collaboration in communities across the country and makes them accessible to a much broader audience,” said Laird Nossuli, CEO of iEmergent. “At its core, CONVERGENCE is about helping communities understand their local housing challenges, learn from what has worked elsewhere and build solutions that reflect their own needs. The Knowledge Hub brings those elements together in one place, combining practical resources, real-world examples and local market insights that can help stakeholders move from discussion to action.”

“iEmergent has been a cornerstone of CONVERGENCE’s ability to translate data into action at the local level,” said Wendy Penn, vice president of affordable housing initiatives at the Mortgage Bankers Association. “Too often, communities have the motivation to expand homeownership but struggle to make the case for where to focus and why. The Market Profile Dashboard changes that, giving local leaders the evidence they need to align partners, prioritize resources and build strategies with real staying power.”

CONVERGENCE is an initiative launched in 2019 by the Mortgage Bankers Association to expand homeownership through innovative community partnerships. CONVERGENCE addresses the information, trust, resource and market gaps that create barriers to homeownership. CONVERGENCE operates place-based initiatives in Memphis, Tennessee, Columbus, Ohio, Philadelphia and Baltimore. In each city, a mission-aligned local nonprofit organization serves as the lead partner, playing a central role in fostering collaboration among stakeholders across the housing ecosystem.

iEmergent’s contribution to the Knowledge Hub builds on years of involvement with CONVERGENCE initiatives nationwide. Nossuli currently serves as a national partner to CONVERGENCE and co-leads the Research and Evaluation workstream for both CONVERGENCE Philadelphia and Columbus. Beyond providing technology and market intelligence, iEmergent works alongside lenders, nonprofit organizations and municipal leaders to develop data-informed strategies, measure outcomes and expand access to sustainable homeownership.

Explore the CONVERGENCE Knowledge Hub at https://convergenceknowledgehub.org/.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com.

Tags: @iEmergent

Media Kit (PDF):
https://www.iemergent.com/docs/default-source/default-document-library/presskit_digitallinked.pdf

NEWS SOURCE: iEmergent


This press release was issued on behalf of the news source (iEmergent), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/iemergent-supports-launch-of-convergence-knowledge-hub-with-market-profile-dashboard/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136446 NOREL-3B


Dovenmuehle launches Diagnostic Process to streamline mortgage subservicing onboarding

LAKE ZURICH, Ill., June 23, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (DMI), a leading mortgage subservicing company, announced today that it is improving onboarding with its new Diagnostic Process. This approach helps DMI subservicing clients identify and evaluate organizational complexity, resource constraints and team readiness earlier in servicing transfer workflows. Early preparation using the Diagnostic Process improves servicing transfer outcomes and increases onboarding efficiency.

Dovenmuehle Mortgage
Image caption: Dovenmuehle Mortgage, Inc.

Traditional onboarding focuses on gathering technical data about loan portfolios and current operations, often leaving critical context undiscovered until it creates friction mid-implementation. Common examples include concurrent operational initiatives that can sap resources, inconsistent internal terminology that creates confusion, and loan portfolios in flux at the time of conversion.

The Diagnostic Process addresses these challenges through a three-part approach. First, a structured survey uncovers valuable insights into loan portfolio complexity, organizational structure, resource allocation, current technology use and operational pace. Next, the results are evaluated by experienced onboarding and technology specialists. Finally, the findings are used to tailor implementation workflows to address each lender’s priorities and areas of risk.

“The initial steps of onboarding are an opportunity to prime teams with deeper clarity before jumping into implementation,” said Head of Innovation Culture Jonas Brickus, who led development of the Diagnostic Process. “The survey questions are designed to characterize the client and the conditions they are in at the moment of transfer. That allows us to address concerns up front, surface hidden complexity and eliminate delays and rework down the line.”

Developed in collaboration with clients who had recently completed servicing transfers, the Diagnostic Process reflects factors identified as most consequential to onboarding outcomes. DMI clients report that completing the diagnostic early helps establish more realistic timelines and increased internal alignment. DMI will continue refining the Diagnostic Process based on client input and implementation experience.

“Better preparation at the start of a servicing relationship changes what the rest of onboarding looks like,” said Senior Vice President Matt Budy. “The Diagnostic Process reflects a straightforward idea: that asking the right questions early, and acting on the answers, leads to better outcomes for lenders and their borrowers.”

Learn more about DMI’s onboarding process and servicing support for commercial banks, credit unions, IMBs, MSR investors and housing finance agencies: https://www.dovenmuehle.com/.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehle-launches-diagnostic-process-to-streamline-mortgage-subservicing-onboarding/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136361 NOREL-3B


Friday Harbor expands AI pre-underwriting to condo and manufactured home loans

Expansion helps lenders navigate two of mortgage lending's most documentation-intensive property categories

SEATTLE, Wash., June 16, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, today announced new capabilities for condominium and manufactured home loans that enable lenders to evaluate property-specific eligibility requirements before files reach underwriting.

Friday Harbor logo
Image caption: Friday Harbor logo.

Condo and manufactured home loans, which together account for nearly 8% of mortgage originations, present unique eligibility requirements that often fall outside the standard mortgage workflow. As a result, lenders frequently rely on specialized reviews that can add time and complexity to the origination process.

Condo reviews can require lenders to evaluate project questionnaires, budgets, insurance coverage, reserve funding and other project-level documentation. Manufactured home loans often involve additional eligibility requirements related to titling, foundation standards and property classification. Both scenarios introduce complexity that can increase review times and create additional work for production and underwriting teams.

Friday Harbor evaluates property-related documentation alongside borrower information as part of its AI pre-underwriting process. Rather than reviewing individual documents in isolation, the platform analyzes information across the loan file and compares it against investor eligibility requirements to identify property-related issues, documentation gaps and potential eligibility concerns.

“Condo and manufactured home loans are a great example of why AI pre-underwriting needs to understand the entire loan file, not just a handful of documents,” said Theo Ellis, founder and CEO of Friday Harbor. “A borrower can be perfectly qualified and still run into property eligibility issues. Friday Harbor helps lenders identify those issues before they slow down the transaction.”

Lenders can learn more about Friday Harbor or request a demo at https://fridayharbor.ai.

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbor-expands-ai-pre-underwriting-to-condo-and-manufactured-home-loans/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136279 NOREL-3B


Informative Research receives MortgagePoint Tech Excellence Award for unified credit and verification platform

GARDEN GROVE, Calif., June 16, 2026 (SEND2PRESS NEWSWIRE) — Informative Research (IR), a leading technology provider of data-driven credit and verification solutions for the lending industry, today announced it has been named a recipient of the MortgagePoint Excellence Award for Top Technology Providers. The recognition highlights IR’s innovative, unified platform, which enables lenders to operate more efficiently and make confident, data-driven decisions across the loan origination process.

Informative Research receives 2026 MortgagePoint Tech Excellence Award
Image caption: Informative Research receives 2026 MortgagePoint Tech Excellence Award.

IR brings credit, verification and borrower data solutions together in a single, cohesive platform. By simplifying the tech stack and streamlining key workflows, IR helps clients manage costs, improve pull-through and enhance performance at every stage of origination. Integrations with leading loan origination systems and top data providers eliminate friction across credit, income and asset verification processes.

IR offerings include:

  • The Credit Platform: powers a full suite of solutions including soft pulls, hard pulls, tri-merge, FICO 10T, VantageScore 4.0, Mortgage Refresh, Account Refresh and simulators.
  • SoftQual™: enables prequalification without impacting borrower credit scores, while automated data transfers into loan origination systems reduce manual work and improve accuracy.
  • The Verification Platform: delivers a customizable waterfall across instant databases, payroll providers and manual verification, integrating with The Work Number®, Experian Verify, AccountChek®, and more.
  • Action Center: a self-service portal enabling loan officers and processors to make changes, request supplements and letters of explanation, and resolve issues directly from the credit report.

A robust data and analytics layer supports multiple IR solutions with dashboards, audit trails, reporting and platform reliability. Over the past year, IR expanded its technology footprint with five new integrations, including a partnership with Halcyon to automate income validation and add IRS tax transcript access, expanded verification options with Thomas & Company, and the introduction of The Work Number Report Indicator from Equifax to provide earlier insight into borrower employment status.

“This recognition reflects the work our team puts into solving real problems for lenders every day,” said CEO Matt Orlando. “Our platform was built to cut through the complexity of the origination process. When lenders can better manage credit and verification costs, improve pull-through and lower repurchase risk using a single, connected platform, we know we’re succeeding. We’re proud to be named among the top technology providers in the industry and remain committed to raising that bar.”

Explore the full list of MortgagePoint Excellence Award recipients: https://themortgagepoint.com/2026/06/15/meet-this-years-mortgagepoint-tech-excellence-award-recipients/.

About Informative Research

Informative Research, a Stewart company, is a premier technology provider delivering data-driven credit and verification solutions to the lending community. The solutions provider currently serves mortgage companies, banks and lenders throughout the United States. The company is recognized for streamlining the loan process with its straightforward service model, progressive solutions and cutting-edge technology. To learn more, visit https://www.informativeresearch.com.

NEWS SOURCE: Informative Research


This press release was issued on behalf of the news source (Informative Research), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/informative-research-receives-mortgagepoint-tech-excellence-award-for-unified-credit-and-verification-platform/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136273 NOREL-3B


DocMagic named 2026 MortgagePoint Tech Excellence Award recipient for digital mortgage innovation

TORRANCE, Calif., June 16, 2026 (SEND2PRESS NEWSWIRE) — DocMagic® announced today it has again been named a recipient of the MortgagePoint Tech Excellence Award. The annual award recognizes the most innovative technology providers in the mortgage industry. According to MortgagePoint, the Tech Excellence Award “highlights companies that deliver cutting-edge solutions, improve operational efficiency and enhance the mortgage process through technology.”

DocMagic, Inc.
Image caption: DocMagic, Inc.

MortgagePoint selected DocMagic as a winner for the second consecutive year based on its continued innovation and measurable impact across the digital mortgage lifecycle. Over nearly four decades, the company has evolved from a provider of document generation into a fully connected platform that supports document prep, compliance, eSignature, closing and eVaulting in a single environment.

Despite a challenging market, DocMagic’s digital closing platform continued to grow in 2025. eClosings increased nearly 31% year over year, with eNote activity growing even faster. Since 2022, the company has supported hundreds of thousands of eClosings and now accounts for nearly 12% of all industry eNote registrations.

“We’re proud to be recognized again by MortgagePoint,” said Lori Johnson, COO of DocMagic. “What matters most to us is helping our clients operate with more certainty and less friction. That means giving them tools that make closings faster, compliance easier and operations more efficient. It’s what we’ve been doing for almost 40 years.”

DocMagic continues to develop proprietary innovations. The company recently secured two U.S. patents related to electronic loan document technology and enabled the industry’s first electronic home equity line of credit registration with the MERS® eRegistry. Most recently, its SmartSAFE eVault earned MISMO’s eVault System Certification, adding to existing MISMO certifications for its eClosing system and remote online notarization capabilities.

Across market cycles, DocMagic has maintained a focus on reliability, compliance and scale. That consistency has allowed lenders, credit unions and independent mortgage banks to expand digital execution without adding operational burden or risk.

The MortgagePoint Tech Excellence Awards annually spotlight organizations advancing essential technology across mortgage and real estate. To learn more and view the full list of honorees, visit https://themortgagepoint.com/2026/06/15/meet-this-years-mortgagepoint-tech-excellence-award-recipients/.

About DocMagic:

DocMagic® provides a complete digital mortgage platform for the mortgage industry, delivering proprietary document generation, automated compliance, eSignature, eClosing, eNotarization, eNote and eVault technology in one unified solution. Built on nearly 40 years of innovation, DocMagic helps lenders, settlement service providers and investors move loans from application through post-closing with greater speed, accuracy and confidence. AI deepens that foundation through the company’s Intelligent Agentic Network. For more information, visit www.docmagic.com.

Logo link for media: https://www.docmagic.com/sites/default/files/img/logo/docmagic-logo-reg.png

NEWS SOURCE: DocMagic, Inc.


This press release was issued on behalf of the news source (DocMagic, Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/docmagic-named-2026-mortgagepoint-tech-excellence-award-recipient-for-digital-mortgage-innovation/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136266 NOREL-3B