Tag Archives: mortgage point-of-sale

[RETRACTED] FirstClose Unveils XpressEquity with Enhanced Encompass Integration to Deliver an End-to-End Home Equity Platform Powered by Intelligent Automation

[RETRACTED] – The company issuing this announcement, FirstClose has retracted this news announcement issued March 12, 2026, and notes this content should not be used as provided.

******************************************************************

AUSTIN, Texas, March 12, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced the rebrand of its point-of-sale (POS) experience as XpressEquity, along with a refreshed Encompass® by ICE Mortgage Technology® integration that delivers a streamlined, end-to-end digital workflow for home equity originations. Together, the platform is designed to help Encompass lenders close home equity loans in as little as 5–10 days.

###

******* RETRACTED *************

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-unveils-xpressequity-with-enhanced-encompass-integration-to-deliver-an-end-to-end-home-equity-platform-powered-by-intelligent-automation/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133836 NOREL-3B


Floify launches Dynamic Apps 2.0, enabling lenders to create fully customizable loan applications

New capability allows mortgage teams to tailor borrower applications by loan purpose while embedded AI automates data capture and underwriting preparation

BOULDER, Colo., March 10, 2026 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced the release of Dynamic Apps 2.0, a major platform enhancement that allows lenders to create fully customizable loan applications tailored to specific loan purposes, borrower scenarios and business workflows without relying on engineering resources or third-party integrations.

Floify logo
Image caption: Floify.

With Dynamic Apps 2.0, lenders can configure application experiences for loan types beyond traditional purchase and refinance mortgages, including HELOCs, construction loans, agricultural lending, non-QM products and other specialized financing options, without requiring custom development or separate application flows.

This new capability enables lenders to control which application sections and questions appear for each loan type and automate downstream processes such as document requests and disclosures, allowing them to expand into new lending categories while maintaining a single, scalable technology platform.

Dynamic Apps 2.0 works in sync with Floify’s previously embedded AI capabilities to extract borrower data from uploaded documents, auto-populate portions of the 1003 loan application, validate document uploads and assist with income calculations and underwriting preparation. By combining configurable workflows with automation, lenders can reduce manual data entry, improve application accuracy and accelerate file readiness earlier in the loan process.

“Dynamic Apps 2.0 allows lenders to design application experiences that match their workflows and product mix, whether that’s a traditional mortgage, a HELOC or a specialty lending program,” said Sydney Barber, head of product at Floify. “By tailoring the application structure to the loan purpose, lenders can capture the right information upfront and eliminate unnecessary friction for both borrowers and lending teams.”

“This is a major step forward in turning the POS into a configurable growth platform for lenders,” said Joshua Steffan, SVP and Group General Manager at Porch Group and Interim President and General Manager of Floify. “By pairing configurable applications with embedded AI automation, lenders can streamline data capture, reduce manual work and move cleaner loan files through the process faster.”

Dynamic Apps 2.0 is available now. Learn more at booth 713 at ICE Experience, March 16–18 and request a demo at https://bit.ly/3NgpE5j

ABOUT FLOIFY:

Floify is a fully configurable point of sale (POS) platform that streamlines the loan process with a secure application, communication and document portal between lenders, borrowers, referral partners and other mortgage stakeholders. Its Dynamic AI feature reimagines the mortgage application process by moving document collection and AI-driven data extraction to the very beginning of the process, allowing borrowers to upload key documents and have applications prepopulated with verified information, accelerating pre-approvals and simplifying the borrower experience. Floify is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more, visit https://floify.com/ or find us on social media at Facebook, LinkedIn or Twitter / X.

X: @Floify #mortgage #fintech #housingfinance

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/floify-launches-dynamic-apps-2-0-enabling-lenders-to-create-fully-customizable-loan-applications/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133794 NOREL-3B


LenderLogix expands LiteSpeed POS with built-in AI-powered agent for mortgage loan officers

AI Sidekick delivers instant insights to improve loan accuracy and reduce loan processing times by up to 40%, leading to increased borrower satisfaction

BUFFALO, N.Y., Nov. 10, 2025 (SEND2PRESS NEWSWIRE) — LenderLogix, a leading provider of mortgage point-of-sale and automation software for banks, credit unions, independent mortgage banks, and brokers, today announced it has launched AI Sidekick, an artificial intelligence (AI) feature built into the LiteSpeed point-of-sale (POS) platform. AI Sidekick supports loan officers (LOs) with simple tools to instantly review loan files, efficiently update document needs lists and rapidly identify missing data, reducing loan processing times by up to 40%.

LenderLogix
Image caption: LenderLogix.

AI Sidekick is designed to support mortgage lending, empowering LOs by streamlining highly manual back-end tasks. It scans and analyzes loan details in seconds, providing LOs with critical insights into potential compliance errors and missing documentation, minimizing risk while improving turnaround time without disrupting current processes. Built with SOC 2–compliant infrastructure and end-to-end encryption, AI Sidekick ensures that borrower data remains fully secure within lenders’ existing Encompass® environments.

AI Sidekick also enables LOs to update borrowers’ needs lists with a single click, reducing manual data entry. By surfacing insights and missing documentation early in the loan process, AI Sidekick improves accuracy, reduces processing time and enhances the borrower experience.

“With AI Sidekick, we’re giving lenders a way to eliminate bottlenecks in the loan process without adding complexity,” said LenderLogix CEO Patrick O’Brien. “It’s not about replacing people but about equipping them with modern tools. AI Sidekick doesn’t interact with borrowers, instead acting as a true copilot for LOs to automate the most time-consuming parts of loan file review so they can focus on what they do best: building relationships and delivering great service.”

Visit https://info.lenderlogix.com/litespeed-ai-sidekick to request a demo.

About LenderLogix

LenderLogix leverages the four decades of firsthand mortgage origination and real estate experience of its executive team to design customized software to meet the needs of today’s mortgage lenders. The company’s suite of products addresses the speed at which today’s real estate market moves by delivering technology solutions that create agile and informed borrowers, build strong referral partners and ultimately save lenders time and money. For more information, visit https://www.lenderlogix.com/.

LOGO link for media (white): https://info.lenderlogix.com/hs-fs/hubfs/lenderlogix-logo_white.png

NEWS SOURCE: LenderLogix


This press release was issued on behalf of the news source (LenderLogix), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/lenderlogix-expands-litespeed-pos-with-built-in-ai-powered-agent-for-mortgage-loan-officers/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130867 NOREL-3B


Peak Residential implements Argyle-LenderLogix integration – LiteSpeed first POS to integrate with Argyle VOA

BUFFALO, N.Y., Oct. 2, 2025 (SEND2PRESS NEWSWIRE) — LenderLogix, a leading provider of mortgage point-of-sale (POS) and automation software for banks, credit unions, independent mortgage banks and brokers, today announced that Peak Residential Lending (Peak) has adopted LenderLogix’s LiteSpeed™ integration with Argyle to deliver verification of assets (VOA) directly at the point of sale (POS). LiteSpeed is the first POS to offer VOA through Argyle’s verification platform.

LenderLogix
Image caption: LenderLogix logo.

Through the integration, Peak’s loan teams can access structured, verified data from the start of the application process, including transaction history, asset summaries and rental history. Using income, employment or asset verifications from Argyle enables lenders to qualify for rep and warrant relief on validated components under Fannie Mae’s Day 1 Certainty® program and Freddie Mac’s Asset and Income Modeler (AIM) capability in Loan Product Advisor®.

LiteSpeed’s integration with Peak’s loan origination system (LOS), Encompass® by ICE Mortgage Technology®, further reduces manual touchpoints, driving efficiency and accuracy throughout the loan lifecycle. For Peak borrowers, the mortgage application is faster and less stressful. Instead of searching for and uploading bank statements, assets are verified in minutes, delivering the digital convenience today’s consumers expect.

“VOA delivered at the POS is not just a feature, it’s a fundamental shift in how we serve our borrowers,” said Peak Co-Founder Charley Bates. “By eliminating manual document collection and reducing back-and-forth follow-ups, we start every file with verified, consumer-permissioned data. That cuts days off the process for our loan teams while giving customers the modern, digital experience they expect when applying for a mortgage. We can focus more on guiding borrowers through the process and less on paperwork.”

“Peak Residential’s implementation is a clear example of how technology can streamline processes and allow lenders to focus on what they do best: originating quality loans,” said Patrick O’Brien, founder and CEO of LenderLogix. “Being the first POS live with Argyle’s VOA is a powerful milestone for the industry and for our customers. Embedding VOA directly into the POS empowers lenders to originate loans with fewer manual touchpoints, higher accuracy and greater compliance certainty.”

“Asset verification has long been one of the most time-consuming and compliance-sensitive parts of the mortgage process,” said John Hardesty, vice president of Argyle’s mortgage division. “By delivering GSE-accepted data instantly at the point of sale, Peak Residential is showing how this integration reduces risk from the very beginning of the loan and ensures lenders can originate with confidence.”

This is the latest in a series of LiteSpeed integrations with leading consumer-permissioned verification providers, underscoring LenderLogix’s commitment to delivering flexibility and choice for lenders while ensuring borrowers receive the modern digital experience they expect.

About LenderLogix

LenderLogix leverages the four decades of firsthand mortgage origination and real estate experience of its executive team to design customized software and APIs to meet the needs of today’s mortgage lenders. The company’s suite of products addresses the speed at which today’s real estate market moves by delivering technology solutions that create agile and informed borrowers, build strong referral partners and ultimately save lenders time and money. For more information, visit https://www.lenderlogix.com/.

LOGO link for media: https://www.lenderlogix.com/landing-assets/assets/images/lenderlogix-logo_white.png

NEWS SOURCE: LenderLogix


This press release was issued on behalf of the news source (LenderLogix), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/peak-residential-implements-argyle-lenderlogix-integration-litespeed-first-pos-to-integrate-with-argyle-voa/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129789 NOREL-3B


FirstClose integrates with Optimal Blue to accelerate home equity closings

AUSTIN, Texas, Sept. 29, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, Inc., a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced a certified integration with Optimal Blue that connects FirstClose’s point-of-sale (POS) platform to Optimal Blue’s product, pricing and eligibility (PPE) engine. The integration builds on FirstClose’s ability to reduce home equity closing times from 45 days to 10 or fewer, while also giving lenders access to Optimal Blue’s trusted pricing and eligibility data. Together, these capabilities position lenders to better serve growing demand for home equity lines and second mortgages in today’s purchase-slow market.

FirstClose logo
Image caption: FirstClose logo.

Through the integration, lenders can provide borrowers with a seamless, branded application experience that combines FirstClose’s real-time property data and eligibility information with Optimal Blue’s accurate, lender-specific pricing. Together, these capabilities deliver a transparent process where consumers see precise loan options and rates while navigating their application.

“By integrating our point-of-sale experience with Optimal Blue’s pricing engine, lenders can now deliver borrowers a faster, simpler and more transparent path to access their home equity,” said Tedd Smith, chief executive officer of FirstClose.

“Americans are holding tremendous amounts of home equity, and this integration gives lenders a seamless path to present borrowers with real-time, accurate pricing information from Optimal Blue,” said Mike Vough, head of corporate strategy at Optimal Blue. “By creating more transparency of product and pricing for homeowners, lenders are better positioned to help borrowers take advantage of home equity opportunities.”

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce cost for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist the lender’s borrowers more effectively, reduce closing costs and ultimately shorten closing times. For more information, visit https://www.firstclose.com/.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-integrates-with-optimal-blue-to-accelerate-home-equity-closings/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129643 NOREL-3B


Genisys Credit Union partners with Floify to enhance the member mortgage experience

Top 75 credit union selects Floify's flexible platform to streamline workflows and expand digital lending capabilities

BOULDER, Colo., Sept. 23, 2025 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced that Genisys Credit Union has selected its platform to streamline mortgage lending workflows and deliver an improved member experience. The partnership reflects Genisys’ focus on flexible technology solutions and Floify’s commitment to supporting credit unions with scalable tools.

Genisys Credit Union partners with Floify
Image caption: Genisys Credit Union partners with Floify.

Genisys Credit Union, headquartered in Auburn Hills, Michigan, serves over 290,000 members through its 30 branches across Michigan and Minnesota. The credit union offers a full range of financial products and services, including real estate lending, personal banking and investment solutions.

Genisys is fully implementing Floify to modernize and replace outdated legacy systems. With Floify, loan officers can manage multiple workflows seamlessly, supporting traditional loan products and specialized offerings such as new construction and home equity lines of credit (HELOCs). The platform enhances efficiency, streamlines borrower experiences and positions Genisys to stay ahead of industry demands. Genisys looks forward to learning more about Floify’s forthcoming Dynamic AI feature, further boosting automation and the ability to customize workflows.

“Floify appears very easy to navigate for users with an embedded verification workflow, and it is cost-effective,” said Lance Smith, Vice President of Real Estate Lending at Genisys. I see Floify significantly enhancing our customer experience, data gathering at POS, and developing some excellent AI tools, all of which help the efficiency of our sales team.”

The collaboration underscores both organizations’ commitment to advancing digital lending for credit union members.

“Credit unions like Genisys are investing in technology to compete more effectively and better serve their members,” said Joshua Steffan, senior vice president and group general manager at Porch Group and interim president and general manager of Floify. “By delivering configurable workflows and responsive customer service, Floify is helping credit unions modernize mortgage lending and elevate the member experience.”

About Floify:

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to create product-specific applications (no coding required!), collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more information, visit the company’s website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

Twitter: @Floify @GenisysCU #mortgage #fintech #housingfinance

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/genisys-credit-union-partners-with-floify-to-enhance-the-member-mortgage-experience/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129495 NOREL-3B


Floify introduces Dynamic Apps so lenders can tailor applications by loan type while supporting regulatory compliance

No-code custom loan applications supports improved borrower experience and faster loan processing

BOULDER, Colo., March 3, 2025 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced Dynamic Apps, a no-code feature that lets lenders tailor loan applications based on loan type. By eliminating irrelevant questions, Dynamic Apps shapes the home financing journey to borrowers’ unique goals while helping lenders accelerate approvals, improve application completion rates and maintain regulatory compliance.
Floify
Image caption: Floify.

Traditional loan applications follow a one-size-fits-all structure, often requiring borrowers to answer unnecessary questions. Dynamic Apps personalizes the application process by prompting borrowers to specify their loan purpose — such as purchase or refinance — at the beginning of the application for appropriate routing to specific questions. Based on their selection, the application adjusts, only guiding borrowers through questions relevant to their loan type.

Notably, Dynamic Apps allows lenders to create custom questions for specialized mortgages, such as non-QM and HELOC loans. It also supports HELOC lending compliance by presenting HELOC-specific disclosures within the loan application and by triggering HELOC-specific, rule-based workflows once a HELOC application has been submitted.

The configuration of questions to ask, require, or disable is based entirely on what the borrower selects upfront as their loan purpose. Dynamic Apps lets lenders customize question flow rather than omitting questions or entire sections from their application for certain loans. This enables borrowers to complete applications faster while improving application completion rates and helping lenders remain in compliance with industry regulations, such as those that prohibit asking applicants to provide demographic information for certain loan types.

“We see allowing lenders to collect information specific to the type of loan they are originating as a game-changer, streamlining the approval process and providing a red carpet experience for loan applicants,” says Sofia Rossato, president and general manager of Floify. “In essence, Dynamic Apps supports easily configurable, no-code application types that reduce application fallout and ultimately help lenders do more business.”

Dynamic Apps will be showcased at ICE Mortgage Technology’s ICE Experience, March 10-12, at Booth 417. Later in 2025, Floify will enhance Dynamic Apps to support additional types of loan application workflows.

About Floify

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more information, visit the company’s website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

Forward-Looking Statements

Certain statements in this release may be considered “forward-looking statements” within the meaning of the “safe harbor” provisions of the United States Private Securities Litigation Reform Act of 1995. Although the Company believes that its plans, intentions, and expectations reflected in or suggested by these forward-looking statements are reasonable, the Company cannot assure you that it will achieve or realize these plans, intentions, or expectations. Forward-looking statements are inherently subject to risks, uncertainties, assumptions, and other factors which could cause actual results to differ materially from those expressed or implied by such forward-looking statements. Generally, statements that are not historical facts, including statements concerning the Company’s possible or assumed future actions, business strategies, events, or results of operations, are forward-looking statements. These statements may be preceded by, followed by, or include the words “believes,” “estimates,” “expects,” “projects,” “forecasts,” “may,” “will,” “should,” “seeks,” “plans,” “scheduled,” “anticipates,” “intends,” or similar expressions.

These forward-looking statements are based upon estimates and assumptions that, while considered reasonable by Porch and its management at the time they are made, are inherently uncertain. Factors that may cause actual results to differ materially from current expectations include, but are not limited to: (1) expansion plans and opportunities, and managing growth, to build a consumer brand; (2) the incidence, frequency, and severity of weather events, extensive wildfires, and other catastrophes; (3) economic conditions, especially those affecting the housing, insurance, and financial markets; (4) expectations regarding revenue, cost of revenue, operating expenses, and the ability to achieve and maintain future profitability; (5) existing and developing federal and state laws and regulations, including with respect to insurance, warranty, privacy, information security, data protection and taxation, and management’s interpretation of and compliance with such laws and regulations; (6) the Company’s reinsurance program, which includes the use of a captive reinsurer, the success of which is dependent on a number of factors outside management’s control, along with reliance on reinsurance to protect us against loss; (7) uncertainties related to regulatory approval of insurance rates, policy forms, insurance products, license applications, acquisitions of businesses or strategic initiatives, including the reciprocal restructuring, and other matters within the purview of insurance regulators; (8) reliance on strategic, proprietary relationships to provide the Company with access to personal data and product information, and the ability to use such data and information to increase transaction volume and attract and retain customers; (9) the ability to develop new, or enhance existing, products, services, and features and bring them to market in a timely manner; (10) changes in capital requirements, and the ability to access capital when needed to provide statutory surplus; (11) the increased costs and initiatives required to address new legal and regulatory requirements arising from developments related to cybersecurity, privacy, and data governance and the increased costs and initiatives to protect against data breaches, cyber-attacks, virus or malware attacks, or other infiltrations or incidents affecting system integrity, availability and performance; (12) retaining and attracting skilled and experienced employees; (13) costs related to being a public company; and (14) other risks and uncertainties discussed in Part I, Item 1A, “Risk Factors,” in the Company’s Annual Report on Form 10-K for the year ended December 31, 2022, and in Part II, Item 1A, “Risk Factors,” in our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, as well as those discussed in subsequent reports filed with the Securities and Exchange Commission (“SEC”), all of which are available on the SEC’s website at www.sec.gov.

Nothing in this release should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date of this release. Unless specifically indicated otherwise, the forward-looking statements in this release do not reflect the potential impact of any divestitures, mergers, acquisitions, or other business combinations that have not been completed as of the date of this release. Porch does not undertake any duty to update these forward-looking statements, whether as a result of changed circumstances, new information, future events or otherwise, except as may be required by law.

X/Twitter: @Floify #mortgage #fintech #housingfinance

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/floify-introduces-dynamic-apps-so-lenders-can-tailor-applications-by-loan-type-while-supporting-regulatory-compliance/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P124385 NOREL-3B


Floify brings its industry-leading point-of-sale technology to The Mortgage Collaborative as a preferred partner

BOULDER, Colo. /ScoopCloud/ -- Floify, the mortgage industry's leading point-of-sale (POS) solution, today announced that it has joined The Mortgage Collaborative (TMC), the nation's largest independent cooperative network serving the mortgage industry. As a member of TMC's Preferred Partner Network, Floify will provide its intuitive lending platform for mortgage lenders at a discounted rate to TMC members.

"Floify is designed to address the challenges faced by our lender members, such as supporting best-in-class borrower experience, while maintaining efficient production and controlling costs," said TMC President and CEO Melissa Langdale. "We are excited for them to join the TMC Preferred Partner Network and strengthen our community."

Floify Lender Edition provides borrowers with an easy-to-navigate portal where they can apply for and monitor the status of their mortgage loans. An intuitive lender interface helps loan teams reduce costs and operate more effectively with features such as automated workflows, free native eSign, and mortgage disclosure support. Additionally, Floify supports native integrations with dozens of other mortgage technology companies, including several of TMC's preferred partners.

Founded in 2013, TMC empowers mortgage lenders across the country with networking and professional development opportunities, and by sharing best practices and technologies that drive market growth, efficiency and profitability.

"In this highly competitive and high interest rate environment, mortgage lenders need to compete more effectively and provide borrowers with a great digital experience from the time they fill out an application through the close. Out of the box, Floify is easy to customize, and our many integrations save lenders time and money in processing applications and completing documentation requirements," said Floify President and General Manager Sofia Rossato. "While many TMC members already use Floify, we're looking forward to making it available at a special rate to others ready to provide their homebuyers with a seamless, modern mortgage experience."

About Floify

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. ("Porch Group") (NASDAQ: PRCH). For more information, visit the company's website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

About The Mortgage Collaborative

The Mortgage Collaborative was founded in 2013 by four notable industry leaders and is the nation's largest independent mortgage cooperative network. TMC is singularly focused on creating an environment of collaboration and innovation for small to midsize mortgage lenders across the country to reduce cost, increase profitability, and better serve the dynamic and changing consumer base in America. For more information, visit https://www.mortgagecollaborative.com.

Forward-Looking Statements

Certain statements in this release may be considered "forward-looking statements" within the meaning of the "safe harbor" provisions of the United States Private Securities Litigation Reform Act of 1995. Although the Company believes that its plans, intentions, and expectations reflected in or suggested by these forward-looking statements are reasonable, the Company cannot assure you that it will achieve or realize these plans, intentions, or expectations. Forward-looking statements are inherently subject to risks, uncertainties, assumptions, and other factors which could cause actual results to differ materially from those expressed or implied by such forward-looking statements. Generally, statements that are not historical facts, including statements concerning the Company's possible or assumed future actions, business strategies, events, or results of operations, are forward-looking statements. These statements may be preceded by, followed by, or include the words "believes," "estimates," "expects," "projects," "forecasts," "may," "will," "should," "seeks," "plans," "scheduled," "anticipates," "intends," or similar expressions.

These forward-looking statements are based upon estimates and assumptions that, while considered reasonable by Porch and its management at the time they are made, are inherently uncertain. Factors that may cause actual results to differ materially from current expectations include, but are not limited to: (1) expansion plans and opportunities, and managing growth, to build a consumer brand; (2) the incidence, frequency, and severity of weather events, extensive wildfires, and other catastrophes; (3) economic conditions, especially those affecting the housing, insurance, and financial markets; (4) expectations regarding revenue, cost of revenue, operating expenses, and the ability to achieve and maintain future profitability; (5) existing and developing federal and state laws and regulations, including with respect to insurance, warranty, privacy, information security, data protection and taxation, and management's interpretation of and compliance with such laws and regulations; (6) the Company's reinsurance program, which includes the use of a captive reinsurer, the success of which is dependent on a number of factors outside management's control, along with reliance on reinsurance to protect us against loss; (7) uncertainties related to regulatory approval of insurance rates, policy forms, insurance products, license applications, acquisitions of businesses or strategic initiatives, including the reciprocal restructuring, and other matters within the purview of insurance regulators; (8) reliance on strategic, proprietary relationships to provide the Company with access to personal data and product information, and the ability to use such data and information to increase transaction volume and attract and retain customers; (9) the ability to develop new, or enhance existing, products, services, and features and bring them to market in a timely manner; (10) changes in capital requirements, and the ability to access capital when needed to provide statutory surplus; (11) the increased costs and initiatives required to address new legal and regulatory requirements arising from developments related to cybersecurity, privacy, and data governance and the increased costs and initiatives to protect against data breaches, cyber-attacks, virus or malware attacks, or other infiltrations or incidents affecting system integrity, availability and performance; (12) retaining and attracting skilled and experienced employees; (13) costs related to being a public company; and (14) other risks and uncertainties discussed in Part I, Item 1A, "Risk Factors," in the Company's Annual Report on Form 10-K for the year ended December 31, 2022, and in Part II, Item 1A, "Risk Factors," in our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, as well as those discussed in subsequent reports filed with the Securities and Exchange Commission ("SEC"), all of which are available on the SEC's website at www.sec.gov.

Nothing in this release should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date of this release. Unless specifically indicated otherwise, the forward-looking statements in this release do not reflect the potential impact of any divestitures, mergers, acquisitions, or other business combinations that have not been completed as of the date of this release. Porch does not undertake any duty to update these forward-looking statements, whether as a result of changed circumstances, new information, future events or otherwise, except as may be required by law.

News from Floify

Floify, the mortgage industry's leading point-of-sale (POS) solution, today announced that it has joined The Mortgage Collaborative (TMC), the nation's largest independent cooperative network serving the mortgage industry. As a member of TMC's Preferred Partner Network, Floify will provide its intuitive lending platform for mortgage lenders at a discounted rate to TMC members.

Related link: https://floify.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

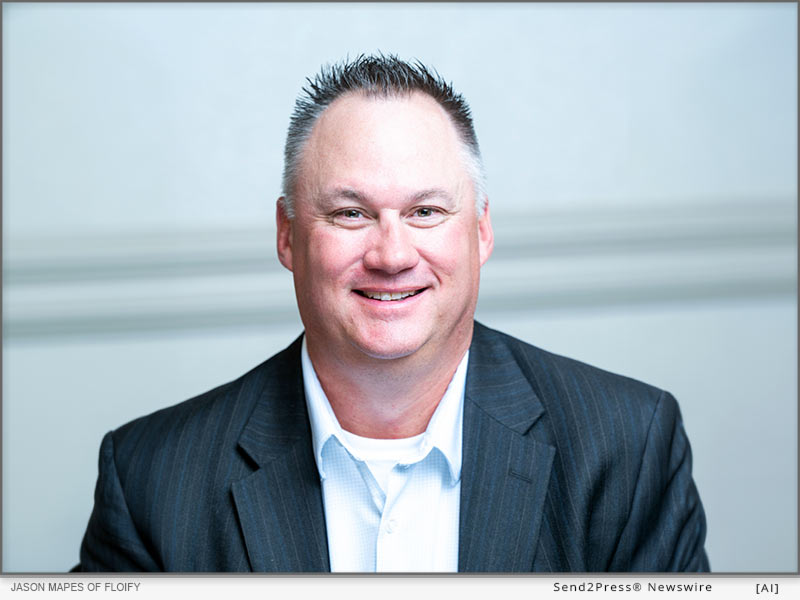
23-year industry veteran Jason Mapes joins Floify as head of sales

BOULDER, Colo. /ScoopCloud/ -- Floify, the mortgage industry's leading point-of-sale (POS) solution, today announced the appointment of Jason Mapes as head of sales. Mapes, who previously served as director of sales for nCino's Mortgage Suite, brings a wealth of experience to spearhead Floify's national sales initiatives.

Mapes's 23 years of experience in the mortgage industry include roles in loan origination, branch management and sales at various organizations, including nCino, Ellie Mae (now ICE Mortgage Technology), Unify and Lenders One. His deep understanding of the mortgage technology ecosystem and relationships with mortgage industry professionals will be instrumental in expanding Floify's market presence.

"Jason is a talented sales executive, and we are excited for him to bring the exceptional capabilities of Floify Lender Edition and Floify Broker Edition to a new usership," said Sofia Rossato, Floify's president and general manager. "His expert-level knowledge of the POS market perfectly positions him to hit the ground running and open new opportunities for Floify."

Mapes joins Floify during a pivotal period of growth as the company rapidly introduces new integrations and expands product functionality. In December 2023, Floify launched Broker Edition, an easy-to-use, one-stop lending platform for mortgage brokers. In March 2024, Floify released Lender Edition to help lenders support a best-in-class borrower experience while streamlining production and controlling costs.

"I'm pleased to join the Floify team and introduce our top-tier POS solutions to a new universe of lenders and brokers who would greatly benefit from their functionality," said Mapes. "I look forward to working shoulder to shoulder with Floify's committed team to simplify home lending for mortgage professionals and consumers alike."

About Floify

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. ("Porch Group") (NASDAQ: PRCH). For more information, visit the company's website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

Forward-Looking Statements

Certain statements in this release may be considered "forward-looking statements" within the meaning of the "safe harbor" provisions of the United States Private Securities Litigation Reform Act of 1995. Although the Company believes that its plans, intentions, and expectations reflected in or suggested by these forward-looking statements are reasonable, the Company cannot assure you that it will achieve or realize these plans, intentions, or expectations. Forward-looking statements are inherently subject to risks, uncertainties, assumptions, and other factors which could cause actual results to differ materially from those expressed or implied by such forward-looking statements. Generally, statements that are not historical facts, including statements concerning the Company's possible or assumed future actions, business strategies, events, or results of operations, are forward-looking statements. These statements may be preceded by, followed by, or include the words "believes," "estimates," "expects," "projects," "forecasts," "may," "will," "should," "seeks," "plans," "scheduled," "anticipates," "intends," or similar expressions.

These forward-looking statements are based upon estimates and assumptions that, while considered reasonable by Porch and its management at the time they are made, are inherently uncertain. Factors that may cause actual results to differ materially from current expectations include, but are not limited to: (1) expansion plans and opportunities, and managing growth, to build a consumer brand; (2) the incidence, frequency, and severity of weather events, extensive wildfires, and other catastrophes; (3) economic conditions, especially those affecting the housing, insurance, and financial markets; (4) expectations regarding revenue, cost of revenue, operating expenses, and the ability to achieve and maintain future profitability; (5) existing and developing federal and state laws and regulations, including with respect to insurance, warranty, privacy, information security, data protection and taxation, and management's interpretation of and compliance with such laws and regulations; (6) the Company's reinsurance program, which includes the use of a captive reinsurer, the success of which is dependent on a number of factors outside management's control, along with reliance on reinsurance to protect us against loss; (7) uncertainties related to regulatory approval of insurance rates, policy forms, insurance products, license applications, acquisitions of businesses or strategic initiatives, including the reciprocal restructuring, and other matters within the purview of insurance regulators; (8) reliance on strategic, proprietary relationships to provide the Company with access to personal data and product information, and the ability to use such data and information to increase transaction volume and attract and retain customers; (9) the ability to develop new, or enhance existing, products, services, and features and bring them to market in a timely manner; (10) changes in capital requirements, and the ability to access capital when needed to provide statutory surplus; (11) the increased costs and initiatives required to address new legal and regulatory requirements arising from developments related to cybersecurity, privacy, and data governance and the increased costs and initiatives to protect against data breaches, cyber-attacks, virus or malware attacks, or other infiltrations or incidents affecting system integrity, availability and performance; (12) retaining and attracting skilled and experienced employees; (13) costs related to being a public company; and (14) other risks and uncertainties discussed in Part I, Item 1A, "Risk Factors," in the Company's Annual Report on Form 10-K for the year ended December 31, 2022, and in Part II, Item 1A, "Risk Factors," in our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, as well as those discussed in subsequent reports filed with the Securities and Exchange Commission ("SEC"), all of which are available on the SEC's website at www.sec.gov.

Nothing in this release should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date of this release. Unless specifically indicated otherwise, the forward-looking statements in this release do not reflect the potential impact of any divestitures, mergers, acquisitions, or other business combinations that have not been completed as of the date of this release. Porch does not undertake any duty to update these forward-looking statements, whether as a result of changed circumstances, new information, future events or otherwise, except as may be required by law.

News from Floify

Floify, the mortgage industry's leading point-of-sale (POS) solution, today announced the appointment of Jason Mapes as head of sales. Mapes, who previously served as director of sales for nCino's Mortgage Suite, brings a wealth of experience to spearhead Floify's national sales initiatives.

Related link: https://floify.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

LenderLogix Announces POS Integration with Informative Research’s AccountChek to Enhance the Mortgage Borrower Experience

BUFFALO, N.Y. /ScoopCloud/ -- LenderLogix, a leading provider of mortgage point-of-sale and automation software for banks, credit unions, independent mortgage banks and brokers, announced the integration of AccountChek by Informative Research into its point-of-sale system LiteSpeed. This integration blends AccountChek's pioneering verification technology into LiteSpeed to seamlessly enhance the borrower experience and optimize the loan origination process to ensure a smooth experience for borrowers and users alike.

"Enhancing our clients' tech stacks with simple, digital-first tools is the foundation of our company's mission, and it's integrations like these that help us further that mission," said LenderLogix Co-Founder and CEO Patrick O'Brien. "By leveraging AccountChek's advanced verification capabilities, we can provide LOs with greater efficiency and accuracy, ensuring all parties experience the highest service standards."

AccountChek by Informative Research streamlines the lending process by providing advanced verification capabilities and seamless data integration for lenders and borrowers alike. With AccountChek's Verification of Assets (VOA), LenderLogix clients can expect enhanced efficiency and accuracy in the loan origination process, with VOA orders routed through the Encompass loan number and documents and data populating directly into the Encompass loan file. The VOA data will flow directly into the automated underwriting systems at the GSEs, allowing the lender seamless access to programs like Day 1 Certainty®, Asset and Income Modeler (AIM) and pre-close employment verifications.

"The integration of AccountChek into the LenderLogix LiteSpeed platform demonstrates our shared commitment to innovation and customer satisfaction while also enabling LenderLogix's clients to streamline the underwriting process by obtaining key verifications at the point of application," said Informative Research's Head of AccountChek Brian Francis. "We look forward to continuing our partnership to deliver impactful innovation to the mortgage lending community and help lenders advance their digital transformation efforts."

About Informative Research:

Informative Research, a Stewart company, is a leading technology platform that delivers data-driven solutions to the lending community. The solutions provider currently serves over 3,000 mortgage companies, banks, and lenders throughout the United States. The company is recognized for streamlining the loan process with its straightforward service model, progressive solutions, and cutting-edge technology. To learn more, visit https://www.informativeresearch.com/.

About LenderLogix:

LenderLogix leverages the four decades of firsthand mortgage origination and real estate experience of its executive team to design customized software and APIs to meet the needs of today's mortgage lenders. The company's suite of products addresses the speed at which today's real estate market moves by delivering technology solutions that create agile and informed borrowers, build strong referral partners and ultimately save lenders time and money. For more information, visit https://www.lenderlogix.com/.

RELATED LINKS:

https://www.informativeresearch.com/accountchek/

https://lenderlogix.com/litespeed-point-of-sale

News from LenderLogix

LenderLogix, a leading provider of mortgage point-of-sale and automation software for banks, credit unions, independent mortgage banks and brokers, announced the integration of AccountChek by Informative Research into its point-of-sale system LiteSpeed. This integration blends AccountChek's pioneering verification technology into LiteSpeed to seamlessly enhance the borrower experience and optimize the loan origination process to ensure a smooth experience for borrowers and users alike.

Related link: https://www.lenderlogix.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Floify named a 2024 HW Tech100 Mortgage honoree

BOULDER, Colo. /ScoopCloud/ -- Floify, the mortgage industry's leading point-of-sale (POS) solution, announced that it has been named a HW Tech100 Mortgage award honoree.

Floify was recognized as an exceedingly user-friendly point-of-sale (POS) whose easy-to-configure platform and rule-based automations have made it beloved among small and midsize lenders and mortgage brokers. Floify's no-hassle platform comes equipped with native features and workflows that help lenders reduce costs and move with agility in any market.

"At Floify, we believe in empowering mortgage brokers and lenders of all stripes with tools that streamline their operations and enable them to adapt swiftly in a dynamic market," said Sofia Rossato, Floify's president and general manager. "Being named among this year's Tech100 Mortgage honorees is a testament to our vision of making mortgage processing as efficient and hassle-free as possible. We are grateful for this acknowledgment and remain dedicated to continuing our pursuit of excellence and innovation in the mortgage technology space."

"The technology capabilities and solutions that this year's Tech100 winning organizations have developed are an absolute testament to the relentless innovation within the real estate and mortgage technology landscape," HW Media Editor-in-Chief Sarah Wheeler said. "These past few years have been transformative for the industry, and these honorees are continuing to bring long-awaited solutions to the challenges that mortgage and real estate professionals have struggled with for decades. Congratulations to all the deserving winners for their outstanding contributions to our ever-evolving industry."

Now in its 12th year, the HW Tech100 recognizes some of the most innovative and impactful technology organizations serving the housing sector.

The full list of HW Tech100 honorees can be viewed at https://www.housingwire.com/.

About Floify:

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. ("Porch Group") (NASDAQ: PRCH). For more information, visit the company's website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

Forward-Looking Statements:

Certain statements in this release may be considered "forward-looking statements" within the meaning of the "safe harbor" provisions of the United States Private Securities Litigation Reform Act of 1995. Although the Company believes that its plans, intentions, and expectations reflected in or suggested by these forward-looking statements are reasonable, the Company cannot assure you that it will achieve or realize these plans, intentions, or expectations. Forward-looking statements are inherently subject to risks, uncertainties, assumptions, and other factors which could cause actual results to differ materially from those expressed or implied by such forward-looking statements. Generally, statements that are not historical facts, including statements concerning the Company's possible or assumed future actions, business strategies, events, or results of operations, are forward-looking statements. These statements may be preceded by, followed by, or include the words "believes," "estimates," "expects," "projects," "forecasts," "may," "will," "should," "seeks," "plans," "scheduled," "anticipates," "intends," or similar expressions.

These forward-looking statements are based upon estimates and assumptions that, while considered reasonable by Porch and its management at the time they are made, are inherently uncertain. Factors that may cause actual results to differ materially from current expectations include, but are not limited to: (1) expansion plans and opportunities, and managing growth, to build a consumer brand; (2) the incidence, frequency, and severity of weather events, extensive wildfires, and other catastrophes; (3) economic conditions, especially those affecting the housing, insurance, and financial markets; (4) expectations regarding revenue, cost of revenue, operating expenses, and the ability to achieve and maintain future profitability; (5) existing and developing federal and state laws and regulations, including with respect to insurance, warranty, privacy, information security, data protection and taxation, and management's interpretation of and compliance with such laws and regulations; (6) the Company's reinsurance program, which includes the use of a captive reinsurer, the success of which is dependent on a number of factors outside management's control, along with reliance on reinsurance to protect us against loss; (7) uncertainties related to regulatory approval of insurance rates, policy forms, insurance products, license applications, acquisitions of businesses or strategic initiatives, including the reciprocal restructuring, and other matters within the purview of insurance regulators; (8) reliance on strategic, proprietary relationships to provide the Company with access to personal data and product information, and the ability to use such data and information to increase transaction volume and attract and retain customers; (9) the ability to develop new, or enhance existing, products, services, and features and bring them to market in a timely manner; (10) changes in capital requirements, and the ability to access capital when needed to provide statutory surplus; (11) the increased costs and initiatives required to address new legal and regulatory requirements arising from developments related to cybersecurity, privacy, and data governance and the increased costs and initiatives to protect against data breaches, cyber-attacks, virus or malware attacks, or other infiltrations or incidents affecting system integrity, availability and performance; (12) retaining and attracting skilled and experienced employees; (13) costs related to being a public company; and (14) other risks and uncertainties discussed in Part I, Item 1A, "Risk Factors," in the Company's Annual Report on Form 10-K for the year ended December 31, 2022, and in Part II, Item 1A, "Risk Factors," in our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, as well as those discussed in subsequent reports filed with the Securities and Exchange Commission ("SEC"), all of which are available on the SEC's website at www.sec.gov.

Nothing in this release should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date of this release. Unless specifically indicated otherwise, the forward-looking statements in this release do not reflect the potential impact of any divestitures, mergers, acquisitions, or other business combinations that have not been completed as of the date of this release. Porch does not undertake any duty to update these forward-looking statements, whether as a result of changed circumstances, new information, future events or otherwise, except as may be required by law.

News from Floify

Floify, the mortgage industry's leading point-of-sale (POS) solution, announced that it has been named a HW Tech100 Mortgage award honoree. Floify was recognized as an exceedingly user-friendly point-of-sale (POS) whose easy-to-configure platform and rule-based automations have made it beloved among small and midsize lenders and mortgage brokers.

Related link: https://floify.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Floify launches comprehensive lending platform for mortgage brokers

BOULDER, Colo. /ScoopCloud/ -- Floify, the mortgage industry's leading point-of-sale (POS), today announced the launch of Floify Broker Edition, an easy-to-use, one-stop lending platform for mortgage brokers.

"Floify Broker Edition is born out of a deep understanding of the unique challenges faced by mortgage brokers, which include juggling a burdensome administrative workload, regulatory compliance and multiple technologies with minimal support," said Floify President and General Manager Sofia Rossato. "The platform is designed to make mortgage lending easier and more cost-effective while enabling mortgage brokers to provide a sleek and intuitive loan management portal for borrowers."

Built on the foundation of the classic Floify POS platform, Broker Edition has been thoughtfully configured to make managing loans simpler at an accessible price point. Floify's borrower-friendly interface increases application pull-through, while rule-based automations promote operational efficiency by performing rote tasks and advancing loans behind the scenes.

Broker Edition comes equipped with four pillar features that enable brokers to use the platform in lieu of a traditional loan origination system (LOS) or as a complement to their existing LOS.

* Mortgage Call Reports (MCR) functionality allows brokers to swiftly generate mandatory NMLS reporting documentation and export reports by quarter, year and state, streamlining a burdensome compliance requirement.

* Dual Automated Underwriting System (AUS) functionality enables brokers to order AUS findings from Fannie Mae and Freddie Mac and view findings side-by-side to identify documentation requirements and counsel borrowers more effectively.

* A Product Pricing Engine (PPE) integration with Lender Price's PPE automatically syncs borrower 1003 data so brokers can provide accurate, real-time pricing quotes.

* A United Wholesale Mortgage (UWM) integration enables brokers to electronically submit loan applications to UWM, substantially expediting the loan submission process.

"Brokers deserve access to the same quality tools as their enterprise lender colleagues and Floify Broker Edition provides exactly that," said Rossato. "We are proud to offer a complete lending platform that makes financing homes easier for brokers and the borrowers they serve."

About Floify

Floify is a digital mortgage automation solution that streamlines the loan process by providing a secure application, communication, and document portal between lenders, borrowers, referral partners, and other mortgage stakeholders. Loan originators use the platform to collect and verify borrower documentation, track loan progress, communicate with borrowers and real estate agents, and close loans faster. The company is based in Boulder, Colorado and is a subsidiary of Porch Group, Inc. ("Porch Group") (NASDAQ: PRCH). For more information, visit the company's website at https://floify.com/ or on social media at Facebook, LinkedIn, or Twitter / X.

Forward-Looking Statements

Certain statements in this release may be considered "forward-looking statements" within the meaning of the "safe harbor" provisions of the United States Private Securities Litigation Reform Act of 1995. Although the Company believes that its plans, intentions, and expectations reflected in or suggested by these forward-looking statements are reasonable, the Company cannot assure you that it will achieve or realize these plans, intentions, or expectations. Forward-looking statements are inherently subject to risks, uncertainties, assumptions, and other factors which could cause actual results to differ materially from those expressed or implied by such forward-looking statements. Generally, statements that are not historical facts, including statements concerning the Company's possible or assumed future actions, business strategies, events, or results of operations, are forward-looking statements. These statements may be preceded by, followed by, or include the words "believes," "estimates," "expects," "projects," "forecasts," "may," "will," "should," "seeks," "plans," "scheduled," "anticipates," "intends," or similar expressions.

These forward-looking statements are based upon estimates and assumptions that, while considered reasonable by Porch and its management at the time they are made, are inherently uncertain. Factors that may cause actual results to differ materially from current expectations include, but are not limited to: (1) expansion plans and opportunities, and managing growth, to build a consumer brand; (2) the incidence, frequency, and severity of weather events, extensive wildfires, and other catastrophes; (3) economic conditions, especially those affecting the housing, insurance, and financial markets; (4) expectations regarding revenue, cost of revenue, operating expenses, and the ability to achieve and maintain future profitability; (5) existing and developing federal and state laws and regulations, including with respect to insurance, warranty, privacy, information security, data protection and taxation, and management's interpretation of and compliance with such laws and regulations; (6) the Company's reinsurance program, which includes the use of a captive reinsurer, the success of which is dependent on a number of factors outside management's control, along with reliance on reinsurance to protect us against loss; (7) uncertainties related to regulatory approval of insurance rates, policy forms, insurance products, license applications, acquisitions of businesses or strategic initiatives, including the reciprocal restructuring, and other matters within the purview of insurance regulators; (8) reliance on strategic, proprietary relationships to provide the Company with access to personal data and product information, and the ability to use such data and information to increase transaction volume and attract and retain customers; (9) the ability to develop new, or enhance existing, products, services, and features and bring them to market in a timely manner; (10) changes in capital requirements, and the ability to access capital when needed to provide statutory surplus; (11) the increased costs and initiatives required to address new legal and regulatory requirements arising from developments related to cybersecurity, privacy, and data governance and the increased costs and initiatives to protect against data breaches, cyber-attacks, virus or malware attacks, or other infiltrations or incidents affecting system integrity, availability and performance; (12) retaining and attracting skilled and experienced employees; (13) costs related to being a public company; and (14) other risks and uncertainties discussed in Part I, Item 1A, "Risk Factors," in the Company's Annual Report on Form 10-K for the year ended December 31, 2022, and in Part II, Item 1A, "Risk Factors," in our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023, as well as those discussed in subsequent reports filed with the Securities and Exchange Commission ("SEC"), all of which are available on the SEC's website at www.sec.gov.

Nothing in this release should be regarded as a representation by any person that the forward-looking statements set forth herein will be achieved or that any of the contemplated results of such forward-looking statements will be achieved. You should not place undue reliance on forward-looking statements, which speak only as of the date of this release. Unless specifically indicated otherwise, the forward-looking statements in this release do not reflect the potential impact of any divestitures, mergers, acquisitions, or other business combinations that have not been completed as of the date of this release. Porch does not undertake any duty to update these forward-looking statements, whether as a result of changed circumstances, new information, future events or otherwise, except as may be required by law.

News from Floify

Floify, the mortgage industry's leading point-of-sale (POS), today announced the launch of Floify Broker Edition, an easy-to-use, one-stop lending platform for mortgage brokers. Built on the foundation of the classic Floify POS platform, Broker Edition has been thoughtfully configured to make managing loans simpler at an accessible price point.

Related link: https://floify.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Affinity Plus Federal Credit Union Selects LenderLogix’s QuickQual to Improve Transparency and Responsiveness During Mortgage Borrowers’ Home Search

BUFFALO, N.Y. /ScoopCloud/ -- LenderLogix, a leading provider of mortgage point-of-sale and automation software for banks, credit unions, independent mortgage banks and brokers, today announced that Minnesota-based Affinity Plus Federal Credit Union (Affinity Plus) has selected its pre-approval letter generation tool QuickQual to provide borrowers with a white-labeled, digitally-driven entry point into their homebuying experience.

"Each member engaging in the mortgage process is different, and we thought our technology should reflect that experience," said Tara Rutz, Mortgage Servicing and Origination Manager, Affinity Plus Federal Credit Union. "QuickQual enables us to deliver a highly engaging experience for our members, including generating pre-approval letters quickly and efficiently. Additionally, the interactive tool will allow members to preview real-time costs (down payment, monthly payments, cash to close, etc...) of purchasing their next home and adjust accordingly to the properties they are viewing within the parameters set forth in the pre-approval."

With QuickQual, loan officers set parameters within the system based on the borrower's maximum pre-approved loan amount. From there, borrowers and their real estate agents can generate pre-approval letters on demand and run payment scenarios based on those parameters, thus providing borrowers with a deeper understanding of their capacity to purchase on a house-by-house basis.

"Affinity Plus is a perfect example of the difference thoughtful tech investment can make in helping credit unions compete effectively in today's market," said LenderLogix Co-Founder and CEO Patrick O'Brien. "This is exactly what we intended when designing our suite of products - to improve lenders' operations by addressing the gaps in their existing tech stack and provide a stellar user experience for their customers."

About LenderLogix:

LenderLogix leverages the four decades of firsthand mortgage origination and real estate experience of its executive team to design customized software and APIs to meet the needs of today's mortgage lenders. The company's suite of products addresses the speed at which today's real estate market moves by delivering technology solutions that create agile and informed borrowers, build strong referral partners and ultimately save lenders time and money.

For more information, visit https://www.lenderlogix.com/.

RELATED LINKS:

https://lenderlogix.com/quickqual-demo

News from LenderLogix

LenderLogix, a leading provider of mortgage point-of-sale and automation software for banks, credit unions, independent mortgage banks and brokers, today announced that Minnesota-based Affinity Plus Federal Credit Union (Affinity Plus) has selected its pre-approval letter generation tool QuickQual to provide borrowers with a white-labeled, digitally-driven entry point into their homebuying experience.

Related link: https://www.lenderlogix.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

The Mortgage Firm selects LiteSpeed from LenderLogix as its POS Platform

BUFFALO, N.Y. /ScoopCloud/ -- LenderLogix, a leading provider of mortgage automation software and application programming interfaces (APIs), today announced The Mortgage Firm, a Florida-based independent retail mortgage lender with branches located throughout the U.S., has selected its streamlined point-of-sale (POS) platform LiteSpeed to power its application process and deliver a superior borrower experience at the initial point of contact.

"As a growth-minded organization, The Mortgage Firm is deeply committed to curating a best-in-class tech stack that empowers our loan officers to focus on the borrower experience and provides a distinct competitive advantage in today's market," said The Mortgage Firm President Todd Pierson. "Having partnered with LenderLogix for more than three years, we've seen the tremendous impact QuickQual and Fee Chaser have had on our operations, so the decision to add LiteSpeed to the mix was an easy one. The ability to implement the system within days versus months, LenderLogix's ongoing, live customer support and it's seamless integration with Encompass(r) only reinforces our decision."

Leveraging LiteSpeed and QuickQual at the front end of its origination process ensures an easy transition for The Mortgage Firm's borrowers from application to approval letter. Once the borrowers move from application to the underwriting phase, Fee Chaser extends the value derived from LiteSpeed and QuickQual through the seamless collection of up-front costs, such as appraisal fees, within the same operating environment. As a result, The Mortgage Firm can deliver a consistent, modern, streamlined experience from the first point of contact through application to complement the high-touch service its loan officers provide.

"The competitive forces working against independent mortgage lenders are as strong as ever. For a lender like The Mortgage Firm that is continuing to grow in a down market, borrower experience must be the key differentiator from both a new business and a recruitment standpoint," said LenderLogix Founder and CEO Patrick O'Brien. "The term 'best-in-class' gets thrown around quite a bit, but this concept sits at the core of both LenderLogix and The Mortgage Firm. Our shared goal of delivering superior technology and customer service has made this partnership especially fruitful, and we are honored that The Mortgage Firm has doubled down on this relationship entrusting LiteSpeed to serve as the gateway to its borrower relationships."

About LenderLogix:

LenderLogix leverages the four decades of firsthand mortgage origination and real estate experience of its executive team to design customized software and APIs to meet the needs of today's mortgage lenders. The company's suite of products addresses the speed at which today's real estate market moves by delivering technology solutions that create agile and informed borrowers, build strong referral partners and ultimately save lenders time and money. For more information, visit https://www.lenderlogix.com/.

News from LenderLogix

LenderLogix, a leading provider of mortgage automation software and application programming interfaces (APIs), today announced The Mortgage Firm, a Florida-based independent retail mortgage lender with branches located throughout the U.S., has selected its streamlined point-of-sale (POS) platform LiteSpeed to power its application process and deliver a superior borrower experience at the initial point of contact.

Related link: https://www.lenderlogix.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

National Bankers Association Endorses Promontory MortgagePath for Mortgage Fulfillment Services and POS Technology

DANBURY, Conn. /ScoopCloud/ -- Leading digital mortgage and fulfillment solutions provider Promontory MortgagePath LLC today announced the National Bankers Association (NBA) has endorsed its mortgage fulfillment services and proprietary point-of-sale technology, Borrower Wallet®.

Founded in 1927, NBA has served as a voice for minority-owned banks. Its members include Black, Hispanic, Asian, Pacific Islander, Native American and women-owned banks across the country, all working to help low- and moderate-income communities that are underserved by traditional banks and financial service providers. NBA's endorsement recognizes Promontory MortgagePath's mortgage fulfillment service and POS technology for their ability to help minority depository institutions (MDIs) build their mortgage businesses.

Utilizing Promontory MortgagePath, NBA's member banks can offer a full suite of mortgage products without the need to invest in significant internal infrastructure while also lowering their origination costs. In addition, Promontory MortgagePath facilitates secondary market investor relationships to support clients' mortgage origination activities.

"Providing our member banks with technology and solutions that will help them increase access to financial services in minority communities is essential to our work," said Nicole Elam, president and CEO, NBA. "We are pleased to have successfully vetted Promontory MortgagePath, which will offer member MDIs shared access to a mortgage fulfillment solution necessary to making homeownership a possibility in communities aspiring to build generational wealth."

Founded by former U.S. Comptroller of Currency Gene Ludwig, Promontory MortgagePath began with a mission of empowering community banks to participate profitably in mortgage lending. Promontory MortgagePath's community development and minority-owned bank initiative is focused on increasing access to homeownership in underserved communities. Via the initiative, Promontory MortgagePath provides competitive pricing models, access to its user-friendly technology, dedicated U.S.-based teams of mortgage experts and robust strategies to help clients drive origination growth, with the overall goal of helping build long-term wealth in communities through increased homeownership.

"Minority depository institutions are critical conduits for financial services in the communities they serve," said Ludwig, founder and CEO of Promontory MortgagePath. "We are proud to have the endorsement of the National Bankers Association, which for nearly 100 years has supported these important institutions. Promontory MortgagePath is committed to working with the NBA to increase access to homeownership, which is central to wealth building in these communities and the American Dream."

The National Bankers Association joins the Community Development Bankers Association (CDBA) and American Bankers Association (ABA), as well as a growing list of state banking associations, in endorsing Promontory MortgagePath's services and technology.

About National Bankers Association

Founded in 1927 as the Negro Bankers Association, today, the association NBA has expanded its membership to also include Hispanic-American, Asian-American, Native American, and women-owned banks. Member banks are located in twenty-two states and the District of Columbia. Recognized as the voice of minority banking in the U.S., the NBA continues its role as chief advocate for these banks in the nation's capital. Through the decades, NBA has helped to shape public policy at the White House, on Capitol Hill, within the regulatory community and throughout the federal bureaucracy. For more information, visit https://www.nationalbankers.org/.

About Promontory MortgagePath LLC | NMLS ID 1532373

Promontory MortgagePath is a fast-growing team of passionate problem solvers on a mission to fundamentally change the way lenders approach their mortgage business. The company combines an intuitive, collaborative digital mortgage platform with modern, comprehensive fulfillment services, giving lenders the progressive technology and scalability required to profitably compete in today's rapidly changing residential mortgage market. Promontory MortgagePath's founder, former U.S. Comptroller of the Currency Gene Ludwig, is widely recognized as a visionary thinker on the critical issues confronting financial services, and his companies are renowned for helping community lenders resolve their most pressing challenges. To learn more, visit https://www.mortgagepath.com.

News from Promontory MortgagePath

Leading digital mortgage and fulfillment solutions provider Promontory MortgagePath LLC today announced the National Bankers Association (NBA) has endorsed its mortgage fulfillment services and proprietary point-of-sale technology, Borrower Wallet®.

Related link: https://www.mortgagepath.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Cloudvirga Selected to Demo Mobile POS at MBA Annual Conference and Expo in Washington, DC

IRVINE, Calif. /ScoopCloud/ -- Cloudvirga(TM), a leading provider of digital mortgage software, announced that it has been selected to demo its recently launched Mobile POS at the Mortgage Bankers Association's Annual Conference & Expo 2018, taking place October 14-17 at the Walter E. Washington Convention Center in downtown Washington, D.C.

Cloudvirga Mobile POS is a mobile-first mortgage point-of-sale solution tuned to serve the needs of loan originators and homebuyers in a purchase mortgage environment. The platform was unveiled September 17 from the stage of the Digital Mortgage conference in Las Vegas.

Backed by the same intelligent mortgage engine that powers Cloudvirga's award-winning Enterprise POS, the Mobile POS allows loan originators to collaborate with borrowers and real estate agents seamlessly and from any web-enabled device.

"Cloudvirga Mobile POS delivers the industry's most advanced digital mortgage technology to loan originators, borrower and real estate agents anytime, anywhere," said Kamrooz. "The marriage of effortless collaboration and productivity-enhancing automation is a must-have for lenders in today's competitive purchase market."

The conference's Discovery Stage is spotlighting the industry's hottest products and services. Cloudvirga will present its Mobile POS at 1:15 p.m. on Monday, October 15 with company Co-founder Kyle Kamrooz leading the demo. Cloudvirga also encourages attendees to visit its booth #455 in THE HUB during Sunday's opening reception or during exhibition hours on Monday (10 a.m. - 5:30 p.m.) and Tuesday (9:30 a.m. - 4 p.m.).

The Mortgage Bankers Association (MBA) is the leading national trade association for the mortgage industry. The MBA's Annual Convention & Expo is the country's largest gathering of real estate finance professionals.

About Cloudvirga(TM)

Cloudvirga's digital mortgage point-of-sale (POS) software, powered by the intelligent Mortgage Platform(r), uniquely combines a world-class borrower experience with a truly automated lender workflow that radically cuts overall loan costs, increases transparency and reduces the time to close a loan. Founded by top fintech veterans with a track record of building successful mortgage technologies, Cloudvirga's customer base includes nine of the top 40 non-bank mortgage originators. To date, Cloudvirga has raised over $77 million from some of the country's top lenders and private-equity firms.

For more information, visit http://www.cloudvirga.com or follow Cloudvirga on LinkedIn.

Twitter: @Cloudvirga #MBAAnnual18 #mortgagePOS

News from Cloudvirga Inc.

Cloudvirga(TM), a leading provider of digital mortgage software, announced that it has been selected to demo its recently launched Mobile POS at the Mortgage Bankers Association's Annual Conference & Expo 2018, taking place October 14-17 at the Walter E. Washington Convention Center in downtown Washington, D.C.

Related link:

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Digital Mortgage Point-of-Sale Pioneer Cloudvirga Hires Sean McEvoy as Chief Customer Officer

IRVINE, Calif. /ScoopCloud/ -- Cloudvirga(TM), developer of intelligent mortgage point-of-sale (POS) platforms, has appointed Sean McEvoy as its chief customer officer. As a member of the senior leadership team, McEvoy will be responsible for the firm's customer leadership, implementation and support functions. He has an extensive background in building world-class customer success organizations at FileNET, IBM, Quest and Dell. He will report to Cloudvirga CEO Michael Schreck.

McEvoy joins on the heels of Cloudvirga's recent addition of five top-30 lender customers to its digital mortgage platform. He brings a global skill set and a track record of success from roles that include vice president of global services and customer support for Dell Technologies (NYSE: DVMT). While there, McEvoy led a team of more than 900 global customer success, support and professional service engineers and contributed to hundreds of millions of dollars in software services and maintenance/renewals business growth.

McEvoy's other career accomplishments include establishing a $200 million renewal sales channel as a business unit executive for IBM (NYSE: IBM); overseeing six acquisitions and launching offshore delivery centers as vice president of support services for Quest Software (acquired by Dell in 2012); and serving as global director of technical consultancy services while vice president of technical operations for FileNET (acquired by IBM in 2006). He holds a master's degree in international business administration and a bachelor's degree in software engineering.

"Delighting our leading lending customers, which include five of the top eight non-bank originators, is core to Cloudvirga's mission in 2018," said Schreck. "We are bulking up our customer success organization to support a growing client base that produced over $100 billion in mortgages in 2017 and employs thousands of loan officers. Sean is a proven leader who can scale enterprise-class organizations to help ensure their success."

"As a software-as-a-service provider, Cloudvirga's long-term success hinges on our ability to help customers meet their desired outcomes," said McEvoy. "I look forward to helping Cloudvirga deliver on this mission."

About Cloudvirga(TM):

Cloudvirga's intelligent mortgage point-of-sale (POS) platforms uniquely combine a world-class borrower experience with a truly digital lender platform that radically cuts overall loan costs, increases transparency and reduces the time to close a loan. Founded by top fintech veterans with a track record of building successful mortgage technologies, Cloudvirga's initial customer roster includes nine of the top 40 non-bank mortgage originators. To date, Cloudvirga has raised over $25 million from some of the country's top lenders and venture capital firms.

For more information, visit http://www.cloudvirga.com/ or follow Cloudvirga on LinkedIn.

*PHOTO for Media: Send2Press.com/300dpi/18-0109s2p-Sean-McEvoy-300dpi.jpg
*Photo Caption: Cloudvirga Appoints Sean McEvoy as Its Chief Customer Officer.

News from Cloudvirga Inc.

Cloudvirga Inc., developer of intelligent mortgage point-of-sale (POS) platforms, has appointed Sean McEvoy as its chief customer officer. As a member of the senior leadership team, McEvoy will be responsible for the firm's customer leadership, implementation and support functions. He has an extensive background in building world-class customer success organizations at FileNET, IBM, Quest and Dell. He will report to Cloudvirga CEO Michael Schreck.

Related link:

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Docutech and Cloudvirga Partner to Help Loan Officers Work More Efficiently

IRVINE, Calif. /ScoopCloud/ -- Cloudvirga(TM), developer of intelligent mortgage point-of-sale (POS) platforms, today announced a partnership with Docutech that will enable Cloudvirga's lender customers to work more efficiently, reduce the cost of document compliance and make the home loan experience more convenient for borrowers.

Docutech is the leading provider of document and compliance technology for mortgage, home equity and consumer lending. Its flagship ConformX(TM) dynamic document generation engine will integrate seamlessly with Cloudvirga's digital mortgage platform, pulling data directly from the POS and leveraging rules-based intelligence to automate the creation of accurate and compliant loan disclosures for all 50 states. The combination of Cloudvirga's comprehensive loan data and Docutech's built-in compliance checks will give loan officers confidence that loan packages are accurate and compliant from the start.

Cloudvirga will also offer Docutech's Solex(TM) eSign and eDelivery functionality. Solex enables borrowers to compliantly review and sign documents using any web-enabled device. When paper delivery of the loan package is required, ConformX print and mail fulfillment service will ensure documents are delivered in the required timeframes.

"By seamlessly combining Cloudvirga's automated workflow, comprehensive guidelines and calculations for all loan products with Docutech's comprehensive suite of document and compliance solutions, we're empowering loan officers to generate disclosures with ease - and to get it right the first time, every time," said Cloudvirga Co-founder and Chief Strategy Officer Kyle Kamrooz.

"Our integration with Cloudvirga enables us to help more loan originators transition away from paper processes that are manual, time-intensive and inflexible in favor of dynamic, technology-enabled processes that streamline operations, improve processing speed and accuracy, reduce cost and delight customers," said Amy Brandt, president and COO of Docutech.

Eight of the top 40 non-bank lenders have chosen Cloudvirga because it re-engineers the mortgage workflow to give consumers greater control over the loan application process and accelerate the mortgage sales funnel for loan officers. The company's digital mortgage technology delivers underwriter-ready loan applications with unmatched speed and quality, resulting in massively reduced costs to produce.

About Cloudvirga(TM):

Cloudvirga's intelligent mortgage point-of-sale (POS) platforms uniquely combine a world-class borrower experience with a truly digital lender platform that radically cuts overall loan costs, increases transparency and reduces the time to close a loan. Founded by top fintech veterans with a track record of building successful mortgage technologies, Cloudvirga's initial customer roster includes eight of the top 40 non-bank mortgage originators. To date, Cloudvirga has raised over $25 million from some of the country's top lenders and venture capital firms. For more information, visit http://www.cloudvirga.com/ or follow Cloudvirga on LinkedIn.

About Docutech

Founded in 1991, Idaho Falls, Idaho and Scottsdale, Ariz.-based Docutech offers a wide range of document technology solutions for mortgage, home equity, and consumer lending from document generation to eDelivery, eSign, eClose, and print fulfillment. The company sets the standard in providing market-proven technology and unrivaled customer service to the financial industry. Docutech's knowledge and solutions empower lending professionals to efficiently produce accurate loan packages in all 50 states to ensure compliance with constantly changing laws and regulations. For more information, visit the company's website at http://www.docutech.com or follow them on social media at LinkedIn or Twitter @Docutech.

News from Cloudvirga Inc.

Cloudvirga, developer of intelligent mortgage point-of-sale (POS) platforms, today announced a partnership with Docutech that will enable Cloudvirga's lender customers to work more efficiently, reduce the cost of document compliance and make the home loan experience more convenient for borrowers.

Related link:

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

ScoopCloud Newswire

Cloudvirga Introduces AccountChek Automated Asset Verification into Its intelligent Mortgage Platform

ATLANTA, Ga. /ScoopCloud/ -- FormFree today announced that cloudvirga(SM), developer of the automated, cloud-based intelligent Mortgage Platform(R) (iMP), has selected AccountChek(TM) for automated asset verification. Cloudvirga's custom integration of AccountChek into the iMP collects borrower account information early in the loan application process and offers a seamless asset verification experience unlike any other mortgage point-of-sale (POS) system in the marketplace today.

"Cloudvirga is re-engineering the mortgage workflow with a relentless focus on increasing efficiency and driving down the cost of lending," said Kyle Kamrooz, co-founder of cloudvirga. "Our partnership with AccountChek by FormFree exemplifies how cloudvirga delivers on the promise of true automation."

A next-generation mortgage POS system, the iMP takes consumer empowerment way beyond the typical digital loan application while automating the entire initial disclosures process for loan officers and consumers in all 50 states. The POS gives consumers and loan officers an automated, intuitive and compliant workflow while moving many traditional back-office tasks to the front of the loan process.

FormFree's flagship app, AccountChek allows borrowers to securely link asset and deposit data from virtually any financial institution. Within seconds, lenders receive detailed analysis on the borrower's ability to repay. Trusted by hundreds of lenders and hundreds of thousands of borrowers, AccountChek was the first provider of asset verification to participate in Fannie Mae's Day 1 Certainty(TM) initiative.

"AccountChek is a perfect fit for the intelligent Mortgage Platform, not just because we're the most trusted name in asset verification, but also because we share cloudvirga's vision of a more modern and efficient way of lending," said Brent Chandler, chief executive officer and founder of FormFree. "By not only collecting but applying sophisticated analysis to borrower data, AccountChek completely eliminates the need for back-office verification."

About cloudvirga(SM):

Cloudvirga is the company behind the cloud-based intelligent Mortgage Platform(R) (iMP) designed to streamline the mortgage process. The platform is digitizing the mortgage industry by deploying an automated workflow to reduce overall cost, increase transparency and shorten the time it takes to close a loan for both borrowers and lenders. Founded by Bill Dallas, Kyle Kamroo, and Mark Attaway, seasoned financial veterans with a proven track record of building mortgage-related technologies, cloudvirga is disrupting the antiquated mortgage industry.

For more information, visit http://www.cloudvirga.com/ or follow cloudvirga on LinkedIn at https://www.linkedin.com/company-beta/7577062/.

About FormFree:

Leading lenders trust Athens, Georgia-based FormFree to deliver automated verification solutions that streamline the loan origination process and provide better intelligence on borrowers' ability to repay. FormFree's flagship app, AccountChek(TM), eliminates the hassle of collecting paper statements from borrowers by using direct-access data untouched by human hands to consolidate, analyze and verify assets. Lender tested and GSE approved, AccountChek securely delivers automated asset verification data and on-demand reports to more than 200 leading U.S. lenders and their millions of customers. FormFree was named one of American Banker magazine's "Top 10 Tech Companies to Watch" in 2015.

For more information, visit http://www.formfree.com/.

*Logos for media:
Send2Press.com/mediaboom/17-0315s2p-accountchek-300dpi.jpg
Send2Press.com/mediaboom/17-0322s2p-cloudvirga-300dpi.jpg

FormFree today announced that cloudvirga(SM), developer of the automated, cloud-based intelligent Mortgage Platform(R) (iMP), has selected AccountChek(TM) for automated asset verification. Cloudvirga's custom integration of AccountChek into the iMP collects borrower account information early in the loan application process and offers a seamless asset verification experience.

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of the Neotrope® News Network - all rights reserved.