Tag Archives: Originations Market Monitor

Mortgage Purchase Lock Counts See First YoY Gain Since Fed Rate Hikes Began Two Years Ago

PLANO, Texas /ScoopCloud/ -- Optimal Blue today released its April 2024 Originations Market Monitor report, which reveals the first year-over-year increase in purchase mortgage lock counts since the Federal Reserve initiated rate hikes in March 2022.

"Purchase lock counts are a key market indicator as they control for changes in home prices and more volatile refi activity, so the year-over-year increase in April is a particularly encouraging sign that mortgage production may be turning a corner," said Brennan O'Connell, director of data solutions at Optimal Blue. "While we are cautiously optimistic, May figures will provide further confidence in the positive trend, as April 2024 numbers got a boost from the Easter holiday landing in March this year."

Key findings from the April 2024 Originations Market Monitor report, which are drawn from direct-source mortgage lock data, include:

* Year-over-year lock count growth: April purchase lock counts rose 5% over April 2023, the first increase in annual lock counts in more than two years.

* Spring homebuying drove overall increase in lock volume: Total monthly rate lock volume increased by 8.7% in April, driven by an 11.0% month-over-month increase in purchase lock volume.

* Declining refinance activity: The refinance share of total volume decreased to 12%, tying the low levels seen during the summer of 2023. Rate/term refinance volume fell by 13.7%, and cash-out volume remained flat.

* Rising interest rates: The benchmark Optimal Blue Mortgage Market Indices (OBMMI) observed significant increases across all categories as higher-than-anticipated inflation readings have cooled market expectations for rate cuts in 2024. The 30-year conforming fixed rate rose 51 basis points to finish the month at 7.24%. This figure is 80 basis points higher than one year ago.

* Shifts in loan type popularity: Nonconforming loan products, including jumbo and non-QM loans, increased their market share by 1.85% to 13.7%. Meanwhile, shares for conforming, FHA, and VA loans declined.

* Increasing loan and home purchase prices: The average loan amount increased $7,200 to $374.5K, and the average home purchase price climbed $14,100 to $477.9K.

The full April 2024 Originations Market Monitor report provides further detail on these findings and more insights into U.S. mortgage market trends: https://www2.optimalblue.com/wp-content/uploads/2024/05/OB_OMM_APR2024_Report.pdf

About the OMM Report:

Each month, Optimal Blue issues the Originations Market Monitor report, which provides early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE - the mortgage industry's most widely used product, pricing, and eligibility engine - the Originations Market Monitor provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders' pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue:

Optimal Blue is a market leader in mortgage secondary marketing technology. The company facilitates transactions among mortgage market participants through its Marketplace Platform, actionable data, and technology vendor connections. The platform supports a range of functions for originators and investors to automate and optimize core processes related to product, pricing, and eligibility, hedge analytics, MSR valuation, loan trading, social media compliance, and counterparty oversight. The company's premier products are used by 68% of the top 500 mortgage lenders in the U.S. For more information on Optimal Blue's end-to-end secondary marketing automation, visit OptimalBlue.com.
News from Optimal Blue

Optimal Blue today released its April 2024 Originations Market Monitor report, which reveals the first year-over-year increase in purchase mortgage lock counts since the Federal Reserve initiated rate hikes in March 2022.

Related link: https://www2.optimalblue.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Average Homebuyer Credit Score Hits the Highest Mark in Years

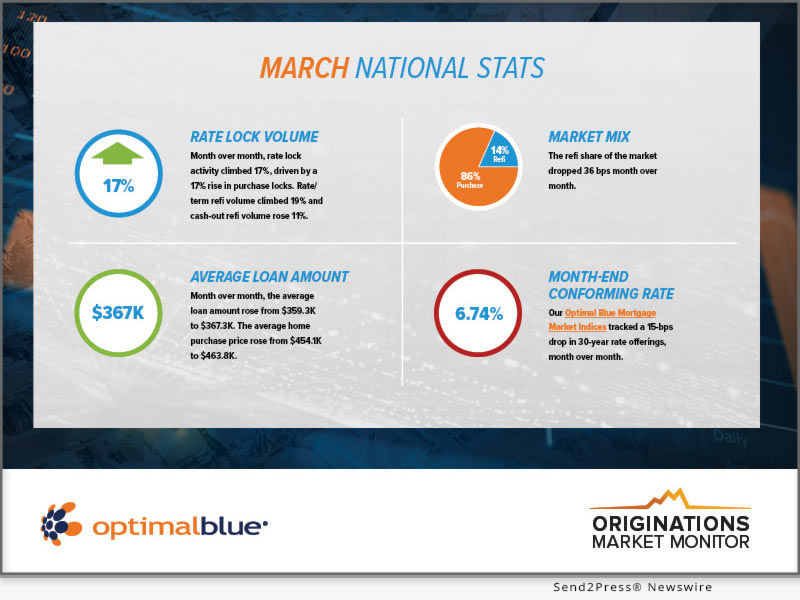
PLANO, Texas /ScoopCloud/ -- Today, Optimal Blue released its March 2024 Originations Market Monitor report, which reveals the average homebuyer credit score has reached 737 - an all-time high since the company began tracking this data in January 2018. Despite the potential buyer pool being somewhat limited to borrowers with higher credit, rate lock volume showed steady month-over-month growth of 17% in March as the spring buying season got underway.

Key findings from the March 2024 Originations Market Monitor report, which reflects month-over-month changes in mortgage lock data, include:

* Unprecedented credit scores: March recorded the highest average borrower credit score for purchase loans at 737 since tracking commenced in January 2018. Similarly, in February and March 2024, FHA borrower credit scores reached six-year highs of 677 and 676, respectively. VA borrower credit scores reached their peak since February 2021, and conforming loan borrower credit scores achieved their highest mark since January 2021.

* Spring rate lock activity surge: March saw a notable 17% increase in rate lock volume, driven by a 17% rise in purchase locks. While refinances comprised a small share of lock volume, rate/term activity rose 19% and cash-out activity rose 11%, aided by an improving rate environment.

* Interest rates tick down: The Optimal Blue Mortgage Market Indices (OBMMI) 30-year benchmark rate decreased by 15 bps to 6.74%, signaling an improving rate environment conducive to both purchase and refinance transactions. The OBMMI jumbo index saw the largest rally, dropping 27 bps to 7.07%.

* Year-over-year comparison: Despite strong month-over-month gains, March purchase lock counts were down 24% from the same period in 2023. This year-over-year decline is likely due to the Easter holiday weekend falling in March this year and April last year. April and May figures will be a better indicator of whether the market is turning a corner.

* Market share adjustments: FHA lending saw its fourth straight month-over-month decline in market share, falling 0.72% to capture a 19% share of total lock volume. FHA volume had seen relatively consistent growth from 2021-2023, with market share growing from 9% to a peak of 23% in November 2023 before the recent stretch of declines.

* Loan amounts and prices increase: The average loan amount rose by $8,000 to $367.3K, and the average home purchase price increased $9,700 to $463.8K.

"Driven by rising interest rates and home prices, we're witnessing the highest average homebuyer credit scores in years," said Brennan O'Connell, director of data solutions at Optimal Blue. "This unprecedented level of creditworthiness among purchasers is largely a result of the affordability issues borrowers face in today's housing market, with prospective buyers with lower credit scores waiting on the sidelines until conditions improve. However, it is encouraging to see a strong pool of qualified buyers still actively pursuing homeownership. This trend underscores the resilience of the market and the adaptability of consumers in navigating the current economic landscape."

The full March 2024 Originations Market Monitor report provides further detail on these findings and more insights into U.S. mortgage market trends: https://www2.optimalblue.com/wp-content/uploads/2024/04/OB_OMM_MAR2024_Report.pdf

About the OMM Report:

Each month, Optimal Blue issues the Originations Market Monitor report, which provides early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE - the mortgage industry's most widely used product, pricing, and eligibility engine - the Originations Market Monitor provides a view of early-stage origination activity.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue:

Optimal Blue is a market leader in mortgage secondary marketing technology. The company facilitates transactions among mortgage market participants through its Marketplace Platform, actionable data, and technology vendor connections. The platform supports a range of functions for originators and investors to automate and optimize core processes related to product, pricing, and eligibility, hedge analytics, MSR valuation, loan trading, social media compliance, and counterparty oversight. The company's premier products are used by 68% of the top 500 mortgage lenders in the U.S.

For more information on Optimal Blue's end-to-end secondary marketing automation, visit http://OptimalBlue.com/.

News from Optimal Blue

Today, Optimal Blue released its March 2024 Originations Market Monitor report, which reveals the average homebuyer credit score has reached 737 - an all-time high since the company began tracking this data in January 2018. Despite the potential buyer pool being somewhat limited to borrowers with higher credit, rate lock volume showed steady month-over-month growth of 17% in March as the spring buying season got underway.

Related link: https://www2.optimalblue.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

Spring Buying Season Kicks Off With an Uptick in Purchase Applications Despite Climbing Interest Rates

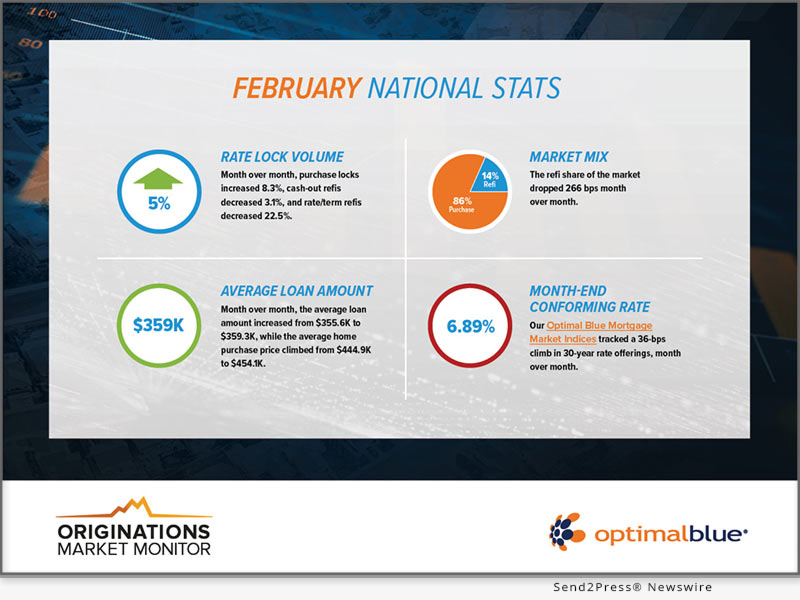
PLANO, Texas /ScoopCloud/ -- Today, Optimal Blue released its February 2024 Originations Market Monitor report, which reveals that the spring homebuying season has kicked off with a jump in monthly purchase mortgage locks. The seasonal spike in purchase locks propelled a net increase in origination activity, even as higher interest rates led to steep declines in mortgage refinances.

Key findings from the February 2024 Originations Market Monitor report, which reflects month-over-month changes in mortgage lock data, show:

* Lock activity up despite steep decline in refinances: Rate lock volumes saw a 5% increase due to a notable 8.3% increase in purchase activity. The rise in purchase activity outpaced the decrease in refinancing activity, which fell by 22.5% for rate/term refinances and 3.1% for cash-out refinances.

* Purchase market nearing its floor: Purchase lock counts, which control for changing home prices, rose 7%, a significant growth compared to the 2% increase in the same period last year during a similar uptick in interest rates. The 7% year-over-year decline in lock activity was the smallest such drop since the Fed began hiking interest rates in March 2022.

* Interest rate trend reverses: The benchmark Optimal Blue Mortgage Market Indices (OBMMI) observed an end to three consecutive months of rate declines - the result of strong economic readings, which significantly lowered market expectations of a near-term rate cut. The OBMMI 30-year conforming rate index rose 36 bps to 6.89%, FHA rose 28 bps to 6.66%, VA rose 41 bps to 6.50%, and jumbo rose 37 bps to 7.35%.

* Non-conforming products see gains: Non-conforming loan products, including jumbo and non-QM loans, claimed an additional 183 basis points of market share, ending the month with 11% of the total volume. Meanwhile, conforming loans maintained a steady 57%, with slight decreases in FHA and VA loans.

* ARMs become slightly more popular: The rate increase nudged the share of ARM loans up, though they still account for only 6% of total production volume. The current economic scenario, particularly the inverted yield curve, will likely constrain further demand growth for these products.

* Credit quality and loan amounts continue upward trend: Credit quality continued to improve across all loan products, except VA loans, which held steady. The average loan amount increased from $355.6K to $359.3K, while the average home purchase price climbed from $444.9K to $454.1K.

"As the spring buying season commenced, we saw a resurgence in purchase locks, despite the rise in interest rates," said Brennan O'Connell, director of data solutions at Optimal Blue. "Although lock counts were down on a year-over-year basis, the rate of decline is decelerating and suggests we may be nearing a floor for purchase lending in the current rate environment."

View the full February 2024 Originations Market Monitor report for more detail: https://www2.optimalblue.com/wp-content/uploads/2024/03/OB_OMM_FEB2024_Report.pdf

About the OMM Report:

Each month, Optimal Blue issues the Originations Market Monitor report, which provides early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE - the mortgage industry's most widely used product, pricing, and eligibility engine - the Originations Market Monitor provides a view of early-stage origination activity.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue is a market leader in mortgage secondary marketing technology. The company facilitates transactions among mortgage market participants through its Marketplace Platform, actionable data, and technology vendor connections. The platform supports a range of functions for originators and investors to automate and optimize core processes related to product, pricing, and eligibility, hedge analytics, MSR valuation, loan trading, social media compliance, and counterparty oversight. The company's premier products are used by 68% of the top 500 mortgage lenders in the U.S.

For more information on Optimal Blue's end-to-end secondary marketing automation, visit https://OptimalBlue.com/.

News from Optimal Blue

Today, Optimal Blue released its February 2024 Originations Market Monitor report, which reveals that the spring homebuying season has kicked off with a jump in monthly purchase mortgage locks. The seasonal spike in purchase locks propelled a net increase in origination activity, even as higher interest rates led to steep declines in mortgage refinances.

Related link: https://www2.optimalblue.com/

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.