Author Archives: Optimal Blue

Optimal Blue announces initial speaker lineup for 2027 Summit

Registration now open for premier event bringing together industry leaders, leading economists, and Optimal Blue innovators to shape what's next in mortgage

PLANO, Texas, Sept. 9, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced its initial speaker lineup for its 2027 Optimal Blue Summit, including Analyst, ESPN Monday Night Football, 3-Time Super Bowl-Winning Quarterback, Pro Football Hall of Famer Troy Aikman. The third annual event shaping what’s next in mortgage will take place February 1–3, 2027 at the JW Marriott Phoenix Desert Ridge Resort and Spa in Scottsdale, Ariz., and bring together the industry’s leading executives, economists and innovators. Registration is now open at Summit.OptimalBlue.com, with early-bird pricing available for a limited time.
Optimal Blue logo.
Image caption: Optimal Blue.

As a leader in AI-driven innovation and the industry’s only end-to-end capital markets platform, Optimal Blue’s annual conference is designed to help mortgage leaders and professionals navigate a rapidly changing market. It will provide more than 500 attendees from across the mortgage ecosystem with access to actionable insights, best-in-class technologies, leading experts and professional networks to help optimize their performance and profitability, all in one Scottsdale destination. Attendees will benefit from a comprehensive agenda featuring to-be-announced speakers and breakout sessions focused on market dynamics, lender trends, rate conditions, secondary-market strategy, product intelligence, and peer insight, plus a front-row view of Optimal Blue innovation, to help them navigate the year ahead.

Ahead of serving as announcer for The Big Game in February, Troy Aikman will take the stage in Scottsdale for a fireside chat with Optimal Blue Chief Executive Officer Joe Tyrrell. The legendary quarterback, Emmy-nominated broadcaster, entrepreneur, and philanthropist will inspire and motivate attendees through lessons learned from his storied career leading high-performing teams on and off the field.

Highlighted industry experts planned to speak at the 2027 Optimal Blue Summit include:

  • Robert (Bob) Broeksmit, CMB, president and chief executive officer, Mortgage Bankers Association
    One of the mortgage industry’s most recognizable and trusted voices, Bob Broeksmit is a senior finance executive with over 35 years of experience across mortgage operations, secondary marketing and servicing. With deep knowledge across all aspects of mortgage lending activities, Bob advocates for more than 2,000 member companies on issues of critical importance and has served as an expert witness in complex mortgage underwriting cases.
  • Michael Fratantoni, Ph.D., chief economist, Mortgage Bankers Association
    Michael Fratantoni oversees MBA’s economic forecasts, industry surveys and benchmarking studies, as well as leads its award-winning economics team. He also serves on the board of CONVERGENCE Collaborative. A leading economist and expert on the trends shaping the mortgage market, Michael delivers data-driven insights to inform and educate mortgage professionals.
  • Joe Tyrrell, chief executive officer, Optimal Blue
    Joe Tyrrell leads Optimal Blue’s strategy to empower lenders with modern technology, actionable data, and AI-driven innovation across the mortgage capital markets lifecycle. With more than 25 years of fintech leadership experience touching all aspects of origination and secondary marketing technologies, he is accelerating the company’s AI-first vision that combines trusted intelligence, automation, and emerging technologies to help lenders make better decisions, operate more efficiently, and unlock new competitive advantages, no matter the market.
  • Erin Wester, chief product officer, Optimal Blue
    Erin Wester oversees product strategy and innovation across Optimal Blue’s mortgage capital markets platform, driving AI-powered solutions that help lenders make smarter decisions, reduce complexity, and improve performance. A mortgage fintech leader with more than 15 years of industry experience, she is known for combining customer-centric innovation, deep industry expertise, and responsible AI leadership to help shape the future of mortgage lending.

“The Optimal Blue Summit is where the conversations shaping the future of mortgage lending turn into action,” said Sara Holtz, chief marketing officer at Optimal Blue. “By bringing together industry and executive voices, emerging technologies and market intelligence, we’re helping lenders navigate change, uncover opportunity, and make better decisions so they can move forward with greater confidence. And this is only the beginning as we continue to add to our lineup.”

In addition to a robust expert speaker roster, the event will feature:

  • Reveals of the latest AI-driven innovations, powered by the new Optimal Blue AI Labs
  • Hands-on trainings, product demonstrations, and client feedback forums that shape future product direction
  • Meaningful connections and networking opportunities with leaders and decision-makers from across the mortgage ecosystem

To learn more about Optimal Blue Summit 2027 and to take advantage of early bird pricing before it ends Oct. 31, visit Summit.OptimalBlue.com.

About Optimal Blue

Optimal Blue powers strategic performance across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes optimize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue helps deliver measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-announces-initial-speaker-lineup-for-2027-summit/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P138048 NOREL-3B


Optimal Blue report: Mortgage demand strengthens as purchase activity and pull-through rebound

Purchase locks reached their highest level since early spring as pull-through rates rebounded and non-conforming lending climbed to a multi-year high

PLANO, Texas, July 9, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its June 2026 Market Advantage mortgage data report, which found that mortgage activity strengthened month over month (MoM), with purchase lock volume climbing to its highest level since early spring and pull-through rates rebounding across both purchase and refinance pipelines. Total rate-lock volume rose 10% MoM and 15% year over year (YoY). June also extended recent shifts in product mix, with non-conforming lending reaching its highest share in several years as conforming volume remained below 49% for the second consecutive month.

Optimal Blue's June 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s June 2026 Market Advantage mortgage data report.

Mortgage rates were mixed in June. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, edged up 1 basis point (bp) MoM to 6.45%, remaining 22 bps lower than June 2025. The 10-year Treasury yield closed the month at 4.44%, down 1 bp MoM, while the spread between the 10-year Treasury and the OBMMI 30-year conforming rate widened to 201 bps.

“June wasn’t defined by a single headline number. Purchase demand strengthened, refinance activity held up and pull-through improved after softening in May,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Together, those trends point to a market that is battle tested and that has adapted to a higher-for-longer rate environment.”

On the secondary side, lenders continued to balance execution options as agency mortgage-backed security (MBS) executions declined for the second consecutive month to 40% of funded loan sales, while best-efforts activity increased to 3%. Execution spreads also moved in different directions, with conventional 30-year best-efforts-to-mandatory spreads tightening to 31 bps and government 30-year spreads widening to 18 bps. Mortgage servicing rights (MSRs) for conforming 30-year loans declined to 1.33% in June.

“We saw lenders continue to fine-tune execution strategy in June,” Vough said. “Agency MBS executions declined again while best-efforts activity increased showing that lenders are evaluating all potential loan sale options, and best efforts-mandatory pricing spreads moved in opposite directions for conventional and government loans. It shows lenders must continue to evaluate execution opportunities on a product-by-product basis.”

KEY FINDINGS FROM THE MARKET ADVANTAGE REPORT, DERIVED FROM DIRECT-SOURCE MORTGAGE LOCK AND SECONDARY MARKET DATA, INCLUDE:

Volume trends and market composition

  • Refis hold steady: Refinance share remained essentially unchanged at 19% of total lock volume in June, materially higher than levels seen throughout much of 2025. Cash-out refinance volume grew 11% MoM and 10% YoY. Rate-and-term refinance volume increased 6% MoM and 32% YoY.
  • Purchase momentum builds: Purchase lock volume increased 10% MoM and 14% YoY, reaching its highest level since early spring. Purchase loans accounted for more than 81% of total lock volume in June.
  • Conforming stays below 49%: Conforming share declined to 49% of total production in June, extending the decline that first pushed it below 50% in April. Non-conforming lending expanded to more than 19% of volume, its highest share in several years. FHA represented nearly 19% of production, while VA loans accounted for almost 13%.
  • Non-QM remains elevated: Non-qualified mortgage loans accounted for 9% of total lock volume in June, 1.4 percentage points higher than a year ago.
  • New construction strengthens: Planned unit developments (PUDs), a proxy for new construction activity, increased to 28% of total volume. Single-family detached homes remained the dominant property type at 64% of production. Condo share held at 6%.

Rates and pricing

  • Mortgage spread tops 200 bps: The OBMMI 30-year conforming fixed rate increased 1 bp MoM to 6.45%, down 22 bps YoY. The 10-year Treasury yield closed at 4.44%, down 1 bp MoM. The spread between the 10-year Treasury and the OBMMI 30-year conforming rate widened to 201 bps, remaining above long-term averages despite narrowing from year-ago levels.
  • MSRs edge lower: MSRs for conforming 30-year loans declined 3 bps to 1.33%, representing a 5.32 multiple.
  • Conventional and government spreads split: Best-efforts-to-mandatory spreads for conventional 30-year products tightened 9 bps to 31 bps. Government 30-year spreads widened 6 bps to 18 bps.
  • Top-tier executions increase: The share of loans sold at the highest price tier increased 78 bps to 78%. Loans sold at the second- and third-ranked price tiers each declined 93 bps and 25 bps to 12% and 3%, respectively. Fourth-tier-or-lower executions increased 40 bps to 7%.

Channel and execution

  • Agency MBS executions decline for second consecutive month: Hedged loan sales to agency MBS declined 1 percentage point to 40% of funded loan sales.
  • Best-efforts activity picks up: Cash and bulk aggregator executions held flat while best-efforts executions increased from 2% to 3% of funded loan sales.
  • Investor count plateaus: Investor participation held at 14 for the second consecutive month after reaching 15 in April.

Product mix and borrower profiles                          

  • First-time buyers regain ground: First-time homebuyers accounted for 45% of conforming purchase locks in June, nearly 3 percentage points above year-ago levels. FHA first-time homebuyer share remained elevated at 69%.
  • DTI ratios remain below year-ago levels: Purchase debt-to-income ratios held below 2025 levels across all major products: conforming borrowers at 36.6%, FHA at 43.5% and VA at 43.0%, suggesting affordability has modestly improved relative to last year despite higher home prices.
  • Borrower credit quality holds steady: The average credit score held at 731, ranging from 757 in the San Francisco Bay Area to 716 in San Antonio. Conforming borrowers averaged a score of 753.
  • Pull-through stays strong: Purchase pull-through increased to 81.4% in June, recovering from May’s decline. Refinance pull-through also climbed to 71.1%.
  • Loan amounts near $400K again: The average locked loan amount increased to just over $399,000 in June, near record highs as home prices continue to appreciate and purchase activity remains concentrated in higher-cost markets. Average loan-to-value (LTV) ratios nationwide were 81.4%, ranging from 71.0% in the greater Los Angeles area to 88.8% in San Antonio.

To view the full June 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Alexandra Kreuter to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

IMAGE link for media: https://www.Send2Press.com/300dpi/26-0709-s2popbluchart-300dpi.webp

Image caption: Optimal Blue’s June 2026 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-mortgage-demand-strengthens-as-purchase-activity-and-pull-through-rebound/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136714 NOREL-3B


Optimal Blue report: Purchase market remains resilient as pull-through rates weaken

More than four out of five mortgage locks were tied to purchase transactions in May, but conversion rates declined across both purchase and refinance pipelines

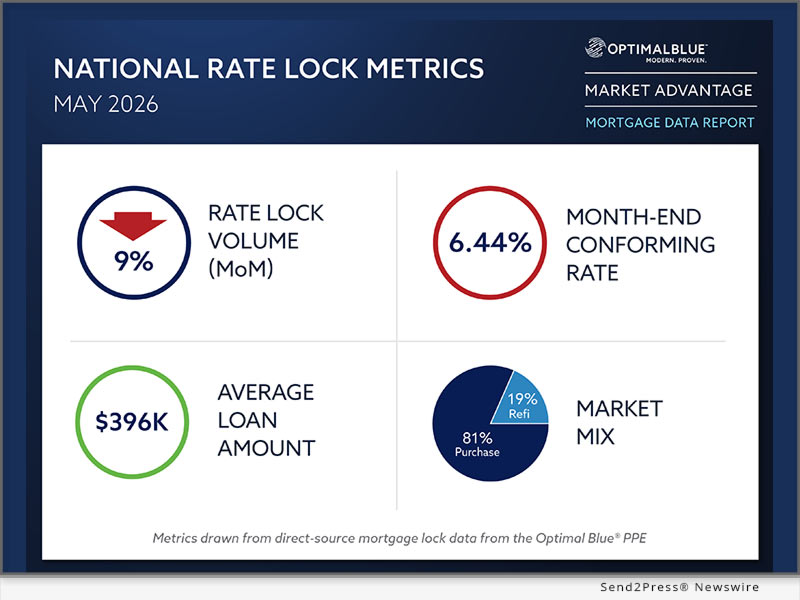
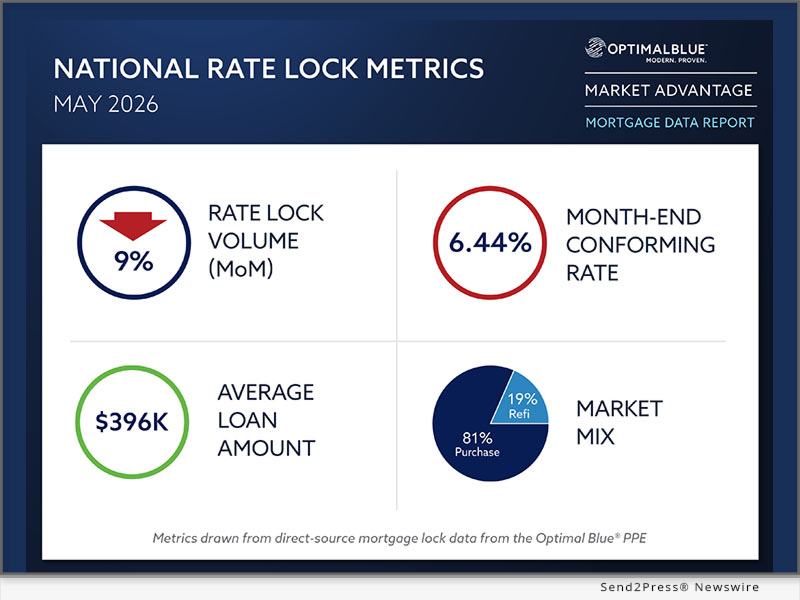
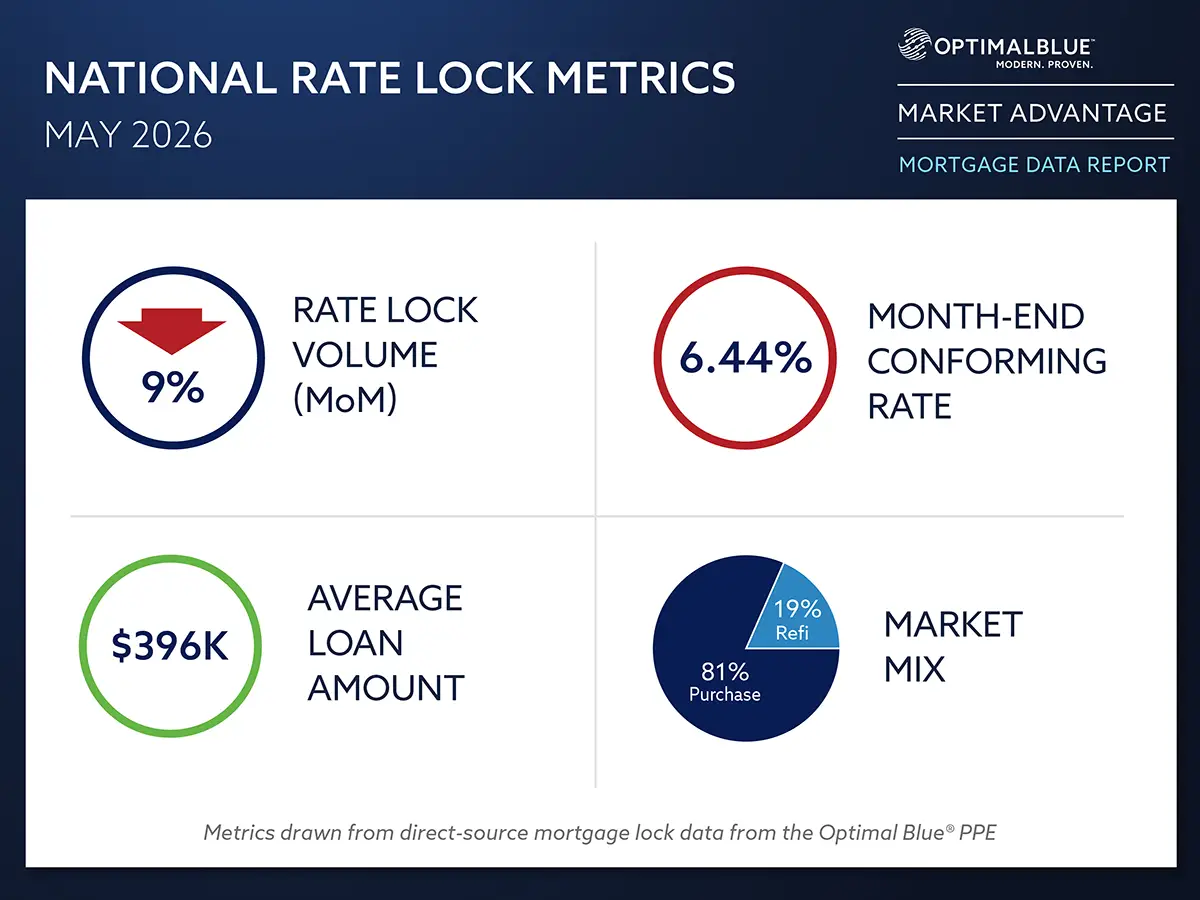
PLANO, Texas, June 9, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its May 2026 Market Advantage mortgage data report, which found that mortgage activity continued to cool as higher rates weighed on both purchase and refinance demand. Total rate-lock volume declined 9% month over month (MoM) but remained 7% higher year over year (YoY). Purchase activity continued to dominate production, accounting for just over 81% of total lock volume, while refinance share fell to 19%, its lowest level since June 2025.

Optimal Blue’s May 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s May 2026 Market Advantage mortgage data report.

Mortgage rates moved higher in May, with the Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate increasing 13 basis points (bps) month over month to 6.44%. The 10-year Treasury yield rose 5 bps to 4.45%, while the spread between the 10-year Treasury and the 30-year mortgage rate widened to just under 200 bps.

“Purchase activity continues to be the loan purpose leader in spite of affordability pressures,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “More than four out of five mortgage locks were tied to purchase transactions in May, but the more notable shift may be what happened after borrowers locked. Pull-through rates declined across both purchase and refinance pipelines, which tells us borrowers are closely monitoring changes in the rate market.”

Secondary market activity reflected shifting execution preferences in May. Agency mortgage-backed securities (MBS) executions declined to 41% of funded loan sales, while cash executions increased to 32%. Mortgage servicing rights (MSRs) for conforming 30-year loans increased 7 bps to 1.36%, representing a 5.44 multiple.

“We saw lenders continue to balance different execution options during May,” Vough said. “Agency MBS share declined while cash executions gained ground, reflecting the impact of agency execution strategies and/or specified pay-up impacts.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refi demand retreats: Refinance share declined to 19% of total lock volume in May, its lowest level since June 2025. Rate-and-term refinance volume fell 34% MoM but remained 46% higher YoY, while cash-out refinance volume declined 13% MoM but remained 7% higher YoY.
  • Purchase share exceeds 80%: Purchase loans accounted for over 81% of total lock volume in May. Purchase lock volume declined 5% MoM but remained 3% higher YoY.
  • Conforming share continues decline: Conforming share declined to just under 49% of total lock volume in May after falling below 50% for the first time in April. FHA share increased to 19%, non-conforming rose to 19%, VA declined to 13% and USDA held at 1%.
  • Non-QM share expands: Non-qualified mortgage loans accounted for 9% of total lock volume in May, up 83 bps MoM and 207 bps YoY.
  • Borrowers continue turning to ARMs: Adjustable-rate mortgages accounted for 11% of total production in May, the highest level since October 2022 outside of March 2026.
  • Property mix favors single-family homes: Single-family homes represented 64% of production in May, while planned unit developments (PUDs), a proxy for new construction activity, accounted for 28% of volume. Condo share declined to 6%.

Rates and pricing

  • Mortgage-to-Treasury spread widens: The OBMMI 30-year conforming fixed rate increased 13 bps MoM to 6.44%. Jumbo rates rose 27 bps to 6.70%, FHA rates increased 21 bps to 6.27% and VA rates climbed 15 bps to 6.06%. The 10-year Treasury yield increased 5 bps to 4.45%, while the mortgage-to-Treasury spread widened to just under 200 bps.
  • Servicing values gain ground: MSRs for conforming 30-year loans increased 7 bps to 1.36%, representing a 5.44 multiple moving in line with OBMMI.
  • Execution spreads diverge: Best-efforts-to-mandatory spreads held at 39 bps for conventional 30-year products and increased 4 bps to 47 bps for conventional 15-year products. Government 30-year spreads decreased 1 bp to 11 bps.
  • Top-tier pricing share declines: The share of loans sold at the highest price tier declined 208 bps to 77%, while fourth-tier-or-lower executions increased 86 bps to 6%. Third-tier share declined 18 bps to 4%.

Channel and execution

  • Agency MBS executions retreat: Hedged loan sales to agency MBS declined 349 bps to 41% of funded loan sales.
  • Cash executions gain share: Cash executions increased 362 bps to 32% of funded loan sales.
  • Investor count returns to 14: Investor participation declined to 14 in May after reaching 15 in April.

Product mix and borrower profiles

  • First-time buyer participation softens: First-time homebuyers accounted for 44% of conforming purchase locks, 70% of FHA purchase locks and 44% of VA purchase locks, reflecting modest declines across all three major product categories.
  • DTI ratios show little change: Purchase debt-to-income ratios remained relatively stable, with conforming at 36.4%, FHA at 43.6% and VA at 42.8%.
  • Credit profiles remain stable: The average purchase credit score held at 731. Conforming borrowers averaged 754, FHA borrowers averaged 677 and VA borrowers averaged 715.
  • Pipeline conversion weakens: Purchase pull-through fell 539 bps MoM to 76.7% and declined 636 bps YoY. Refinance pull-through dropped 1,332 bps MoM to 65.3% but remained 304 bps higher YoY.
  • Loan balances edge higher: The average locked loan amount increased to $395,536 from $394,046 in April, while average loan-to-value (LTV) was 81.6%. Average loan amounts ranged from $917,568 in greater San Francisco to $307,833 in Cincinnati, while regional LTVs ranged from 68.7% in greater San Francisco to 89.1% in San Antonio.

To view the full May 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Alexandra Kreuter to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0609-s2p-opblue-rep-300dpi.webp

Image caption: Optimal Blue’s May 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-market-remains-resilient-as-pull-through-rates-weaken/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P136037 NOREL-3B


Optimal Blue report: Purchase demand holds firm as April lock activity cools

Conforming share drops below 50% for first time since at least January 2018

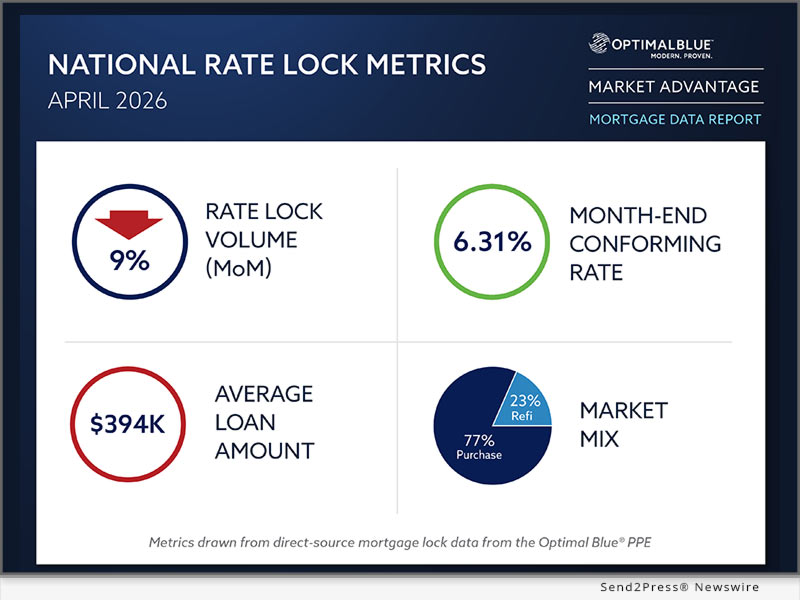
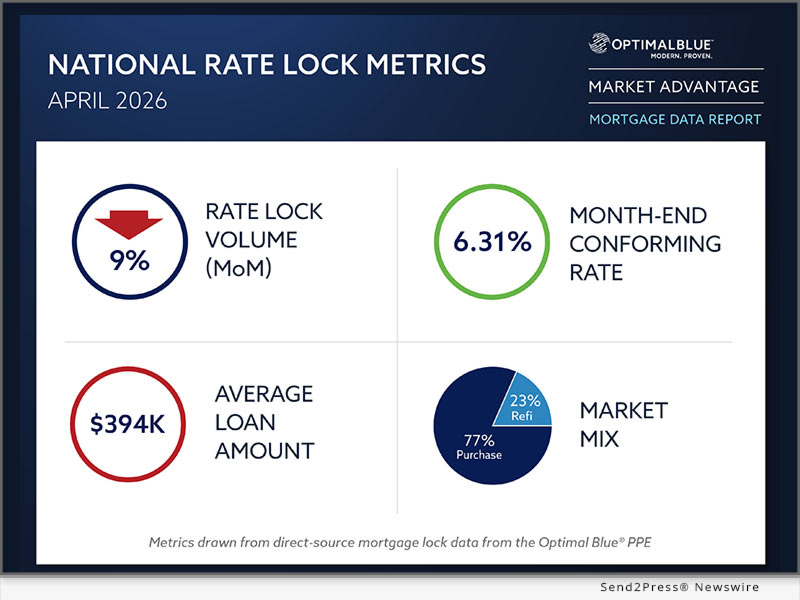
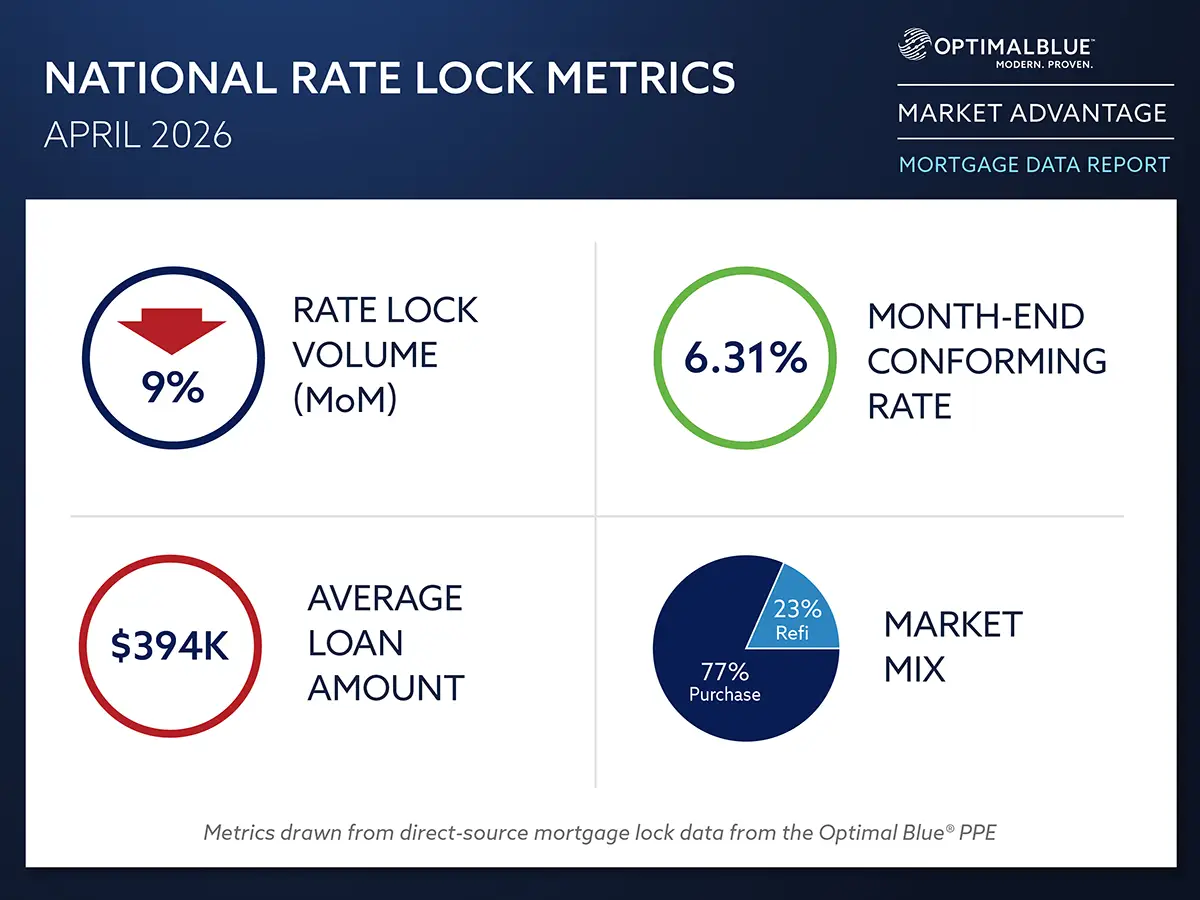
PLANO, Texas, May 12, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its April 2026 Market Advantage mortgage data report, which found that mortgage lock activity pulled back after a strong first quarter. Total rate-lock volume declined 9% month over month (MoM) but remained 11% higher year over year (YoY). Purchase lock volume declined just under 2% from March but increased more than 9% from April 2025, continuing to lead production as refinance activity cooled. Rate-and-term refinance volume fell nearly 38% MoM but remained more than 22% higher YoY, while cash-out refinance volume declined 12% MoM but was up 11% YoY. Refinance share slipped to 23% of total volume, down from March but still above year-ago levels.

Optimal Blue's April 2026 Market Advantage mortgage data report
Image caption: Image caption: Optimal Blue’s April 2026 Market Advantage mortgage data report.

Mortgage rates remained elevated throughout April but finished slightly lower by month-end. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended the month at 6.31%, down 4 basis points (bps) MoM. The 10-year Treasury yield finished April at 4.40%, up 10 bps MoM, while the spread between the 10-year Treasury and the 30-year mortgage rate narrowed to 191 bps as mortgages outperformed.

“April looks more like a cooling from a strong first quarter than a real weakening in borrower demand,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Purchase activity held up well despite rate pressure, while refinance volume reacted more quickly to recent rate moves. That split reinforces how rate-sensitive borrowers remain, even as the spring purchase market continues to show resilience.”

On the secondary side, April data pointed to renewed movement toward agency mortgage-backed securities (MBS) execution. Agency MBS sales increased while bulk loan sales declined, and mortgage servicing rights (MSR) values rose as higher rates reduced expected refinance activity. Investor participation also increased after holding steady for three consecutive months.

“In a higher-rate environment, lenders are paying close attention to where execution value is showing up,” said Vough. “The move toward agency MBS execution, combined with higher MSR values and increased investor participation, continues to prove that lenders need to evaluate all potential execution options to maximize profitability.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refi activity cools: Rate-and-term refinance volume fell nearly 38% MoM but remained more than 22% higher YoY, while cash-out refinance volume declined 12% MoM but rose 11% YoY. Refinance share slipped to 23% of total volume.
  • Purchase activity holds steady: Purchase lock volume declined just under 2% MoM but increased more than 9% YoY, continuing to lead overall production.
  • Conforming share drops below 50%: Conforming share fell just below 50% of total lock volume in April for the first time since Optimal Blue began tracking this metric. FHA share rose to 19%, VA increased to 13%, non-conforming declined to 17% and USDA held steady at 1%.
  • Non-QM share remains elevated: Non-qualified mortgages accounted for 9% of total lock volume in April, up 30 bps MoM and 233 bps YoY, with investor and bank-statement products leading expanded-guideline activity.
  • ARM levels remain elevated: Adjustable-rate mortgages accounted for 10% of total production, down 182 bps MoM but broadly in line with year-ago levels and well above pre-2022 norms.
  • Property mix shifts: Single-family homes represented 64% of production, while planned unit developments, a proxy for new construction activity, declined to 28%, down 42 bps MoM and 326 bps YoY. Condo share also declined to 6%.

Rates and pricing

  • Mortgage rates outperform Treasuries: The OBMMI 30-year conforming fixed rate finished at 6.31%, down 4 bps MoM. Jumbo rates ended at 6.43%, VA rates at 5.90% and FHA rates at 6.06%. The 10-year Treasury increased 10 bps to 4.40%, while the mortgage-to-Treasury spread narrowed to 191 bps.
  • MSR values climb: MSRs rose 5 bps to 1.29%, representing a 5.16 multiple, moving in line with higher rates and lower refinance expectations.
  • Conventional spreads widen: Best-efforts-to-mandatory spreads increased 4 bps for conventional 30- and 15-year products, while government 30-year spreads decreased 3 bps.
  • Lower-tier sales increase: Loans sold to the fourth or lower price tier increased 89 bps to 5%, while third-tier share increased 21 bps.

Channel and execution

  • Agency MBS share increases: Hedged loan sales to agency MBS rose 354 bps to 44%, marking a shift toward securitization executions.
  • Bulk executions decline: Bulk loan sales decreased 257 bps to 25%.
  • Investor count rises: Investor participation increased to 15 in April after holding at 14 for the prior three months.

Product mix and borrower profiles

  • First-time buyers maintain purchase presence: First-time homebuyer share remained nearly flat in April but continued to represent a meaningful share of purchase activity, accounting for 47% of conforming purchase locks, 70% of FHA purchase locks and 45% of VA purchase locks.
  • DTI ratios remain stable: Purchase debt-to-income ratios improved YoY, with conforming at 36.2%, FHA at 43.5% and VA at 42.7%.
  • Credit quality holds firm: The average purchase credit score held at 735, unchanged from March. By product, conforming borrowers averaged 753, FHA borrowers averaged 676 and VA borrowers averaged 716.
  • Pull-through rates improve: Purchase pull-through rose to just over 82%, up 208 bps MoM but down 58 bps YoY. Refinance pull-through increased to just under 79%, up 356 bps MoM and 1,381 bps YoY.
  • Loan amounts decline: The average loan amount was $394,046, down from $401,100 in March and $404,586 in February. The average loan-to-value ratio (LTV) was 81.64%. Loan amounts ranged from $888,871 in greater San Francisco to $302,493 in Cincinnati, while regional LTVs ranged from 71.23% in the Bay Area to 89.05% in San Antonio.

To view the full April 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Alexandra Kreuter to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0512-s2p-opblue0526-300dpi.webp

Image caption: Optimal Blue’s April 2026 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-demand-holds-firm-as-april-lock-activity-cools/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P135303 NOREL-3B


Optimal Blue report: Purchase demand lifts mortgage lock activity as rates rise

Lock volume rises 13% month over month as spring buying season gains traction

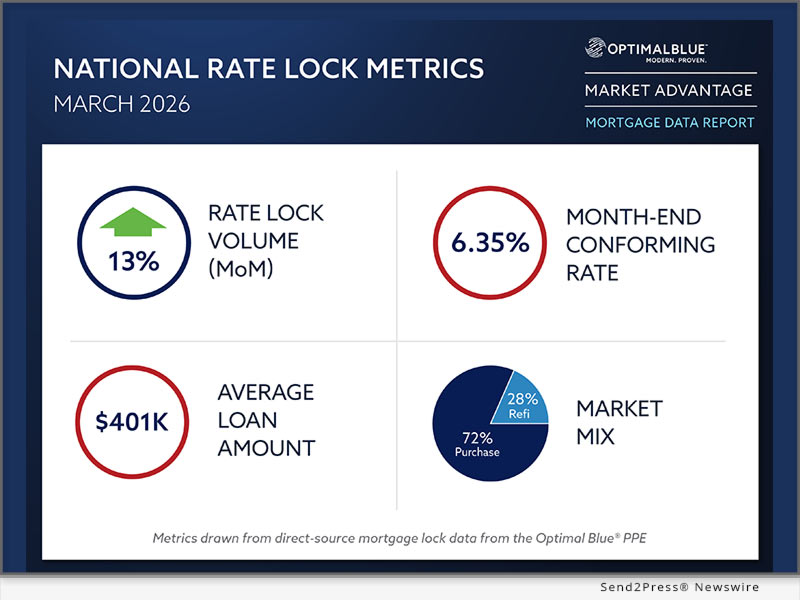
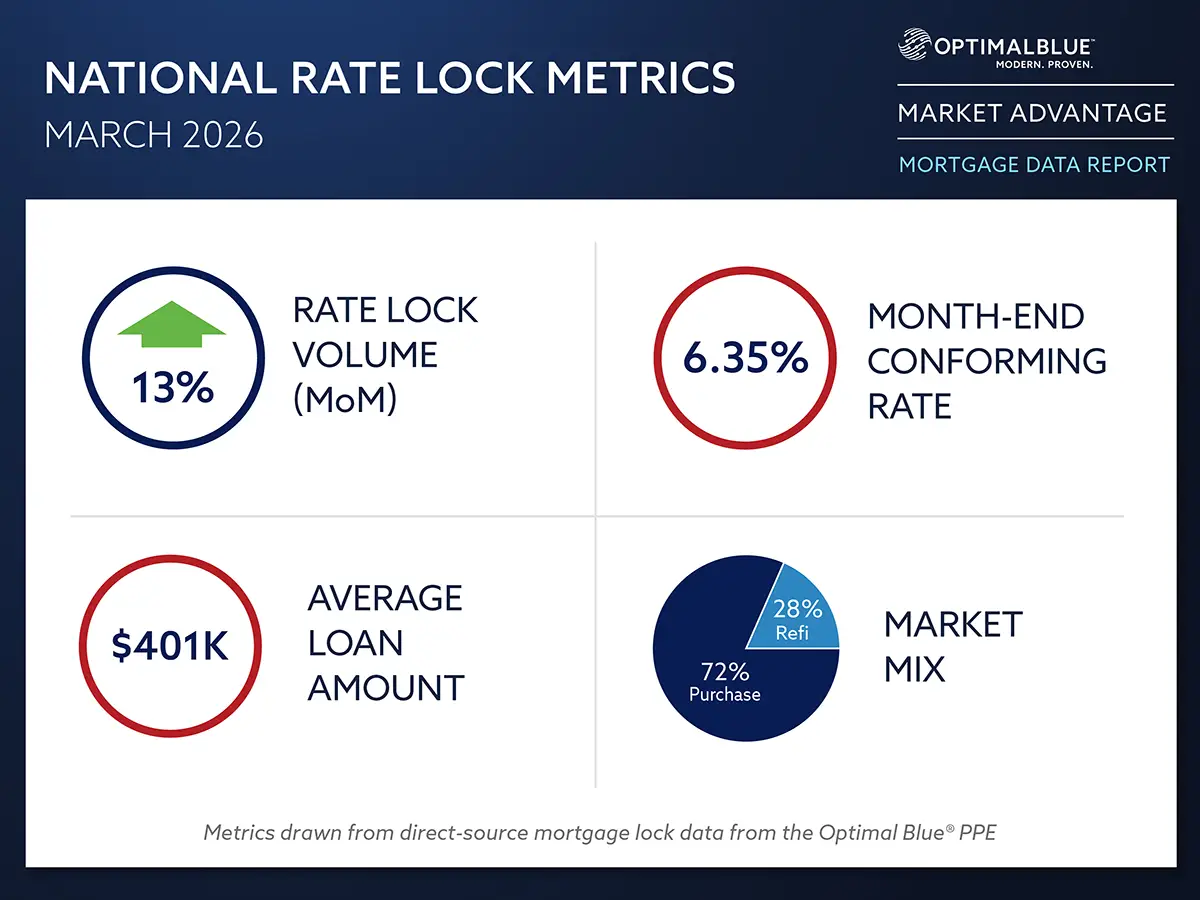
PLANO, Texas, April 14, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its March 2026 Market Advantage mortgage data report, reflecting resilient mortgage activity as purchase demand strengthened despite higher rates. Total rate-lock volume rose 13% month over month (MoM) and 26% year over year (YoY). Purchase activity led the month, with purchase lock volume up 38% from February and 20% from March 2025. Cash-out refinance volume increased 9% MoM and 21% YoY, while rate-and-term refinance volume declined 34% from February but remained more than 66% higher YoY. Refinance share finished March at 28% of total production, down from earlier in the year but still well above 2025 levels.

Optimal Blue's March 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s March 2026 Market Advantage mortgage data report.

​​Mortgage rates moved higher across all major products in March. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended the month at 6.35%, up 45 basis points (bps) from February. Jumbo, VA and FHA rates also increased during the month. The 10-year Treasury yield ended March at 4.30%, up 33 bps, while the spread between the 10-year Treasury and the 30-year rate widened to 205 bps.

“Purchase demand is carrying the market forward even as rates move higher,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “That’s a strong sign for the spring market, especially with refinance share still at 28%, well above where it spent most of 2025.”

On the secondary side, March data reflected modest shifts in execution. Best-efforts-to-mandatory spreads tightened for 30-year products, while agency cash window executions increased 100 bps and securitization activity eased. Mortgage servicing rights (MSR) values also rose 6 bps as higher rates reduced refinance expectations.

“In a higher-rate environment, lenders have to be more deliberate about how they execute and where they find value,” Vough said. “We saw some movement toward the cash window in March, but the more telling signal was MSRs moving higher as refinance expectations came down. That’s the market adjusting to a higher-rate backdrop.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance share eases: Refinances accounted for 28% of total lock volume in March as purchase demand accelerated. Rate-and-term refinance volume declined 34% MoM but remained more than 66% higher YoY, while cash-out refinance volume increased 9% MoM and 21% YoY.
  • Purchase share expands: Purchase locks accounted for just over 71% of total volume in March, with purchase activity rising 38% MoM and 20% YoY as the market moved deeper into the spring selling season.
  • Conforming’s majority narrows: Conforming share declined to just over 50% of total volume in March. FHA and non-conforming share each increased to 18%, while VA share eased to 13% and USDA held steady at 1%.
  • ARM usage climbs: Adjustable-rate mortgages accounted for 12% of total production in March, up 162 bps MoM and reaching the highest mark since October 2022.
  • PUD share rises: Planned unit developments, a proxy for new construction activity, rose to 28% of total volume in March, up 75 bps MoM but down 413 bps YoY.

Rates and pricing

  • Rates move higher: The OBMMI 30-year conforming fixed rate rose 45 bps to 6.35%. Jumbo rates increased 41 bps, VA rates rose 44 bps and FHA rates climbed 21 bps. The 10-year Treasury yield increased 33 bps to 4.30%, while the mortgage-to-Treasury spread widened to 205 bps.
  • MSR values rise: MSRs for conforming 30-year loans increased 6 bps to 1.24%, representing a 4.97 multiple, as higher rates reduced refinance expectations.
  • Execution spreads tighten: Best-efforts-to-mandatory spreads decreased 3 bps for conventional 30-year loans and 5 bps for government 30-year loans, while the conforming 15-year spread increased 7 bps.
  • Top pricing share slips: The share of loans sold at the highest price tier declined 100 bps to 79%, while loans sold in the fourth (or worse) tier decreased 100 bps to 4%.

Channel and execution

  • MBS share slips: Agency mortgage-backed securities (MBS) securitizations accounted for 41% of hedged executions, down slightly from 42% the prior month.
  • Cash window gains ground: Hedged loan sales to the agency cash window rose 100 bps to 28%.

Product mix and borrower profiles

  • First-time buyer share remains high: First-time homebuyers represented 46% of conforming purchase locks and more than 70% of FHA volume in March, while VA first-time buyer share held near 46%. Conforming first-time buyer share was up 3 points over the past three months and 1 point year over year.
  • Borrower profiles remain stable: Debt-to-income (DTI) ratios for purchase loans were 36.3% for conforming loans, 43.3% for FHA and 42.7% for VA in March. Conforming purchase DTI was essentially flat from February, while FHA and VA purchase DTIs moved modestly lower. All three remained below year-ago levels. The average purchase FICO was 732.
  • Loan balances stay elevated: Average loan amount declined to just over $401,000 from $404,586 in February but remained well above year-ago levels. The average loan-to-value ratio (LTV) was 81.32%. Loan amounts ranged from $888,536 in greater San Francisco to $306,283 in Indianapolis, while regional LTVs ranged from 69.88% in the Bay Area to 89.47% in San Antonio.

To view the full March 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0414-s2p-opblue-300dpi.webp

Image caption: Optimal Blue’s March 2026 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-demand-lifts-mortgage-lock-activity-as-rates-rise/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P134536 NOREL-3B


MarketWise Advisors study finds mortgage lenders increase efficiency by over $1,000 per loan with Optimal Blue

Hundreds of surveyed lenders report major improvements in accuracy, operational capacity, execution and risk reduction, including 1,193% ROI for PPE clients

PLANO, Texas, March 17, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced key results of an independent analysis by consulting advisory firm MarketWise Advisors LLC quantifying the operational and financial efficiencies of its end-to-end capital markets platform and the significant value it generates per loan. The study found that mortgage lenders using Optimal Blue technology are more efficient and competitive. Optimal Blue mortgage lenders report an average net financial benefit of $1,006 per loan, reflecting measurable gains in execution quality, error reduction, automation and operational efficiency.

Optimal Blue logo.
Image caption: Optimal Blue logo.

Across the institutions studied, lenders reported improvements in accuracy, performance, operational capacity and capital markets execution. The analysis highlights both the cumulative value created when lenders adopt multiple capabilities across the Optimal Blue ecosystem and the value delivered by specific Optimal Blue technology solutions when combined with individual strategic decision-making. By combining pricing, execution, data and secondary marketing tools within a single platform, lenders are able to scale loan production more efficiently and respond more effectively to changing market conditions.

“In mortgage capital markets, every basis point matters. That is why our core goal is providing our clients with data that enables them to be more competitive. When lenders are gaining more than $1,000 per loan and achieving a rate of return of $12 for every $1 spent, that’s more than efficiency, that is operational advantage,” said Joe Tyrrell, CEO of Optimal Blue. “This independent analysis confirms what our clients experience every day: when lenders have better technology, including use-case specific AI tools backed by real expertise, the impact shows up on their bottom line.

“The results confirm that Optimal Blue delivers substantial, measurable value – contributing to clients’ ability to scale efficiently, improve execution, manage risk and achieve strong returns across the ecosystem,” said Jordan Brown, founding principal and CEO of MarketWise Advisors.

KEY FINDINGS

The analysis identified five key findings showing how lenders use Optimal Blue’s solutions to make smarter decisions, resulting in:

  • Average positive impact of more than $1,000 per loan. Across the Optimal Blue ecosystem, lenders reported an average net benefit of $1,006 per closed loan.
  • Nearly 45% increase in operational capacity. Respondents reported a 43.65% improvement in their ability to manage higher loan volume using Optimal Blue technology without requiring an increase in staff.
  • More than $400 per-loan impact from advanced hedging and secondary marketing tools. The AI-driven hedging and trading capabilities supporting strategic execution, trade optimization, MSR valuation and mark-to-market reporting produced an average financial impact of $401.43 per loan.
  • 12X ROI for Optimal Blue PPE clients. Clients reported a median return on investment of 1,193%, representing nearly $12 returned for every dollar spent with Optimal Blue.
  • Universal error reduction with measurable financial impact. 100% of survey respondents indicated that Optimal Blue helps reduce errors, with 98% reporting financial benefits tied to improved pricing and eligibility accuracy. These benefits represent an average additional gain of $181.83 per loan.

Full results from the study will be available in early May. To explore these key findings in greater detail or be notified when the full report is released, visit https://www2.optimalblue.com/2026-study.

METHODOLOGY

The ROI analysis was conducted by MarketWise Advisors LLC, a consulting advisory firm specializing in financial services technology and benchmarking. The study evaluated client-reported outcomes across Optimal Blue’s end-to-end platform, including its Product and Pricing Engine (PPE), hedging and trading solutions, data solutions and Comergence counterparty oversight solution.

More than a quarter of Optimal Blue’s nearly 1,000 unique lender customers participated in the analysis, representing a balanced mix of banks, credit unions, independent mortgage banks and housing authorities. Because Optimal Blue’s client base spans various segments of the mortgage market, the participating institutions collectively provide a representative cross-section of lender types, sizes and business models.

MarketWise Advisors applied a deliberately conservative methodology to assess value delivery, using median production volumes and client-reported outcomes to quantify financial and operational impact while avoiding assumptions that could overstate results.

NOTE ON RESULTS

Results reflect client-reported outcomes collected as part of the MarketWise Advisors analysis. Neither MarketWise Advisors LLC nor Optimal Blue provide any warranty or representation regarding performance outcomes, which rely on clients’ independent business strategies and decision-making. Individual results may vary.

About Optimal Blue

Optimal Blue powers strategic performance across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes optimize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue helps deliver measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/marketwise-advisors-study-finds-mortgage-lenders-increase-efficiency-by-over-1000-per-loan-with-optimal-blue/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133956 NOREL-3B


Optimal Blue report: Purchase demand rebounds as mortgage market finds balance

Lock volume rises 9% month over month and nearly 40% year over year as lower rates draw borrowers back into the market

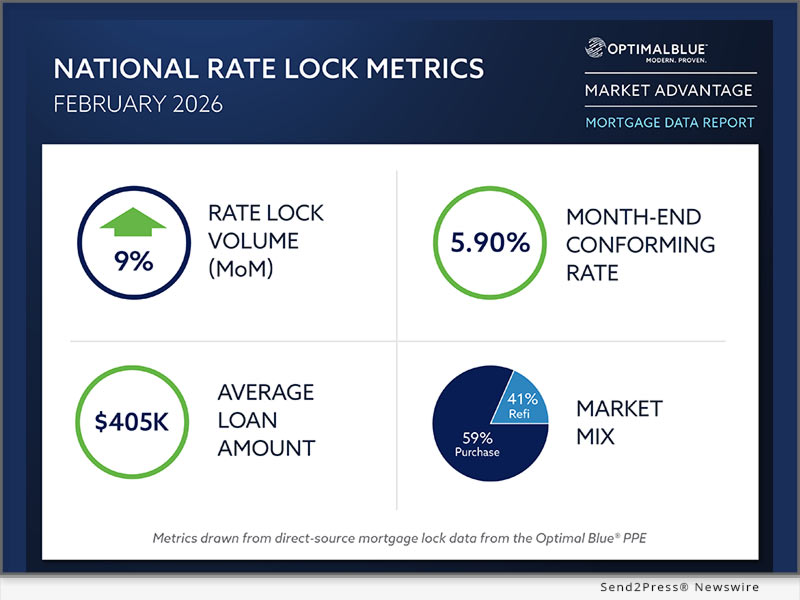
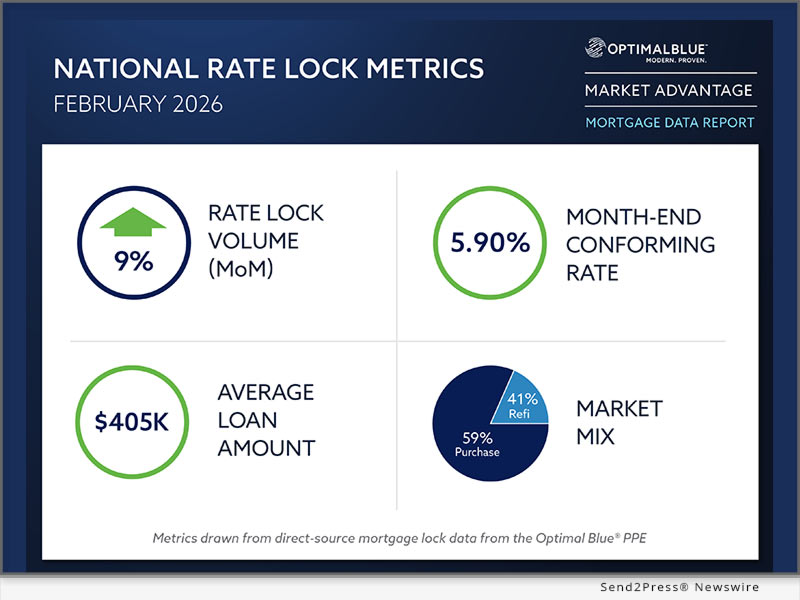
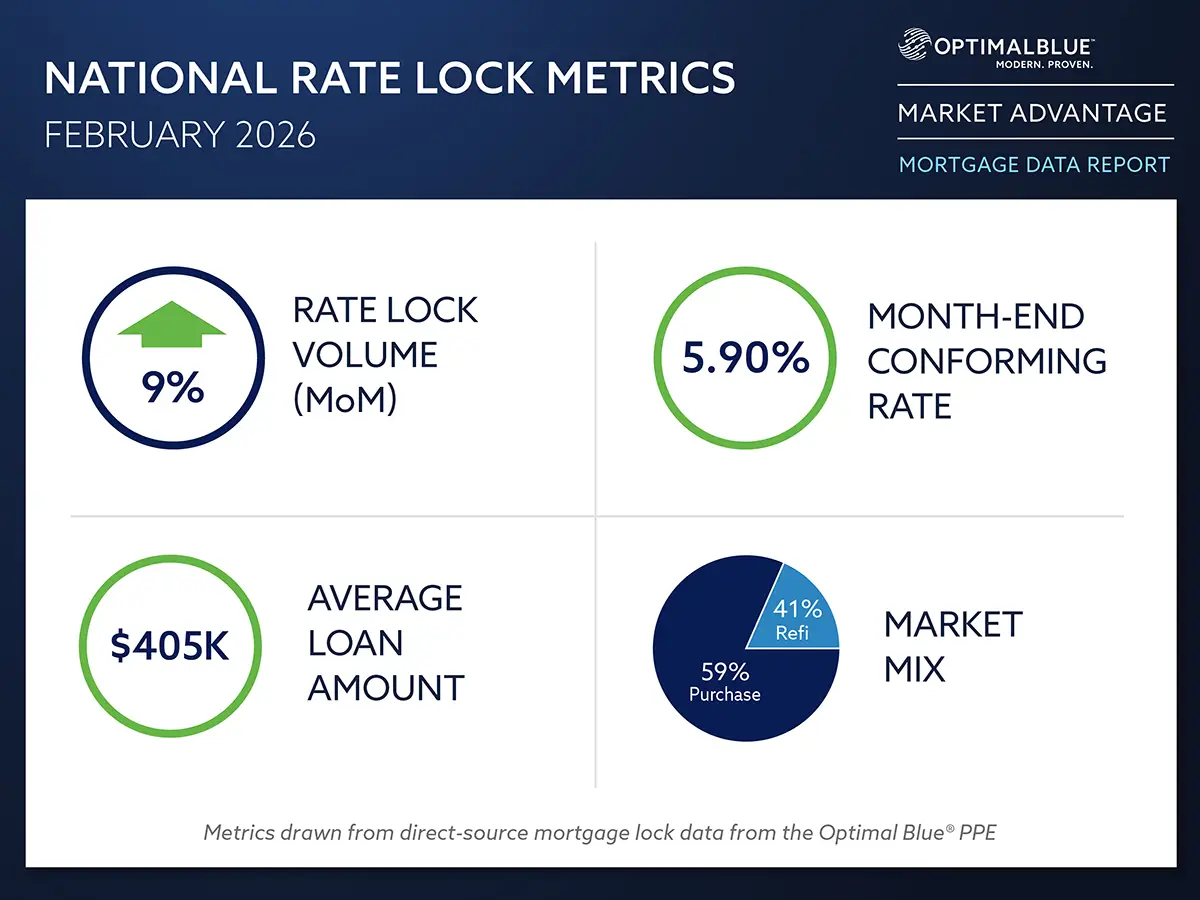
PLANO, Texas, March 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its February 2026 Market Advantage mortgage data report, showing a meaningful improvement in lock activity as lower mortgage rates helped bring purchase borrowers back into the market. Total rate-lock volume rose 9% month over month (MoM) and was nearly 40% higher year over year (YoY). Purchase lock volume increased more than 14% from January and 5% compared with February 2025, driving refinance share down to 41% of locks from 44% in January. Rate-and-term and cash-out refinance activity edged modestly higher from January but remained sharply stronger YoY.

Optimal Blue’s February 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

Mortgage rates declined across all major products in February. The OBMMI 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month at 5.90%, down 17 basis points (bps) from January. Jumbo and VA rates each declined 11 bps during the month, while FHA rates fell 13 bps. The 10-year Treasury yield closed the month at 3.97%, down nearly 30 bps, and the spread between the 10-year Treasury and the OBMMI 30-year rate widened to 193 bps as the mortgage rally lagged the broader bond market.

“February’s data shows the market settling into a healthier balance between purchase and refinance activity as rates moved lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Purchase demand is back after a slow start to the year, but refinance share is still running at 41%, which is higher than anything we saw between early 2022 and late last year.”

Secondary market data in February pointed to shifting execution dynamics as pricing spreads widened and delivery strategies evolved. Best-efforts-to-mandatory spreads widened for conventional products while hedged loan sales moved toward the agency cash window. At the same time, agency mortgage-backed securities (MBS) securitization declined and mortgage servicing rights (MSR) values increased despite falling benchmark rates.

“In an environment like this, lenders are paying close attention to how they execute and manage risk,” said Vough. “We’re seeing more active positioning across delivery channels and servicing assets as lenders balance near-term pricing with longer-term portfolio value.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance activity remains strong: Refinances accounted for 41% of total lock volume in February, down from 44% in January, as purchase demand rebounded. Rate-and-term refinance locks increased 3% MoM and 280% YoY, while cash-out refinance volume rose 1% MoM and 34% YoY.
  • Purchase demand rebounds: Purchase lock volume rose 14% MoM and 5% YoY, marking a meaningful improvement from January’s slower start to the year and helping restore a more balanced mix between purchase and refinance activity.
  • Non-conforming share expands: Conforming loans represented 53% of total lock volume in February, down 28 bps MoM but up 62 bps YoY. Non-conforming share increased to 16%, rising 91 bps MoM and 90 bps YoY. FHA loans accounted for 17% of locks, VA loans for 13% and USDA loans for 1%.
  • ARM utilization rises: Adjustable-rate mortgages comprised 10% of total lock volume in February, up 111 bps MoM and 337 bps YoY from 6.9% last year.

Rates and pricing

  • Rates move lower: The OBMMI 30-year conforming fixed rate declined 17 bps to 5.90%. Jumbo and VA rates each fell 11 bps, while FHA rates declined 13 bps. The 10-year Treasury yield declined nearly 30 bps to 3.97%, while the mortgage-to-Treasury spread widened to 193 bps.
  • MSR values increase: Mortgage servicing rights for conforming 30-year loans rose 2 bps to 1.18%, representing a 4.74 multiple, even as benchmark mortgage rates declined during the month.
  • Spreads adjust across products: Best-efforts-to-mandatory spreads widened for conventional products, with the conforming 30-year spread increasing 3 bps and the conventional 15-year spread rising 1 bp. The government 30-year spread decreased 5 bps.
  • Loan pricing mix shifts slightly: The share of loans sold at the highest price tier declined 100 bps to 78%, while second-tier executions increased 100 bps to 13%.

Channel and execution

  • Securitization share pulls back: Agency MBS securitizations accounted for 42% of hedged executions in February, down from 47% in January.
  • Cash window share jumps: Hedged loan sales to the agency cash window rose 500 bps MoM to 29%, the largest share of cash window deliveries since February 2025.

Product mix and borrower profiles

  • Credit profiles diverge: Purchase FICO scores averaged 734 in February, down 1 point MoM and 3 points YoY. Refinance credit profiles strengthened, with cash-out scores averaging 705 (up 1 point MoM and 10 points YoY) and rate-and-term scores averaging 749 (up 2 points MoM and 18 points YoY).
  • Loan amounts climb: The national average loan amount increased from $400,667 in January to $404,586 in February, marking the first time the average has remained above $400,000 for consecutive months. The national average loan-to-value ratio was 80.32%. Loan amounts ranged from $875,787 in the San Francisco Bay area to $319,743 in San Antonio, with regional LTVs spanning from 68.45% in the Bay area to 89.38% in San Antonio.

To view the full February 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0310-s2p-opblufeb26mk-300dpi.webp

Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-demand-rebounds-as-mortgage-market-finds-balance/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133788 NOREL-3B


Optimal Blue to host 2027 Summit February 1-3 in Scottsdale

Third annual event will return to Arizona for three days of capital markets strategy and innovation

PLANO, Texas, Feb. 25, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced it will host its 2027 Optimal Blue Summit February 1–3 at the JW Marriott Desert Ridge Resort & Spa in Scottsdale, Arizona. The annual event convenes Optimal Blue clients, integration partners and capital markets leaders from across the mortgage industry for three days of insight, collaboration and forward-looking strategy.

Optimal Blue
Image caption: Optimal Blue.

Entering its third year, the Optimal Blue Summit has become a forum for mortgage capital markets professionals to explore technology innovation, share best practices and engage in candid discussion about the market dynamics shaping the industry. The 2027 agenda will continue that focus with expert-led sessions, hands-on training and curated networking designed to equip attendees with practical strategies they can apply within their organizations.

“Our Summit is where strategy and execution come together,” said Sara Holtz, chief marketing officer at Optimal Blue. “Each year, we create an environment where clients and partners can engage directly with our leadership team, explore new platform capabilities and exchange ideas with peers facing similar market challenges. We look forward to building on this year’s momentum as we return to Arizona in 2027.”

Event highlights will include:

  • New technology unveilings: Early access to Optimal Blue’s latest platform advancements, including AI-driven capabilities, automation enhancements and expanded integrations
  • Market intelligence and economic insights: Expert perspectives on secondary market dynamics, rate trends and capital markets strategy
  • Execution and performance workshops: Tactical sessions focused on pricing accuracy, margin management, hedging and operational efficiency
  • Executive leadership forums: Discussions centered on navigating volatility and positioning for sustainable growth
  • Interactive feedback sessions: Client roundtables and product forums designed to shape the future direction of the Optimal Blue platform

Registration for the 2027 event is now open at Summit.OptimalBlue.com. Early bird pricing is available for a limited time.

Additional event details will be announced in the coming months.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-to-host-2027-summit-february-1-3-in-scottsdale/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133459 NOREL-3B


Industry-first AI/ML-powered forecasting tool headlines extensive lineup of mortgage capital markets innovations unveiled at 2026 Optimal Blue Summit

On-demand Virtual Economist anchors nine advancements that unify the capital markets profitability experience across the loan life cycle

PLANO, Texas, Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced Virtual Economist, the first on-demand forecasting tool for mortgage capital markets leaders powered by artificial intelligence and machine learning (AI/ML), as the centerpiece of nine platform advancements unveiled at the company’s 2026 Summit. Together, the innovations further unify the capital markets profitability experience by connecting forecasting, pricing, hedging, competitive benchmarking and workflow execution within a single, end-to-end platform.

Optimal Blue
Image caption: Optimal Blue.

“The future of mortgage capital markets belongs to platforms that don’t just respond to volatility, but anticipate it,” said Joe Tyrrell, CEO at Optimal Blue. “Optimal Blue is building and continuously innovating an intelligent, connected and comprehensive ecosystem that gives lenders clarity and confidence from origination to secondary marketing, and back again. The innovations announced at our 2026 Optimal Blue Summit reflect our long-term commitment to redefining how the industry plans, prices and performs in any market environment.”

“Virtual Economist was built to address a real challenge our lender clients face – the disconnect between economic insight and day-to-day execution,” said Erin Wester, chief product officer at Optimal Blue. “By uniting public economic indicators with Optimal Blue’s proprietary lock volume data and applying AI/ML-driven forecasting, teams can test assumptions and prepare immediately through conversational and visual scenario modeling. That same data-driven approach extends across our 2026 innovations, creating a tighter feedback loop among pricing, margin management and hedge analytics so decisions are informed by real-time insight and reflected consistently across the platform.”

The 2026 Summit advancements include:

VIRTUAL ECONOMIST

In a market where profitability planning typically depends on static, macro forecasts and manual what-if exercises, Virtual Economist gives lenders on-demand predictions without the lag, labor or subjectivity of traditional approaches. The mortgage industry’s first and only AI/ML-powered forecasting tool, it combines public economic data with Optimal Blue’s lock volume data into proprietary machine learning models to deliver real-time rate and volume predictions and instant scenario analysis for strategic planning. Users can choose their preferred economist avatar and engage conversationally through voice or text, with forecasts presented visually to enhance clarity and decision-making.

PROFITABILITY CENTER

Profitability Center introduces a unified dashboard across Optimal Blue products, enabling faster navigation while surfacing cross-product market, production and profitability insights that inform decision-making before users move into deeper workflows. This central landing experience includes access to an economic calendar and predictive insights to anticipate market movement and plan hedging or pricing actions accordingly.

COMPETITIVE DATA LICENSE PLUS

Competitive Data License Plus expands Optimal Blue’s benchmarking capabilities by adding anonymized hedging and trading data to its existing lock and pricing dataset. By connecting front-end pricing behavior with back-end loan sale outcomes updated daily, it delivers deeper visibility into pull-through performance, margin from lock to sale, investor turn times and best-efforts versus mandatory execution spreads. The enhanced dataset enables lenders to model competitive positioning and execution strategy with greater precision across the capital markets life cycle.

AGENCY DIRECT (for CompassEdge)

Agency Direct in CompassEdge modernizes retained execution workflows for institutions delivering loans to Fannie Mae, Freddie Mac and the Federal Home Loan Bank system. By replacing manual spreadsheet-based tracking with a centralized environment for loan imports, coverage modeling and commitment management in CompassEdge, the solution strengthens executive visibility while reducing operational risk.

RATESHEET PRICING INSIGHTS (for CompassEdge)

Ratesheet Pricing Insights connects pricing from the Optimal Blue PPE with CompassEdge margin management, reducing the lag and manual processes that can separate pricing decisions from published rates. By syncing margin updates directly between systems and embedding market and competitive context into the workflow, it surfaces competitive insights before ratesheets are published and helps ensure rates reflect current conditions while improving margin discipline.

HEDGE COST IN THE PPE (for the Optimal Blue PPE)

Hedge Cost in the PPE embeds CompassEdge hedge analytics directly within the Optimal Blue PPE, giving lenders immediate visibility into the margin impact of extensions, renegotiations and price concessions. By surfacing hedge coupon, mark-to-market exposure and effective margin at the point of decision, it strengthens alignment between origination and secondary teams while protecting execution performance at the transaction level.

AI RULES ASSISTANT (for the Optimal Blue PPE)

AI Rules Assistant enhances Rules Optimizer, a feature within the Optimal Blue PPE that manages pricing and eligibility rules across investor relationships, by enabling administrators to “speak policy, ship rules” – i.e., input natural language and allow AI automation to generate the new rule. It identifies similar configurations and automatically builds required dependencies for review, accelerating rule creation while strengthening governance and pricing control.

ENHANCED ADMIN EXPERIENCE (for the Optimal Blue PPE and CompassEdge)

Enhanced admin experiences in both the Optimal Blue PPE and CompassEdge hedging and trading platform arm administrators with faster, more intuitive ways to configure pricing and manage investors.

In the Optimal Blue PPE, a redesigned configuration experience consolidates key tools into a straightforward, user-friendly workspace, with embedded entity selection and global Release to Production access from any screen. By reducing clicks and improving visibility across pricing configurations, it accelerates setup and governance workflows for administrators.

In CompassEdge, new administrative configuration for investor management gives users more straightforward visibility into the configuration for valuing their loan pipeline. Users can self-manage investors, execution types and more in a single, accessible place.

LOANSIFTER–COMERGENCE CONNECTION

A new connection between Optimal Blue’s Loansifter PPE for mortgage brokers and its Comergence counterparty oversight solution links promotional pricing visibility with counterparty engagement data, giving investors measurable insight into broker interaction and marketing effectiveness. By connecting broker activity with onboarding and approval workflows, the integration enables investors to capture qualified leads and accelerate TPO network growth.

Several of the announced innovations are live today, with others entering beta or phased rollout throughout 2026.

Optimal Blue’s annual Summit brings together lenders, investors and industry leaders to explore the strategies and technologies shaping the future of mortgage capital markets.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/industry-first-ai-ml-powered-forecasting-tool-headlines-extensive-lineup-of-mortgage-capital-markets-innovations-unveiled-at-2026-optimal-blue-summit/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133391 NOREL-3B
 

Optimal Blue report: Sub-6% rates spark refinance surge early in 2026

​​Refinances jump as execution strategies and investor demand shift

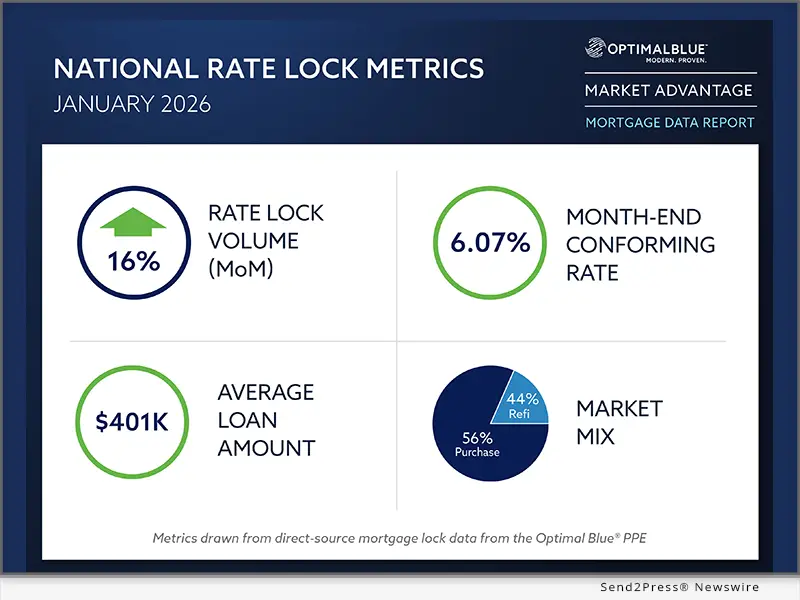
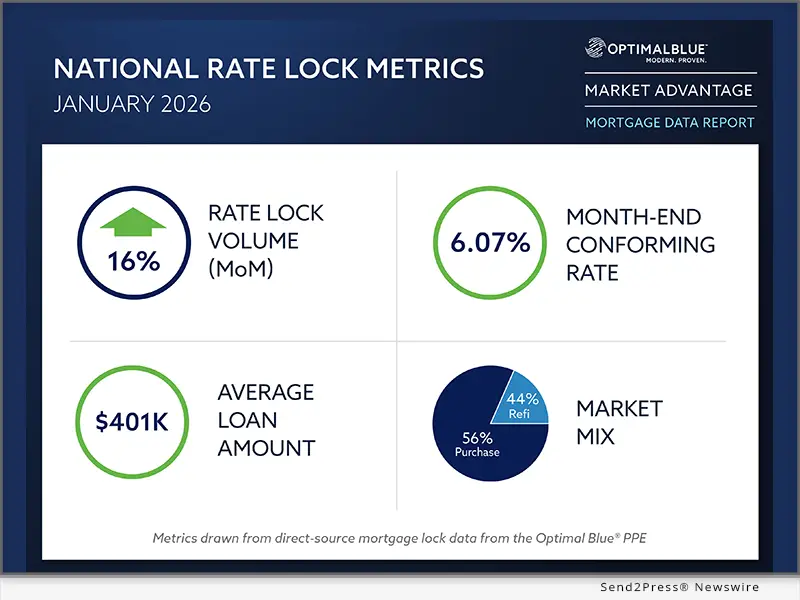
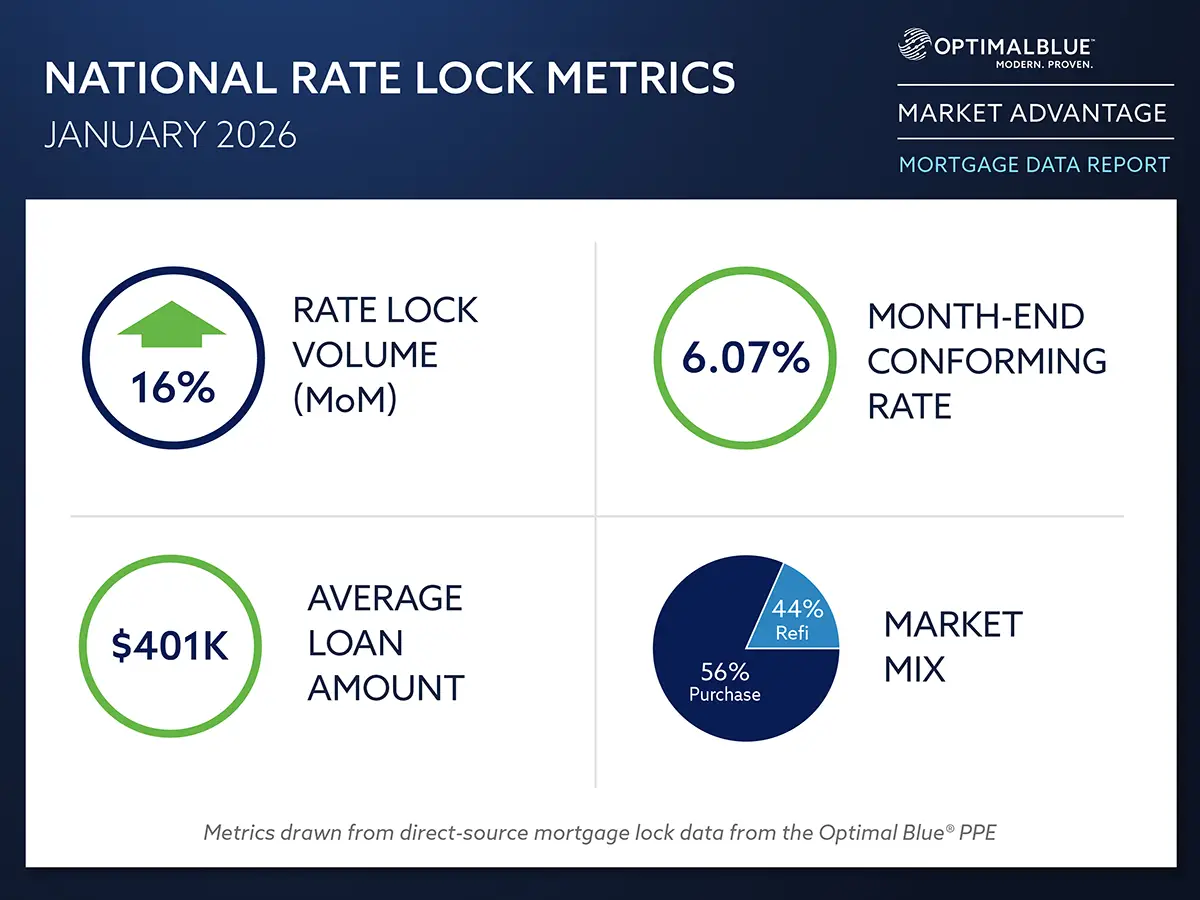
PLANO, Texas, Feb. 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its January 2026 Market Advantage mortgage data report, showing a strong start to the year as falling rates drove a sharp increase in refinance activity. Total rate-lock volume rose 16% month over month (MoM) and finished January 36% higher year over year (YoY), led by a surge in rate-and-term refinances, which climbed 50% from December and more than 400% compared with January 2025. Cash-out refinance activity also increased, rising 11% MoM and 38% YoY. Purchase volume grew a modest 3% from December but remained down 5% from a year earlier, reflecting the slower response of purchase demand to changing rate conditions early in the year.

Optimal Blue’s January 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

Mortgage rates moved lower across most products in January. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, declined 7 basis points (bps) to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely unchanged at 5.99%. The average locked rate on the Optimal Blue PPE fell below 6% for the first time since August 2022.

“January’s data shows just how quickly refinance demand can respond when rates move lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “It’s been more than three years since the market last saw average rates with a ‘5 handle,’ and crossing back below that level appears to have released meaningful pent-up refinance demand. Purchase activity is responding more gradually, which is typical this early in the year, but the shift in borrower behavior is clear.”

On the secondary side, lenders adjusted execution strategies as pricing dynamics shifted and investor demand strengthened. Best-efforts-to-mandatory spreads increased for 30-year products, securitization activity increased and mortgage servicing rights (MSR) values rose despite declining benchmark rates, signaling a continued focus on balance sheet positioning and longer-term value.

“January’s secondary market data reflects lenders positioning early for a potentially more active origination environment,” said Vough. “Pricing trends were increasingly tied to eligibility rather than outright price give-ups, and agency MBS securitization reached its largest share since 2024. Meanwhile, rising MSR values and expanding investor participation point to a market focused on flexibility and long-term execution strategy as 2026 begins.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

VOLUME TRENDS AND MARKET COMPOSITION

  • Sharp pickup in refis: Refinance activity surged in January as falling rates quickly translated into borrower demand. Rate-and-term refinance locks increased 50% MoM and were more than four times higher YoY. Cash-out refinances also gained momentum, rising 11% MoM and 38% YoY.
  • Purchase activity lags: Purchase volume increased a modest 3% MoM but remained down 5% YoY. The slower response reflects the typical lag in purchase demand relative to rate movements, particularly early in the year.
  • Non-QM share pulls back: Non-qualified mortgage share declined to 8% in January, down 160 bps from December but 70 bps higher YoY.
  • VA gains momentum: VA lending captured a larger share of January activity as borrowers moved quickly to take advantage of lower rates, positioning VA portfolios for increased refinance-related payoffs as those loans move through the pipeline. VA loans accounted for 14% of locks, up 125 bps MoM and 212 bps YoY.
  • PUD share retreats: Planned unit developments (PUDs) accounted for 28% of locks in January, down 95 bps MoM and 651 bps YoY.

RATES AND PRICING

  • Rates edge down: Mortgage rates moved lower across most products in January. OBMMI for the 30-year conforming fixed rate declined 7 bps to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely flat at 5.99%.
  • MSR values tick higher: MSR values for conforming 30-year loans increased 2 bps to 1.16%, representing a 4.65 multiple, diverging from declining benchmark rates.
  • Spreads widen on rate moves: Best-efforts-to-mandatory spreads increased for 30-year products in January, with the conforming 30-year spread widening 3 bps and the government 30-year spread increasing 8 bps. The conforming 15-year spread narrowed by 8 bps during the month.
  • Pricing discipline persists: The share of loans sold at the highest price tier remained flat at 79%, while second-tier executions increased 200 bps to 13%, reflecting continued use of eligibility-based delivery strategies with less price concession.

CHANNEL AND EXECUTION

  • Execution mix tilts to securitization: Lenders shifted hedged execution toward agency MBS in January, with securitization share increasing 300 bps MoM to 47%, the largest share since 2024.
  • Aggregator and cash executions ease: Loan sales to bulk aggregators declined 100 bps MoM, while cash window executions also decreased 100 bps during the month.
  • Investor participation continues to expand: The number of active investors increased to 14 in January, extending the expansion in investor participation that began late last year.

PRODUCT MIX AND BORROWER PROFILES

  • Credit quality improves: Average credit scores increased for both cash-out refis (up 2 points) and rate-and-term refis (up 5 points). Credit scores also rose across all major products, including conforming (up 1 point), FHA (up 1 point) and VA (up 4 points) loans.
  • Affordability metrics improve: Purchase debt-to-income (DTI) ratios declined across all loan types in January and fell 1 to 2 percentage points YoY. The share of first-time homebuyers also increased, rising to 45% of conforming loans and 70% of FHA loans.
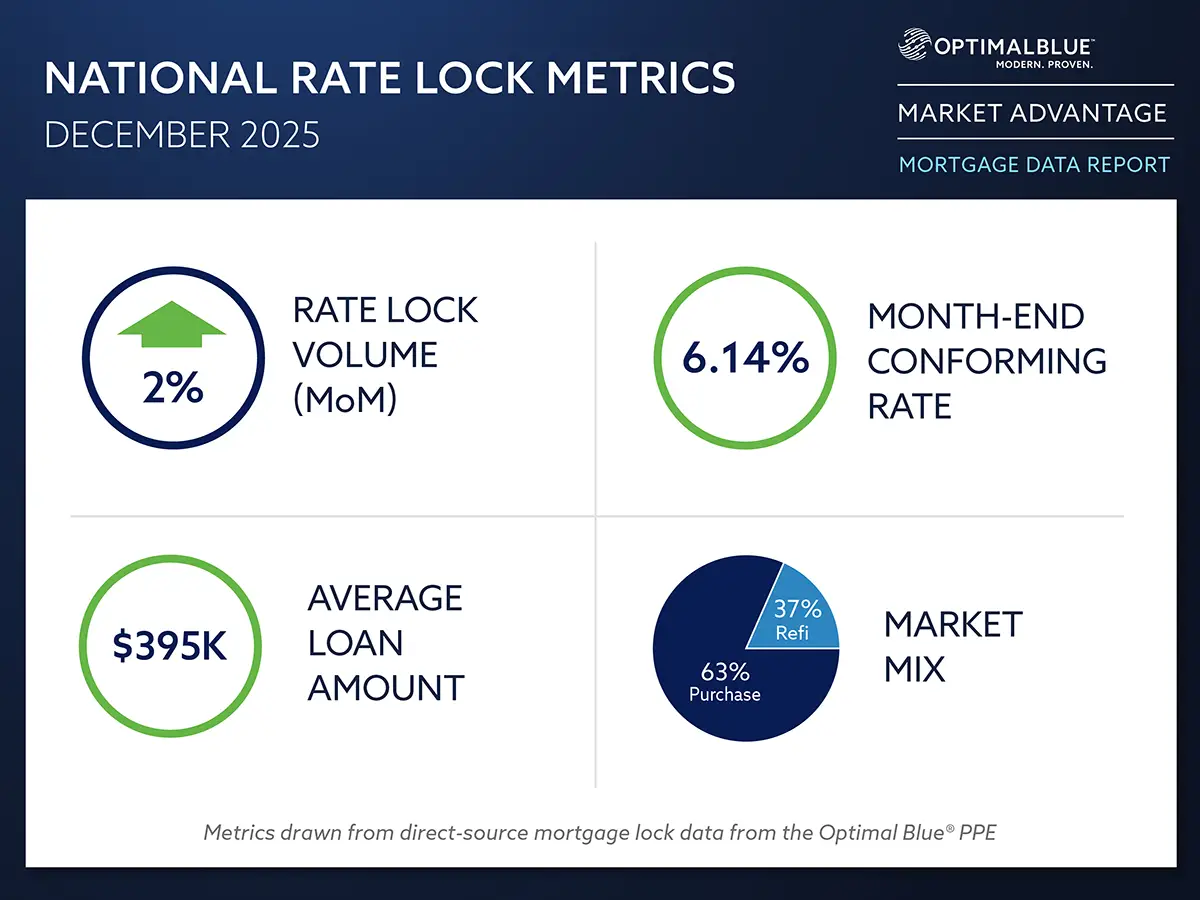
  • Loan amounts edge up: The average loan amount increased from $394,502 in December to $400,667. January loan amounts ranged from $868,498 in greater San Francisco to $316,638 in San Antonio. Loan-to-value ratios ranged from 70.21% in greater Los Angeles to 88.44% in San Antonio, with a national average of 80.06%.

To view the full January 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Inage link for media: https://www.Send2Press.com/300dpi/26-0210-s2p-opblue-300dpi.webp

Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-sub-6-rates-spark-refinance-surge-early-in-2026/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132992 NOREL-3B
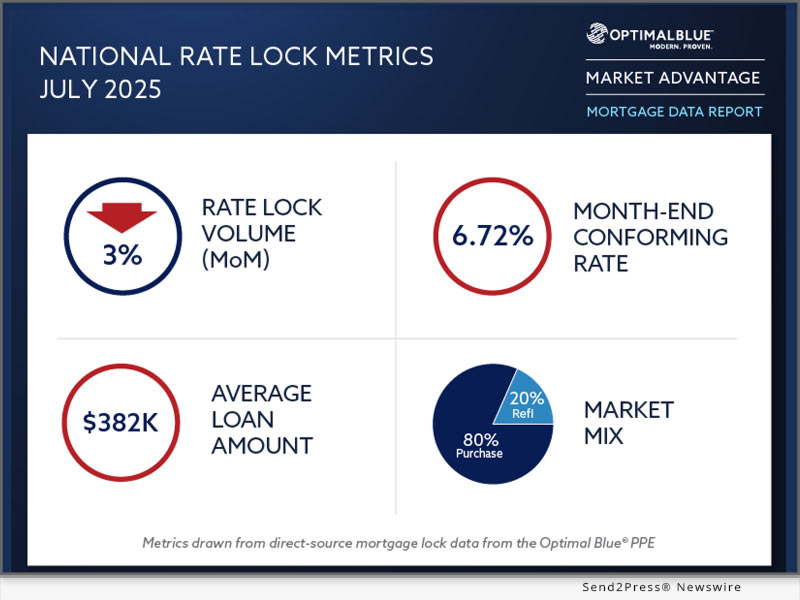
 

Optimal Blue report: December lock volume closes 2025 on a firm footing

Refinance momentum drives year-end activity despite holiday headwinds

PLANO, Texas, Jan. 13, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its December 2025 Market Advantage mortgage data report, showing that mortgage rate-lock activity ended the year on a firm footing, bucking typical holiday-driven seasonality. Total lock volume rose 2% month over month (MoM) from November and finished 30% higher year over year (YoY), driven primarily by rate-and-term refinances, which climbed 13% from November and more than 170% compared with December 2024. Cash-out refinance volume rose a modest 1% MoM but remained up a strong 35% YoY. Purchase activity dipped just 1% from November despite holiday headwinds to end December up 7% YoY.

Optimal Blue's December 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report.

Mortgage rates were largely stable in December. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month flat at 6.14%. Meanwhile, the 10-year Treasury yield rose 14 basis points (bps) to 4.14%, reversing November’s spread widening and pushing the 10-year-to-OBMMI spread to 200 bps at year-end.

“Finishing the year with higher lock volume in December is a clear signal that borrower demand has adjusted to today’s rate environment,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Refinance activity continues to do the heavy lifting, but the fact that purchase volume held essentially flat month over month and finished the year higher than last December speaks to a market that is more durable than many expected.”

Lenders also made notable adjustments on the secondary side as pricing dynamics and execution strategies evolved. Best-efforts-to-mandatory spreads widened across products, bulk aggregator execution regained share, and mortgage servicing rights (MSR) values increased despite flat primary rates.

“December’s secondary data shows lenders actively recalibrating execution as spreads widened and pricing discipline remained tight,” Vough said. “The shift back toward bulk aggregation, combined with stable top-tier pricing and rising MSR values, reflects investor demand that is focused on end-of-year balance sheet management and long-term value as we head into 2026.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance share expands: Refinances accounted for 37% of all locks in December, up 224 bps MoM and 1,354 bps YoY. Rate-and-term refinance volume increased 13% MoM and more than 170% YoY, while cash-out refinances rose 1% MoM and 35% YoY. Overall refinance pull-through improved 194 bps from November to 69.2%.
  • Purchase market remains resilient: Purchase locks slipped just 1% MoM despite typical holiday-driven seasonality and finished December 7% higher than a year earlier. Pull-through for purchase loans increased 199 bps MoM to 85.7%.
  • Non-QM sets another record: Non-qualified mortgage production maintained its upward trajectory, finishing December above 9% of locks, up 50 bps MoM.
  • Government and non-conforming gain share: Conforming loans accounted for 51% of locks in December, down 86 bps MoM and 18 bps YoY. Non-conforming share rose to 17%, up 17 bps MoM and 141 bps YoY. FHA, VA and USDA loans each gained share during the month.
  • PUD share remains sizable: Planned unit developments (PUDs) accounted for 29% of locks by property type, up 123 bps MoM but below year-ago levels, when PUD share was higher.

Rates and pricing

  • Rates largely unchanged: The OBMMI 30-year conforming fixed rate ended December flat at 6.14%. FHA rates declined 1 bp to 5.98%, VA rates fell 6 bps to 5.71% and jumbo rates dropped 3 bps to 6.41%.
  • MSR values move higher: MSR values for conforming 30-year loans increased 5 bps to 1.14%, representing a 4.57 multiple, rising despite largely stable primary rates.
  • Treasury yields rise as spreads widen: The 10-year Treasury yield increased 14 bps to 4.14% in December, compressing the mortgage–Treasury spread to 200 bps. Best-efforts-to-mandatory spreads widened across products, including a 2-bp increase for conforming 30-year loans and a 3-bp increase for government 30-year loans.
  • Top-tier pricing holds: The share of loans sold at the highest price tier remained flat at 79%, while second-tier share was unchanged at 11%, reflecting continued pricing discipline across the market.

Channel and execution

  • Execution mix shifts back toward aggregators: Lenders adjusted hedged execution strategies in December as bulk aggregators regained share at the expense of agency securitization and cash window channels.
  • Bulk aggregator share rebounds: Hedged loan sales to bulk aggregators increased 200 bps MoM to 29%, reversing a multi-month decline.
  • Securitization and cash window ease: Agency mortgage-backed securities (MBS) executions and cash window sales each declined 100 bps during the month.
  • Investor participation increases: The number of active investors rose to 12 in December after holding steady at 11 for four consecutive months, modestly expanding execution options for lenders.

Product mix and borrower profiles

  • Credit scores edge lower: The average borrower credit score declined to 732 in December from 733 in November, extending a gradual pullback from 746 in September.
  • Loan sizes rise as leverage varies by market: The average loan amount increased to $394,502 from $391,323 in November. Loan sizes ranged from $812,240 in Los Angeles to $315,735 in San Antonio. Loan-to-value ratios ranged from 68.85% in the San Francisco–Oakland Bay Area to 87.69% in San Antonio, with a national average of 80.10%.

To view the full December 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/26-0113-s2p-opbluedec25-300dpi.webp

Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-december-lock-volume-closes-2025-on-a-firm-footing/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132225 NOREL-3B


Optimal Blue report: Lock volume posts strongest November since 2021

Resilient refinance demand driven by current rates tempers the effects of seasonal slowdown

PLANO, Texas, Dec. 10, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its November 2025 Market Advantage mortgage data report, which found that total mortgage rate-lock activity declined with normal late fall seasonality, yet still marked the strongest November in four years. Total lock volume fell 25% month over month (MoM) from October but remained up 17% year over year (YoY), buoyed by historically strong refinance demand and mortgage rates holding near 6%. Rate-and-term refinances continued to outperform 2024 levels by a wide margin, finishing November up 223% YoY despite easing from September’s high. Cash-out refinances rose 29% YoY. Purchase lock activity declined 22% MoM in line with seasonal patterns and slipped 6% YoY as elevated home costs and limited inventory continued to restrain demand.

Optimal Blue's November 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s November 2025 Market Advantage mortgage data report.

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, dipped 1 basis point to 6.14% in November, marking a 53-bps improvement from the same period in 2024. FHA rates fell 5 bps to 5.99%, while VA and jumbo rates rose modestly to 5.76% (up 9 bps) and 6.44% (up 8 bps), respectively. The 10-year Treasury yield fell 11 bps to 4%, widening the mortgage rate spread by roughly 10 bps as OBMMI remained essentially flat.

“November’s data underscores a market still responding to rate relief even as seasonal patterns take hold,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Refinances remain the clear standout, with rate-and-term activity running more than triple last year’s levels and cash-outs continuing to outperform. It was a notably strong November by any measure.”

Lenders adjusted execution strategies in November as agency cash window sales rose 300 bps to 25%, interrupting the recent move toward greater securitization. Agency mortgage-backed securities (MBS) deliveries declined 100 bps to 45% after six consecutive months of gains, while bulk aggregator share dropped 300 bps to 27% and best-efforts executions increased 100 bps to 3%. The share of loans sold at the highest price tier fell 200 bps to 79%, while second- and fourth-tier deliveries increased. Mortgage servicing rights (MSRs) for conforming 30-year loans decreased 3 bps to 1.09% (a 4.36 multiple), in line with an average 15 bps decline across other OBMMI rate series.

“Execution strategies shifted meaningfully in November,” said Vough. “Lenders moved to the cash window as securitization momentum moderated, and pricing spreads broadened as more loans moved out of the top tier. These shifts point to lenders fine-tuning execution to manage price and overall delivery profile as the market settles into late-year conditions.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refis remain a major driver: Refinances accounted for 35% of all locks. Rate-and-term refinances rose 223% YoY despite slowing from early fall peaks, while cash-out refinances increased 29% YoY.
  • Purchases decline: Purchase locks fell 22% MoM and 6% YoY as elevated home costs and limited listings continued to weigh on demand.
  • Non-QM sets new record: Non-qualified mortgage share rose to 9%, the highest level recorded by Optimal Blue, with investor/debt-service-coverage-ratio (DSCR) programs accounting for a growing share of non-QM production.
  • FHA, non-conforming pick up share: Product mix shifted toward FHA and non-conforming loans (including jumbo) at the expense of conforming and VA lending, supported in part by 5.99% FHA rates.
  • PUD share ticks up slightly: Planned unit development (PUD) lock share, a reasonable proxy for new construction, rose relative to other property types but remained well below last year’s unusually high levels.

Rates and pricing

  • Rates stabilize near 6%: The OBMMI 30-year conforming fixed rate ticked down 1 bp to 6.14%. FHA fell to 5.99%, while VA and jumbo rates rose to 5.76% and 6.44%, respectively.
  • MSR values dip: MSRs for conforming 30-year loans fell 3 bps to 1.09% (a 4.36 multiple), moving in line with rate declines.
  • Spread widens to 10-year Treasury: The 10-year Treasury yield fell 11 bps to 4%, widening the mortgage rate spread by roughly 10 bps as OBMMI remained mostly unchanged.
  • Pricing tiers show more dispersion: The share of loans sold at the highest price tier dropped 200 bps to 79%, while second- and fourth-tier shares rose.

Channel and execution

  • Cash window share increases: Cash window deliveries increased to 25% (up 300 bps) as lenders shifted execution away from aggregator and securitization outlets in November.
  • MBS share pulls back: Agency MBS sales fell to 45% (down 100 bps) after six consecutive months of increases.
  • Aggregator share declines: Bulk aggregator executions dropped to 27% (down 300 bps), while best-efforts executions rose to 3% (up 100 bps).

Product mix and borrower profiles

  • Lower-rate programs gain traction: Lenders saw greater uptake in products benefiting from improved pricing, including increased FHA share at 18.8% (up 104 bps) and steady demand for jumbo and other non-conforming offerings at 17% (up 34 bps).
  • S. buyer share rises: U.S. citizens accounted for nearly 94% of locks, extending a multi-month upward trend.
  • Credit scores and loan sizes edge lower: The average credit score fell one point to 733. The average loan amount decreased to $391,323 from October’s $397,438. November loan averages ranged from $592,129 in metro New York to $295,526 in Indianapolis. Average loan-to-value ratios ranged from 69.79% in Los Angeles to 88.22% in San Antonio.

To view the full November 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/25-1210-s2p-opbluenov-300dpi.webp

Image caption: Optimal Blue’s November 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-lock-volume-posts-strongest-november-since-2021/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131605 NOREL-3B


Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer

Promotions elevate two longtime leaders into roles that deepen financial stewardship and strengthen revenue alignment as the company scales

PLANO, Texas, Dec. 8, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced the promotion of Lanny Rogers III, CPA, to chief financial officer (CFO) and Jeremy Moreno to chief revenue officer (CRO). Their combined experience and long track records of leadership position the company to advance its next stage of growth and client success with a dedicated financial strategy function and strengthened revenue oversight.

Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer
Image caption: Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer.

Rogers’ promotion to CFO reflects the company’s continued growth and investment in financial strategy as the business expands. As CFO, he will guide financial planning, forecasting, capital allocation and financial diligence on acquisitions, helping ensure the company grows with the discipline, visibility and long-term thinking required of a market leader.

“As we have continued to experience exponential growth and expansion, Lanny has been central to strengthening the financial nimbleness of our business,” said Joe Tyrrell, CEO of Optimal Blue. “He brings clarity to complex decisions, balances discipline with pragmatism and understands the financial considerations that shape every part of our operations. He has already been helping steer our financial direction, and this role formalizes his leadership as we continue to scale responsibly to continue bringing new innovation and value to our clients.”

Rogers first joined Optimal Blue in 2017 as an accounting manager and advanced to division controller in 2022 before being promoted to vice president of accounting in 2023 – his most recent role. A certified public accountant with deep expertise in financial operations, forecasting and organizational governance, he brings a collaborative approach and a steady, practical perspective to financial leadership across the company.

As CRO, Moreno will lead the company’s unified revenue and client retention function, with a focus on aligning ongoing client success, client acquisition and long-term relationship growth. His leadership brings greater cohesion across the client lifecycle and prepares Optimal Blue to respond to shifting market dynamics with agility and clarity.

“Optimal Blue had a record year in 2025 for both adding new clients and expanding relationships with our existing clients. As we continue to prioritize our current and future clients’ success across all aspects of our business, Jeremy’s leadership in the CRO function creates a unified team dedicated to this essential function,” said Tyrrell. “Jeremy has a track record of focusing on the needs of our clients and driving predictable, long-term growth for Optimal Blue, and he is the right leader to further align our strategies around client retention.”

Moreno has been part of Optimal Blue for more than a decade, most recently serving as vice president of sales, where he led acquisition strategies and supported relationship growth initiatives for lenders and partners nationwide. His experience spans operations, client services, training and retention, giving him deep insight into how customers use the company’s platform and where they need support as markets evolve.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-names-lanny-rogers-chief-financial-officer-and-jeremy-moreno-chief-revenue-officer/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131566 NOREL-3B
 

Optimal Blue report: October lock volume holds second-highest level in three years

Seasonal cooling offset by resilient refinance demand and rising agency MBS executions

PLANO, Texas, Nov. 11, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its October 2025 Market Advantage mortgage data report, showing that rate-lock activity remained strong despite seasonal cooling and continued to outpace last year’s levels. Total lock volume fell 4.2% month over month (MoM) from September’s peak but was still up 18% year over year (YoY) as borrowers responded to improving affordability and narrower rate spreads.

Optimal Blue's October 2025 Market Advantage mortgage data report.
Image caption: Optimal Blue’s October 2025 Market Advantage mortgage data report.

Purchase locks declined just 1.5% in October, in line with typical seasonal patterns, while refinance lending remained a key driver of activity. Rate-and-term refinances fell 14% from September but stayed up 143% YoY, and cash-out refinances rose 6% MoM and 29% YoY.

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate – the benchmark for CME Group’s Mortgage Rate futures – dropped another 16 basis points (bps) to 6.16%, marking its lowest level since late 2023.

“October’s data speaks to the market’s resilience,” said Mike Vough, head of corporate strategy at Optimal Blue. “Purchase activity held steady and refinance demand – particularly cash-outs – remained strong. Even after September’s record pace, October delivered another standout month for originations.”

Lenders continued to strengthen execution strategies in the secondary market during October. Sales to agency mortgage-backed securities (MBS) climbed 400 bps to 46%, extending a multi-month trend of large-lender securitization growth. Deliveries to the agency cash window fell 200 bps to 30%, while aggregator bulk and best-efforts channels each dipped 100 bps. The share of loans sold at the highest price tier rose to 81%, up 300 bps, underscoring lenders’ ability to capture premium pricing even as servicing values tightened. Mortgage servicing rights (MSRs) for conforming 30-year loans increased 3 bps to 1.12% (a 4.47 multiple), moving in line with an average 6-bps gain across OBMMI rates for the month.

“October’s secondary market data reflected clear strength in execution,” said Vough. “Lenders leaned further into MBS sales and maintained access to top-tier pricing, signaling disciplined hedging and growing investor confidence. With securitization share and pricing quality both on the rise, large lenders appear well positioned to sustain profitability as production remains steady.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

VOLUME TRENDS AND MARKET COMPOSITION

  • Refis stay elevated: Rate-and-term refinances fell 14% MoM but remained up 143% YoY, while cash-outs rose 6% MoM and 29% YoY. Refinance pull-through improved to 71.6%, up 11.4 points from September. Refinances accounted for 37% of all production in October, down 176 bps from September but up 11.4 points YoY.
  • Purchases steady: Purchase locks declined 1.5% aligned to seasonal expectations, remaining strong relative to historical patterns. Purchase pull-through improved to 84.6%, up 91 bps from September.
  • Non-QM share rises: Non-qualified mortgage share edged higher, driven by gains in both investor/debt-service-coverage-ratio (DSCR) and bank statement programs.
  • FHA and conforming gain share: FHA and conforming production increased at the expense of primarily VA lending. VA refinance activity typically reacts fastest to rate reductions, leading to a front-loading of VA locks in September.
  • Single-family share climbs: Single-family production rose relative to all other property types in October, reflecting sustained strength in owner-occupied lending.

RATES AND PRICING

  • Mortgage rates decline: The OBMMI 30-year conforming fixed rate fell 16 bps to 6.16%, with FHA at 6.04%, VA at 5.67% and jumbo at 6.36%.
  • Spread tightens to 10-year: The mortgage rate spread to the 10-year Treasury narrowed 11 bps to just over 200 bps, down 46 bps from 2024 and the tightest since early 2022. The 10-year yield itself fell only 5 bps to 4.11% as the Fed’s recent rate cut was largely priced into the market, indicating that most of the mortgage rate improvement stemmed from spread compression rather than a broader interest rate decline.
  • Lender pricing strengthens: Lenders achieved higher overall pricing levels in October as spreads narrowed and execution improved across delivery channels.
  • Servicing values recover: MSRs for conforming 30-year loans rose 3 bps to 1.12% (a 4.47 multiple).

CHANNEL AND EXECUTION

  • Agency MBS execution expands: Share rose to 46% (+400 bps), while the agency cash window share of execution fell to 30% (–200 bps) and aggregator bulk and best efforts each dipped 100 bps.
  • Investor count steady: The average number of active investors held at 11, reflecting stable liquidity conditions. Historical counts ranged from 8 in November 2024 to 12 in December 2024.
  • Higher-tier pricing dominates: With 81% of loans sold at the highest pricing tier, lenders demonstrated disciplined execution strategies that offset margin pressure from rate compression.

PRODUCT MIX AND BORROWER PROFILES

  • DTIs and affordability flat: Debt-to-income ratios and first-time homebuyer share held steady, signaling sideways affordability movement.
  • Balanced composition: FHA and conforming production growth offset earlier VA surge, keeping overall mix diverse across loan types.
  • Credit profiles, loan amounts dip: The average credit score fell to 734 from 735 MoM. The average loan amount decreased to $397,438 from $403,746. October loan averages ranged from $602,646 in metro New York to $312,177 in Indianapolis. Average loan-to-value (LTV) ratios ranged from 70% in San Francisco to 87% in San Antonio.

To view the full October 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

Access this month’s podcast episode: https://market-advantage.captivate.fm/episode/episode-14.

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/25-1111-s2p-opblueoct-300dpi.webp

Image caption: Optimal Blue’s October 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-october-lock-volume-holds-second-highest-level-in-three-years/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130911 NOREL-3B


Optimal Blue continues to debut new innovations across complete capital markets platform ahead of MBA Annual Convention and Expo

New data product and three platform enhancements deliver increased market transparency, pricing accuracy, counterparty oversight and trading automation

PLANO, Texas, Oct. 16, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced the launch of a new data solution to deliver increased market transparency, as well as three major platform enhancements focused on pricing accuracy, trade execution and counterparty management. Released ahead of the Mortgage Bankers Association (MBA) Annual Convention and Expo, and as the company prepares for its 2026 Optimal Blue Summit, these innovations reinforce Optimal Blue’s commitment to delivering solutions that position lenders to drive operational excellence and boost competitive performance.

Optimal Blue
Image caption: Optimal Blue.

“We continue to deliver on our promise of innovation at Optimal Blue in areas where it stands to have the greatest impact for our clients,” said Joe Tyrrell, CEO of Optimal Blue. “From AI-powered automation to real-time, transparent market insights, Optimal Blue merges a commitment to modern innovation with decades of proven experience and trust. This will be on full display at our 2026 Optimal Blue Summit, where we will be unveiling more innovations that drive the industry forward.”

  • Broker Search Data License
    Broker Search Data License is a new data product that gives wholesale and non-QM investors a previously unavailable view into broker demand across the market. Delivered monthly from Optimal Blue’s Loansifter platform, the data set includes roughly one million rows of anonymized search activity from more than 6,000 brokers, capturing early signals of what programs and loan types are gaining traction before locks occur. Unlike traditional pricing or lock data, Broker Search Data License reveals broker intent at the top of the funnel, helping investors spot emerging trends, evaluate program competitiveness and refine strategy well ahead of market shifts. Because the data is delivered in a raw, analytics-ready format, users can integrate it directly into internal intelligence environments or combine it with Optimal Blue’s Investor Pricing Insight for a complete view of broker engagement and pricing performance.
  • Pipeline Monitoring for the Optimal Blue PPE
    Pipeline Monitoring is a new feature within Optimal Blue’s product, pricing and eligibility (PPE) engine that automates the oversight of pipeline changes affecting pricing or eligibility post-initial lock. Built for seamless loan origination system (LOS) integrations, it continuously tracks loan detail changes throughout the processing and underwriting of the transaction, such as FICO scores, loan amounts and property information, instantly detecting any change that could alter pricing or eligibility rules. Loan officers receive real-time notifications through email while secondary users can manage these events through an interactive work queue, each specifying which rule triggered the alert, ensuring fast and accurate responses without borrower disruption or pricing-related closing delays. The result is greater workflow automation, reduced manual checks and stronger control over pricing and eligibility risk.
  • Competitive Trade Blotter and TBA Trading Integrations for CompassEdge
    The Competitive Trade Blotter and TBA Trading Integrations are new capabilities within CompassEdge, Optimal Blue’s hedging and loan trading solution, that modernize TBA trading by eliminating manual outreach and fragmented workflows. Traders can collect, compare and execute broker-dealer pricing directly within CompassEdge, reducing error rates and accelerating execution. The Competitive Blotter will track broker-dealer performance trends over time, giving lenders deeper visibility into pricing competitiveness. CompassEdge can connect with any broker-dealer or trading platform that supports APIs. Together, these advancements deliver faster, more accurate and more transparent trading that strengthens broker-dealer relationships and reduces operational risk.
  • Integration Studio for Comergence
    A new capability in Comergence, Optimal Blue’s counterparty oversight solution, Integration Studio lets clients connect seamlessly with external tools such as Salesforce through a no-code integration marketplace. Designed for business users rather than developers, it allows integrations to be configured and deployed in under an hour using an intuitive field mapping wizard with built-in validation and de-duplication. Hourly data syncs and integration logs keep information current and auditable, while self-service admin tools give users full control over their connections. Integration Studio offers a done-for-you approach to data integration that enables lenders, investors and partners to maintain accurate, synchronized and compliant records across systems.

“Innovation at Optimal Blue is about delivering meaningful value that addresses real lending challenges and opportunities,” said Erin Wester, chief product officer at Optimal Blue. “From greater pricing intelligence to seamless system integrations, we’re giving lenders and investors the tools they need to accelerate performance and sharpen their competitive edge.”

Wester will demonstrate Ask Obi – Optimal Blue’s AI-powered assistant that made its debut at the company’s 2025 Summit – at MBA Annual during the Tech Showcase that kicks off at 2:30 p.m. Pacific Time on Monday, October 20. Conference attendees can learn more about Optimal Blue’s new innovations by visiting the company’s booth #200 in the HUB Expo.

Optimal Blue Clients are encouraged to register early for the company’s 2026 Summit taking place February 23–25 in Scottsdale, Arizona, to take advantage of early bird pricing. Registration is open at Summit.OptimalBlue.com.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth.

To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA:

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-continues-to-debut-new-innovations-across-complete-capital-markets-platform-ahead-of-mba-annual-convention-and-expo/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130241 NOREL-3B
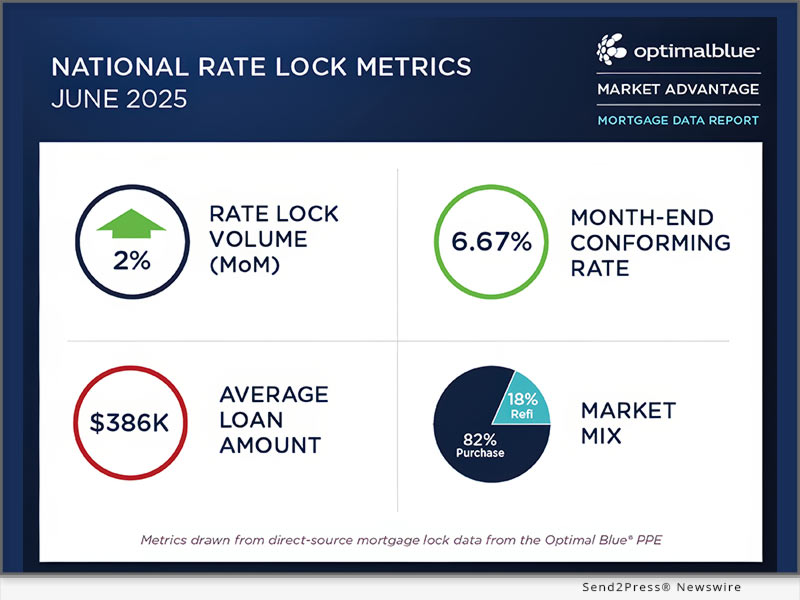
 

Optimal Blue report: Rate rally drives 28% surge in September lock volumes

Affordability gains fuel with biggest refi wave since early 2022, MSR values dip and securitization trends point to rising large-lender market share

PLANO, Texas, Oct. 14, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its September 2025 Market Advantage mortgage data report, which showed a sharp increase in rate-lock activity as mortgage rates fell throughout the month to their lowest levels in nearly a year. Total lock volume rose 28% month over month (MoM), led by a surge in refinance lending as borrowers seized on the opportunity to lower monthly payments. Purchases also climbed 6% MoM, outperforming typical seasonal trends as improved affordability brought more buyers into the market.

Optimal Blue's September 2025 Market Advantage mortgage data report
Image caption: Image caption: Optimal Blue’s September 2025 Market Advantage mortgage data report.

“The rate rally that began in late summer accelerated in September, and borrowers reacted quickly,” said Mike Vough, head of corporate strategy at Optimal Blue. “Rate-and-term refinance locks jumped 153% month over month, lifting total refi share to 39% – the highest level we’ve seen in more than two years. That momentum also spilled into purchase lending as affordability improved, particularly for first-time homebuyers.”

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended September at 6.32%, down 18 basis points (bps) from August. Jumbo rates dropped 11 bps to 6.47%, FHA fell 18 bps to 6.08% and VA declined 18 bps to 5.82%, reinforcing the broader affordability shift seen across loan types.

The report also highlighted notable movements in capital markets execution. Sales to the agency cash window and aggregators each fell 100 bps to 23% and 32% respectively, while agency mortgage-backed security (MBS) executions increased to 42% from 40%, reflecting stronger securitization activity among large lenders. The share of loans sold at the highest pricing tier climbed to 78%, up 300 bps, suggesting less focus on delivery profiles and fewer eligibility exceptions influenced pricing decisions.

“This combination of stronger pricing and greater securitization participation underscores lenders’ efforts to optimize execution as volume rebounds while maintaining profitability,” Vough said. “Even as MSR values edged down 6 bps in September, nearly eight in ten loans were sold at the highest pricing tier, showing how lenders are offsetting that compression through broader investor engagement.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Lock activity jumps: Total rate-lock volume increased 28% in September as falling rates reignited borrower demand.
  • Purchase volume rises: Purchase locks climbed 6% MoM and 9% year over year (YoY), outperforming typical late-season expectations.
  • Refinances dominate growth: Refi share expanded to 39% of all locks – the highest since early 2022 – driven by a 153% MoM increase in rate-and-term refinances and a 13% gain in cash-outs.
  • Refi pull-through improves: The pull-through rate for purchases climbed 58 bps to 83.6%. Refinance pull-through rose 82 bps to 60.2%.

Rates and pricing

  • Rates retreat across loan types: The OBMMI 30-year conforming fixed rate fell 18 bps to 6.32%. Jumbo rates dropped 11 bps to 6.47%, FHA loan rates fell 18 bps to 6.08% and VA loan rates declined 18 bps to 5.82%.
  • MSR valuations ease: Servicing values for conforming 30-year loans slipped 6 bps to 1.09% (a 4.36 multiple), mirroring rate declines and an average 30 bps drop in OBMMI levels across the month.
  • Lenders capture stronger execution: The share of loans sold at the highest pricing tier climbed to 78%, up 300 bps from August, signaling decreased focus on lender profile and eligibility and stronger focus on improved profitability.

Channel and execution

  • Securitization strengthens: Agency MBS executions increased to 42% from 40%, while deliveries to the agency cash window and aggregators fell 100 bps each to 23% and 32%, respectively.
  • Investor engagement steady: The average number of active investors held at 11, consistent with recent months as secondary market liquidity remained stable.

Product mix and borrower profiles

  • Conforming and VA gain share: Conforming and VA each picked up just over 1 percentage point of market share as borrowers in those segments moved quickly to refinance.
  • Credit profiles strengthen in refis: Average credit scores rose to 746 (up 9 points) for rate-and-term refinances and to 701 (up 7 points) for cash-outs as higher-credit borrowers responded first to lower rates.
  • DTI trends lower: Debt-to-income ratios declined for both conforming and FHA production and were down across all products YoY, signaling improving affordability.
  • FTHB participation increases: First-time homebuyer share rose in both FHA and VA production – up 1 bp each – while conforming was unchanged.
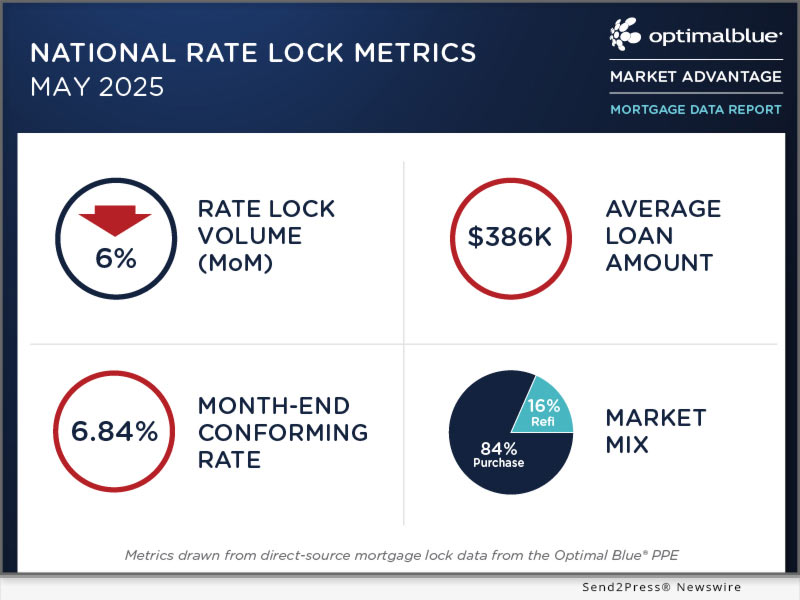
  • Loan amounts edge higher: The average loan amount was $403,746, up from $386,387 in August and $382,476 in July. September averages ranged from $605,542 in metro New York to $305,829 in Indianapolis. Average LTVs ranged from 73.57 in New York to 82.22 in Indianapolis.

To view the full September 2025 Market Advantage report, subscribe for free: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Andria Lightfoot, vice president of client success at FirstClose. Access the podcast: https://market-advantage.captivate.fm/episode/episode-13.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide transparency and insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MUILTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/25-1014-s2p-optbluesep25-300dpi.webp

Image caption: Optimal Blue’s September 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-rate-rally-drives-28-surge-in-september-lock-volumes/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130114 NOREL-3B


Refinances surge nearly 70% as purchase activity falls 10% in August

Seasonal slowdown weighs on purchases; lenders lean on securitization and non-QM to drive performance

PLANO, Texas, Sept. 10, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its August 2025 Market Advantage mortgage data report, which found a sharp split between purchase and refinance trends as seasonal factors and falling rates reshaped origination activity. Total lock volume dipped about 2% month over month (MoM) as a roughly 10% drop in purchase locks outweighed the strongest month for rate-and-term refinances this year, which surged nearly 70%. Non-QM lending also reached a new milestone in August, climbing to a record 8.3% of originations – up from 5.6% a year earlier and just 1.4% in August 2020 – extending the steady growth trend first highlighted in last month’s report.

Optimal Blue's August 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s August 2025 Market Advantage mortgage data report.

“Borrowers are responding quickly to rate improvements, driving the strongest month for rate-and-term refinances we’ve seen this year,” said Mike Vough, head of corporate strategy at Optimal Blue. “At the same time, purchase activity is beginning its typical seasonal decline, while product mix is shifting with non-QM lending at record levels.”

The OBMMI 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended August at 6.49%, down nearly a quarter point from July. Jumbo, FHA and VA rates also declined, falling 32, 24 and 33 basis points (bps), respectively.

The report also pointed to significant changes in capital markets execution, with securitization playing a larger role in loan sales. Agency cash window deliveries fell to 24% while agency MBS executions climbed to 40%, highlighting stronger securitization activity among larger lenders.

“This trend underscores how lenders are strategically adapting to optimize execution in order to gain market share,” Vough said. “We’re seeing deeper engagement in securitization alongside more loans sold to the highest price during loan sales, signaling that capital markets strategies are adjusting to increase profitability.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Lock volumes dip: Overall activity slowed 1.8% in August as the seasonal decline in purchase demand outpaced gains in refinance activity.
  • Purchase volumes slip: Purchase volume fell 9.8% MoM but remained flat year over year (YoY), ushering in the typical post–peak season slowdown.
  • Refis surge: Refinances rose to 26% of originations, up sharply MoM and YoY, as rate-and-term refinances surged 69.8% while cash-outs gained 2.2%.

Rates and pricing

  • Benchmark rates drop: The OBMMI ended August at 6.49%, down nearly a quarter point from July. Jumbo rates fell 32 bps to 6.57%, FHA decreased 24 bps to 6.26% and VA declined 33 bps to 6.00%, creating opportunities across loan types.
  • Pricing strength improves: Loans sold at the highest pricing tier rose to 75%, a 5-point increase, suggesting lenders delivered cleaner loan profiles and captured stronger pricing.
  • MSR valuations soften: MSR values dipped to 1.15% for conforming 30-year loans, down 4 bps, in line with lower rates that compressed servicing valuations.

Channel and execution

  • Cash share declines: Agency cash window sales fell 200 bps to 24% as lenders leaned less on cash executions in favor of strategic delivery methods.
  • MBS executions rise: Agency MBS executions climbed to 40%, reflecting increased securitization by larger lenders optimizing capital markets execution and market share.
  • Pull-through rates mixed: Purchase pull-through rose 22 bps to 84.2%, while refinance pull-through slipped 15 bps to 61%, indicating some softening in refi pipeline performance.

Product mix and borrower profiles

  • Non-QM hits record: Non-QM share rose to 8.34% of all originations in August, up from 8.03% in July and setting a new record high.
  • Conforming declines: Conforming share fell 123 bps to 51%. VA loans gained 78 bps to 12.1%, non-conforming increased 48 bps to 17.3%, FHA edged up 1 bp to 19% and USDA dipped 5 bps to 0.7%.
  • New build activity softens: Planned unit development (PUD) lending fell below 28% of production, down more than 4.5% YoY as new construction market share continued to contract.
  • FTHB activity steady: First-time homebuyer share held flat for conforming and FHA loans and dipped slightly for VA.
  • Borrower profiles remain strong: The average conforming FICO Score was 756, unchanged MoM. Average loan amounts rose to $386,387 from $382,476 in July, ranging from $600,110 in metro New York to $304,511 in Indianapolis. Average LTVs ranged from 73.56 in New York to 81.61 in Indianapolis.
  • ARMs hold: Adjustable-rate mortgages accounted for 10.25% of overall lock activity.

To view the full August 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Optimal Blue Chief Technology Officer Seever Sulaiman. Access the podcast: https://market-advantage.captivate.fm/episode/episode-12 .

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity, and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIAL

Image link for media: https://www.Send2Press.com/300dpi/25-0910-s2p-opbluaug25-300dpi.jpg

Image caption: Optimal Blue’s August 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/refinances-surge-nearly-70-as-purchase-activity-falls-10-in-august/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129198 NOREL-3B


Optimal Blue to Host Its 2026 Summit February 23-25 in Scottsdale

Event will bring together capital markets professionals, industry thought leaders, and experts in AI and innovation

PLANO, Texas, Aug. 18, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced it will host its 2026 Optimal Blue Summit from February 23–25 at the Talking Stick Resort and Conference Center in Scottsdale, Arizona. Building on the success of its inaugural event, the 2026 Summit will bring together the company’s clients and integration partners, along with thought leaders and experts from across the mortgage industry, for three days of insights, connection and strategy. Attendees will experience expert-led sessions, hands-on training and curated networking opportunities focused on maximizing mortgage lending profitability.

Optimal Blue SUMMIT 2026 Scottsdale AZ
Image caption: Optimal Blue SUMMIT 2026 Scottsdale AZ.

“Optimal Blue’s clients know that we don’t just talk about innovation – we deliver it,” said Joe Tyrrell, CEO of Optimal Blue. “Our annual Summit is where we unveil our latest solutions and share the details on how we’re using generative AI, automation and real-time data to address actual capital markets challenges. Every session is designed to provide lenders and investors with a competitive advantage for their business, instruct them on how to leverage the new innovation, and help them maximize their profitability – so attendees will walk away with real value for their businesses.”

Event highlights will include:

  • Generative AI and automation unveiling: Early access to Optimal Blue’s newest product deliverables, including advancements in AI that are reshaping capital markets strategies
  • Profitability-focused solutions: Detailed instructions of Optimal Blue’s capital markets platform, with specific focus on how lenders can achieve measurable ROI through advanced margin management, pricing intelligence and streamlined execution
  • Expert-led tracks: Sessions that provide key insights, tips, tricks and best practices on pricing, trading, compliance and consumer engagement, all led by industry experts
  • Tech showcases and feedback forums: Hands-on demonstrations of new capabilities and client roundtables to incorporate direct feedback into the future of Optimal Blue’s offerings
  • Networking and strategy: Unique opportunity for capital and secondary market leaders to connect with executives, industry peers, economists, policymakers and technology partners through interactive events

Early bird registration is now open at https://www2.optimalblue.com/optimal-blue-summit.

Spots are limited, so attendees are encouraged to register early and take advantage of discount pricing.

About Optimal Blue:

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA:

Video (YouTube): https://youtu.be/-gvQgOGh160?si=tl8L__kU3eMX_oNN

Event logo link for media: https://www.Send2Press.com/300dpi/25-0818-s2p-opbluesummit-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-to-host-its-2026-summit-february-23-25-in-scottsdale/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P128529 NOREL-3B


Refinances tick up and non-QM hits record high as purchase activity falls nearly 5% in July

Lenders respond to affordability pressures with loan product diversity and pricing strategies

PLANO, Texas, Aug. 12, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its July 2025 Market Advantage mortgage data report, which found a 3% month-over-month (MoM) drop in overall rate lock volume, led by a nearly 5% drop in purchase activity as affordability remained strained.

Optimal Blue’s July 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s July 2025 Market Advantage mortgage data report.

Mortgage rates rose MoM across all loan types. The OBMMI 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended July at 6.72%, up 5 basis points (bps). FHA, VA and jumbo rates also ticked up, rising 3, 4 and 11 bps respectively to 6.50%, 6.33% and 6.89%.

While purchase volume held steady year-over-year (YoY), refinancing showed renewed strength in July. Cash-out and rate-and-term refinance locks rose 5% and 7% respectively, partially offsetting the broader softness in the purchase market.

“As we near the end of peak buying season, 2025 purchase activity has largely tracked with 2024,” said Mike Vough, head of corporate strategy at Optimal Blue. “With affordability still a major constraint, purchase volume in line with 2024 is generally a disappointment to the industry based on 2025 projections We’re seeing more cash-out (+27% annually) and rate-and-term (+13% annually) opportunities as borrowers with post-2022 loans respond to even modest rate improvements, and borrowers may be undergoing some financial stress based on cash-out increases.”

Non-QM lending reached a new milestone in July, accounting for 8% of total rate lock volume – the highest on record. At the same time, GSE-eligible originations fell to 52.2% and non-conforming lending rose to 16.8%, underscoring a market shift toward nontraditional financing solutions. This can be attributed to elevated rates, increased debt, growing openness to alternative forms of income verification, and conventional loan limits, which are prompting more borrowers to seek flexible qualification paths.

“There’s growing separation in the ways larger and smaller lenders are managing profitability,” Vough added. “We saw an uptick in agency MBS executions, insinuating more market share is going to depositories and large IMBs, alongside stronger bid-to-cover ratios, indicating lenders are chasing the highest price over other execution considerations. Combined with deeper engagement in OBMMI-tied CME futures and many conversations about capital markets strategies for non-agency loans, it’s clear lenders are being proactive in their pricing, margin and pipeline risk strategies.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Volume down: Total locks declined 3% MoM in July, driven primarily by a 5% drop in purchase activity and reflecting ongoing affordability challenges.
  • Refinance share increases: Although only 20% of the market, refis are gaining traction as borrowers with post-2022 loans find opportunities to lower monthly payments. Cash-out and rate-and-term refis rose 5% and 7%, respectively.
  • PUD volume rises: Planned unit development (PUD) activity grew 0.85% to 28.5% of all production, while single-family homes declined by 0.87% to 63.5%. Despite the monthly increase, new construction market share is down 4% YoY, pointing to a broader builder pullback.

Rates and pricing

  • Benchmark rates climb: The OBMMI ended July at 6.72%, up 5 bps after dipping to ~6.625% earlier in the month. FHA rose 3 bps to 6.50%, VA increased 4 bps to 6.33% and jumbo jumped 11 bps to 6.89%.
  • MSRs dip: Mortgage servicing rights (MSRs) for conforming 30-year loans fell 3 bps to 1.19, moving in counter to OBMMI, but impacted by increases in intramonth volatility.
  • Futures activity rises: CME futures tied to the OBMMI are attracting increased interest from MSR holders and pipeline hedgers seeking to manage rate risk. MSR values tend to fluctuate with interest rate expectations, and recent activity suggests growing demand for tools that help mitigate exposure.

Channel and execution

  • Conventional share slips: The GSE-eligible share declined 0.78% to 52.2%, while non-conforming originations (including jumbo and non-QM) rose 0.62% to 16.8%. FHA, VA and USDA volumes remained flat MoM.
  • Hedged loan sales shift: Sales to the agency cash window fell 200 bps to 26%, while agency mortgage-backed security (MBS) executions rose to 37%, reflecting stronger securitization activity among large lenders and potential for market share increase from this cohort.
  • Loan sales favor higher pricing tiers: The share of loans sold at the highest price rose to 70% (+100 bps), while loans sold in the fourth tier or worse fell to 11% (-100 bps), suggesting that eligibility exceptions and representative delivery profiles played a smaller role in pricing decisions than in prior months.

Product mix and borrower profiles

  • Non-QM reaches record: The share of non-QM loans hit 8% of total volume for the first time, with investor/DSCR at 29%, bank statement loans at 34% and other non-traditional income documentation methods at 38%.
  • ARMs gain: Adjustable-rate mortgages (ARMs) rose to 9.52% of overall volume in July, up from 8.81% in June, despite the SOFR curve flattening with the 2-year/10-year spread dropping ~ 7 bps, but remaining positively sloped.
  • Average credit scores: Conforming FICO scores fell 1 point to 756, and FHA scores dropped to 675, while VA remained flat at 713.
  • Loan amounts dip: The average loan amount was $382,476, down from $386,084 in June. Of the top 30 MSAs, average loan amounts ranged from a high of $609,008 in the New York region to a low of $476,637 in Sacramento, California.

To view the full July 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Julian Hebron, founder of The Basis Point. Access the podcast: https://market-advantage.captivate.fm/episode/episode-11.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity, and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA:

Image link for media https://www.Send2Press.com/300dpi/25-0812-s2p-opblue-july-300dpi.jpg

Image caption: Optimal Blue’s July 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/refinances-tick-up-and-non-qm-hits-record-high-as-purchase-activity-falls-nearly-5-in-july/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P128390 NOREL-3B


Optimal Blue’s New Brand Reflects Its Modern Technology and Proven Expertise and Leadership

Comprehensive new brand includes a new logo, visual identity and messaging focused on the company's role as a trusted, innovative partner that drives the capital markets ecosystem

PLANO, Texas, Aug. 11, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today launched a new brand that emphasizes the company’s market leadership in delivering modern innovation backed by decades of proven, trusted performance. “Optimal Blue is operating in an era defined by accuracy, scale, speed and artificial intelligence – and our new brand embodies that,” said Joe Tyrrell, CEO of Optimal Blue.

Optimal Blue logo.
Image caption: Optimal Blue’s new brand logo.

“We continue to invest in AI and innovations that help our clients stay accurate, move faster and make smarter, more informed and profitable lending decisions. At the same time, we’re building on more than two decades of trusted expertise, performance and unrivaled pricing accuracy. It’s this combination – modern and proven – that makes Optimal Blue the most trusted partner in the capital markets today.”

The new brand introduces a new logo and visual identity, along with messaging that more clearly depicts Optimal Blue’s role as the engine that powers lender profitability with innovative technology and proven results.

“This new brand is more than a visual update – it’s a bold statement about who we are and where we’re going,” said Sara Holtz, chief marketing officer at Optimal Blue. “Our visual identity and messaging not only reflects all the changes and enhancements that we have recently made, but also the fact that Optimal Blue delivers the best of both worlds: modern technology and decades of trust. It’s a reflection of our momentum and mission to continue delivering the innovative solutions lenders need for success.”

The new logo icon embodies Optimal Blue’s role as the central hub of the capital markets ecosystem – representing unity, continuity, and the full capital markets life cycle. The dual-sided symmetry captures the essence of Optimal Blue’s identity: one side symbolizes innovation through cloud-native infrastructure and AI-driven automation, while the other reflects a legacy of trust, accuracy, and market leadership.

The tagline – Modern. Proven. – captures the essence of the unique value Optimal Blue delivers to mortgage lenders, representing the dual promise the company makes to lenders and the values for which it stands.

  • Modern: Optimal Blue is built on a foundation of modern innovation that’s designed to evolve. Its platform is API-first, cloud-native, and architected for scale, speed, and resilience. Generative AI, machine learning, and real-time data syncing position the company’s clients to adapt to market shifts and regulatory changes without disruption.
  • Proven: With decades of experience and the largest market share in key capital markets segments, Optimal Blue is a proven and trusted name in mortgage technology. The company’s deep expertise, honed over decades, powers the precision, compliance, and confidence lenders rely on to power profitability.

The company has begun implementing the new brand across all channels today, and it expects to have all updates complete in early 2026.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth.

To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA:

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blues-new-brand-reflects-its-modern-technology-and-proven-expertise-and-leadership/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P128354 NOREL-3B


Optimal Blue Fully Automates Best Efforts Locking Directly with Investors

Launch of new capability in the Optimal Blue PPE allows lenders to eliminate all manual steps when executing best efforts locks

PLANO, Texas, July 30, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced a new capability in its industry-leading product, pricing and eligibility (PPE) engine that fully automates the process for a lock desk user to execute best efforts locks directly with participating investors via API. By eliminating the last remaining manual step in the locking life cycle, Optimal Blue is delivering innovations and enhancements that will help significantly increase a lender’s efficiency and profitability. The Optimal Blue PPE is the first pricing engine to fully automate this critical stage of the secondary market workflow for investors with support for all loan types, including both agency and non-agency programs.

Optimal Blue logo
Image caption: Optimal Blue logo.

“This is a game-changer for capital markets teams that will save an average of 15 minutes per loan, which is hours saved per day,” said Tiffany McGarry, vice president of product management at Optimal Blue. “Lock desk users can now complete the entire best efforts lock transaction from within the Optimal Blue PPE – no toggling between systems, no rekeying of data and no lost time. It’s a meaningful step forward for day-to-day productivity that helps protect lenders against costly errors and compliance issues, while giving investors a more streamlined path to work with their originator partners.”

The Optimal Blue PPE already automates loan pricing, lock requests and post-lock changes, and the company’s hedging platform already supports automation for mandatory execution. Until the release of this capability, completing a best efforts lock required the lender’s secondary desk to log in to the investor’s portal and re-enter loan details by hand. This enhancement eliminates this final step to execute the lock, fully automating the process.

Best efforts lock requests can now be sent directly to an investor via API, reducing the time required from an average of 15 minutes per loan to just seconds. Loan data flows securely to the investor and back, keeping the loan origination system record up to date and generating a PDF confirmation that provides a clear audit trail and proof of execution. The feature is available at no additional cost to lenders and requires little to no setup or configuration.

The new capability offers a compelling way for the more than 240 investors in Optimal Blue’s network to stand out to over 1,000 originators by delivering a faster, more streamlined means to lock. To participate, investors should contact their Optimal Blue representative to complete a one-time API setup.

“This is the first time investors have been able to complete best efforts locks through real-time, system-to-system connectivity with their lender partners,” said Erin Wester, chief product officer at Optimal Blue. “We’ve already set up this integration with select investor partners, and it’s been exciting to see the positive momentum it is already building for their businesses. It’s a strategic edge that improves execution, strengthens lender-investor relationships and streamlines the path to purchase – and one only Optimal Blue can deliver as the industry’s most connected capital markets platform.”

Future phases of the best efforts lock feature will add support for profile updates, extensions and other post-lock changes as well as integration into the CompassEdge platform – enhancing consistency and reducing downstream data mismatches. For more information, lenders and investors using the Optimal Blue PPE should contact their account representative.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-fully-automates-best-efforts-locking-directly-with-investors/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P128097 NOREL-3B


Refis, Product Shifts and Strong Agency Participation Define June Market Advantage Report

Optimal Blue data shows modest lock volume growth as purchase activity levels off and investor demand for shorter-duration assets grows

PLANO, Texas, July 8, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its June 2025 Market Advantage mortgage data report showing total lock volume rose 1.95% month-over-month (MoM), driven by increased refinance activity. Refinance share climbed from 16% to 18% of all locks as rate-and-term refinances jumped 17.4% MoM and 18.4% year-over-year (YoY). Cash-out refinances rose 8.1% from May and nearly 28% YoY. Meanwhile, purchase activity held relatively steady – a better-than-expected result for June, when the spring homebuying season typically tapers off.

Optimal Blue's June 2025 Market Advantage mortgage data report.
Image caption: Image caption: Optimal Blue’s June 2025 Market Advantage mortgage data report.

The report includes 19 mortgage data metrics, including additional borrower profile metrics and secondary market indicators newly introduced last month. One of these new metrics, non-QM lending, accounted for 7.4% of all June rate locks – a share that has gradually increased in recent months as lenders and borrowers explore alternative qualification paths.

“As market conditions evolve and affordability challenges persist, non-QM lending offers a path for qualifying creditworthy borrowers who may not meet qualified mortgage guidelines,” said Mike Vough, head of corporate strategy at Optimal Blue. “The steady rise in this category reflects the industry’s growing focus on flexibility and meeting borrowers where they are.”

On the capital markets side, the aggregator share of loan sales dropped 300 basis points (bps) MoM to 35%, suggesting that the agencies improved pricing margins and gained market share, either via the cash window or MBS securitizations.

“Given current news headlines, the decrease in aggregator market share corresponding with the increase in agency market share is noteworthy,” said Vough. “Both loans sold to the cash window and via MBS securitization were up 2% month over month. This highlights the need for lenders to review multiple investors and delivery methods to squeeze the most out of their loan sales.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

  • Rates edge lower: The 30-year conforming loan rate dropped 17 bps to 6.67%. Jumbo rates fell 24 bps to 6.78%. FHA rates declined 6 bps to 6.47%, and VA rates decreased 16 bps to 6.29%.
  • Product mix shifts: Conforming share rose 114 bps to 53% of total volume, while non-conforming dipped 25 bps to 16.2%. FHA share declined 80 bps to 18.9%. VA and USDA shares held steady at or near last month’s levels at 11.3% and 0.7%, respectively.
  • Credit quality unchanged: The average FICO score edged up 1 point to 733.
  • Loan characteristics hold steady: The average loan amount declined slightly to $386,084. Across the top 30 MSAs, average loan amounts ranged from a high of $586,997 in metro New York to a low of $311,331 in Indianapolis. Average loan-to-value (LTV) ratio stood at 80.5%. Debt-to-income (DTI) ratio averaged 36.8% for conforming loans, 44.7% for FHA and 43.8% for VA.
  • ARMs decline: Adjustable-rate mortgage (ARM) share fell to 8.81%, compared to 9.11% in May. This decrease coincided with a slight flattening of the yield curve compared to the previous month.
  • Market spread trends remain steady: The 10-year Treasury yield dropped 17 bps to 4.24%, while the OBMMI 30-year conforming fixed rate (the benchmark for CME Group’s Mortgage Rate futures) declined 17 bps to 6.67%, keeping the spread steady at 2.43%.
  • Loan sales trend in agencies’ favor: Bulk aggregator sales declined 300 bps to 35%, while agency share grew as cash and MBS executions each rose 200 bps, signaling stronger agency appetite.
  • Loan pricing improves: The share of loans sold at the highest price increased 100 bps to 69%, while sales in the lowest pricing tier declined 100 bps to 12%, suggesting that loan characteristics or eligibility requirements played a smaller role in driving price dispersion.
  • Servicing valuations edge lower: MSR values for 30-year conforming loans declined slightly to 1.226%, tracking alongside the decrease in mortgage rates.
  • Pull-through rates increase: Supported by late-month rate improvements and steady new construction activity, purchase pull-through rose 170 bps to 84.8% and refinance pull-through climbed 29 bps to 62.6%.

To view the full June 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Rob Kessel, founder of Panoramic Capital Advisory and Consulting. Access the podcast: https://market-advantage.captivate.fm/episode/episode-10.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity, and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflects the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/25-0708-s2popblujune-300dpi.jpg

Image caption: Optimal Blue’s June 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/refis-product-shifts-and-strong-agency-participation-define-june-market-advantage-report/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P127507 NOREL-3B


Optimal Blue Releases May Data Findings, Announces Expansion of Monthly Report for More Comprehensive Lender Profitability Insights

Company adds nine new data metrics to its Market Advantage mortgage data report for deeper view into drivers of lending profitability, including DTI, loan sale execution and borrower profiles

PLANO, Texas, June 10, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released the May 2025 edition of its now-expanded Market Advantage mortgage data report, which features newly added borrower profile and capital market datasets for a more comprehensive picture of early-stage mortgage activity and loan profitability. The enhancements come at a critical time for mortgage lenders navigating heightened interest rates, tighter margins, increased volatility and deepening affordability challenges.

Optimal Blue's May 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s May 2025 Market Advantage mortgage data report.

NEW DATA REVEALS DEEPER INSIGHTS INTO BORROWER BEHAVIOR AND CAPITAL MARKETS DYNAMICS

This month’s report includes five new borrower profile metrics, including first-time homebuyer status, debt-to-income ratio and citizenship, as well as four new secondary market indicators, including data on loan sale execution and servicing valuations. These insights help lenders understand not just who is borrowing, but how loan performance and profitability are being shaped in capital markets.

“The Market Advantage has long been a trusted source for early mortgage market insights, and we’ve used Optimal Blue’s position as the leader in capital markets technology to take the report to the next level,” said Mike Vough, head of corporate strategy at Optimal Blue. “These new metrics provide deeper insight into the interconnectedness of front-end borrower affordability and back-end loan sale execution, allowing housing finance professionals and market observers alike to better understand how primary market activity and secondary market dynamics intersect to drive lending profitability.”

SPRING HOMEBUYING SEASON UNDERPERFORMS AS AFFORDABILITY TIGHTENS

While May typically brings a seasonal lift in purchase activity, this year’s data tells a different story. Total lock volume fell 5.87% month-over-month (MoM), and purchase activity was flat – a clear underperformance for what is typically one of the strongest homebuying months of the year. Rising interest rates further suppressed refinance incentives, dragging refinance share down from 21% to 16%.

“Rising mortgage rates are squeezing borrower affordability, while tighter spreads are putting pressure on lenders in the secondary market,” said Brennan O’Connell, director of data solutions at Optimal Blue. “With the brief window of affordability relief now closed, the new data shows first-time buyers are feeling the strain, with modest declines in their share of conforming and FHA loan locks.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

  • Overall lock activity declines: Total mortgage rate lock volume fell 5.87% MoM, reflecting a more difficult rate environment.
  • Refinance activity drops sharply: Refinance share declined from 21% to 16% as rising rates further eroded borrower incentive. Rate-and-term refinances were down 44.4% MoM, while cash-out refis fell 10%.
  • Spring purchase demand underwhelms: Purchase activity was flat MoM, and purchase lock counts (which control for home price appreciation) were down 10% year-over-year (YoY).
  • Rates rise and spreads tighten: The OBMMI 30-year conforming fixed rate (the benchmark for the CME Mortgage Rate futures) rose 16 basis points to 6.84%. The 10-year Treasury yield increased 26 bps to 4.41%, narrowing the OBMMI-Treasury spread to 2.44%, a 10 bps MoM contraction. This signal of rising secondary market pressure was reinforced by slight declines in two of the newly added metrics in this month’s report: servicing valuations and the share of loans executed at the highest price.
  • Product mix shifts modestly: Conforming loan share rose to 51.9% (up 92 bps), and nonconforming share edged up to 16.4% (up 4 bps). Government-backed lending declined as FHA share fell to 19.7% (down 52 bps), VA dropped to 11.4% (down 48 bps) and USDA lending held steady at 0.7%.
  • Credit quality holds steady: The average FICO score and average debt-to-income (DTI) ratio held steady across various loan programs.
  • Loan amounts trend lower: The average loan amount dipped slightly to $386,460 from April’s $387,523. Average loan-to-value (LTV) ratio stood at 80.87%. Across the top 30 metropolitan statistical areas, average loan amounts ranged from a high of $602,888 in metro New York to a low of $385,597 in Raleigh, North Carolina.
  • ARM usage declines: Adjustable-rate mortgages accounted for 9.11% of lock volume, down from 10.3% in April.
  • FTHB share softens: First-time homebuyer share was 42% for conforming loans (down 1%), 68% for FHA (down 2%) and 48% for VA (up 1%). The decline in conforming and FHA FTHB share suggests affordability headwinds may be weighing more heavily on entry-level borrowers.
  • Non-QM lending edges up: Loans locked under expanded guidelines (i.e., non-QM) represented 7.36% of May’s volume, continuing a gradual upward trend as lenders and borrowers explore alternative qualification paths.

To view the full May 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Optimal Blue CEO Joe Tyrrell. Access the podcast: https://market-advantage.captivate.fm/episode/episode-9/

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage data report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity, and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

IMAGE LINK for media: https://www.Send2Press.com/300dpi/25-0619-s2p-opbluemay25-300dpi.jpg

Image caption: Optimal Blue’s May 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-releases-may-data-findings-announces-expansion-of-monthly-report-for-more-comprehensive-lender-profitability-insights/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P126818 NOREL-3B


Optimal Blue Launches New Lead Generation Tool for Originators

Capture for Originators helps lenders approach borrowers at the right time with 'makes sense' refinance scenarios

PLANO, Texas, June 9, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced a new product that helps originators efficiently track and identify refinance opportunities so they can reengage borrowers with eligible refinance options at the right time. Available to Optimal Blue PPE users, Capture for Originators dramatically reduces the manual effort loan officers currently spend evaluating refinance potential by automatically analyzing entire portfolios each month and putting recapture opportunities directly into originators’ hands.

Optimal Blue logo
Image caption: Optimal Blue.

“Instead of expecting originators to review all of their past clients to find refinance opportunities, we have given them a solution that automatically identifies an opportunity, provides pricing options and generates a presentation to the borrower,” said Mike Vough, head of corporate strategy at Optimal Blue. “Capture gives originators an efficient, data-driven way to identify borrower savings and turn that opportunity into reality.”

Capture for Originators goes far beyond basic rate alerts. It provides a user-friendly dashboard that surfaces closed loans with refinance potential, complete with break-even calculations for multiple scenarios, closing cost estimates and borrower savings analysis. By automatically factoring in lender fees and current pricing from the Optimal Blue PPE, Capture helps loan officers act quickly and accurately without spreadsheets or manual data pulls.

Once an opportunity is identified, Capture for Originators generates pre-filled borrower outreach emails that include an easy-to-read summary of available refinance options backed by the industry-leading accuracy of the Optimal Blue PPE along with a link to the lender’s point-of-sale experience or borrower intake form. The tool also streamlines an originator’s ability to evaluate new refinance prospects. Loan officers can input referral details directly within the Capture for Originators interface, as well as send an intake form directly to new prospects, making it easy to start the conversation with referred borrowers and instantly analyze their existing loan. An activity log tracks all borrower outreach history.

Developed in partnership with Uplist, a leading SaaS platform for the real estate industry, Capture for Originators includes all the data sources loan officers need to assess refinance potential. That includes automated valuation models (AVMs), county records and live pricing elements, including branch and originator margins and concessions – all integrated out of the box. With this data in place, lenders can deliver personalized refinance offers without the complexity and cost of managing external integrations or market-tracking tools.

“Our approach at Uplist is all about giving originators more efficiency and accuracy, and we are thrilled to partner with Optimal Blue to make these benefits accessible to more originators,” said Jeff Bell, president of Uplist. “Rather than spending up to 30 minutes manually evaluating each loan and creating presentations, originators can now rely on Capture for Originators to identify refinance opportunities they might otherwise miss – and deliver them to clients with minimal effort.”

To begin taking advantage of Capture for Originators, Optimal Blue PPE users should contact their Client Services representative or Sales@OptimalBlue.com.

About Optimal Blue:

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-launches-new-lead-generation-tool-for-originators/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P126784 NOREL-3B


Optimal Blue Releases Executive-Level AI Insights Tool, Ask Obi, to Clients

The no-cost, AI-powered assistant is built for executive decision-makers seeking fast answers to complex business profitability questions

PLANO, Texas, May 19, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced that Ask Obi, an AI-powered assistant designed to help mortgage lending executives extract real-time insights from across Optimal Blue’s capital markets platform, is now generally available to all PPE clients. Introduced at the company’s inaugural user conference in February and refined through beta testing with select clients, Ask Obi provides executives with fast answers to complex profitability questions at no additional cost.

Optimal Blue logo
Image caption: Optimal Blue logo.

Ask Obi is built for executive decision-makers who need reliable, data-driven answers to complex business questions. By aggregating data across Optimal Blue’s solutions, it enables users to ask conversational questions – such as ‘where did margins shift the most last quarter?’ or ‘which branches issued the highest concessions last month?’ – and receive clear, visual responses that support confident, strategic decisions. An interface sidebar retains previous queries, making it easy to revisit past prompts or rerun commonly used questions with a single click.

“Ask Obi fills a critical need for lending leaders: making capital markets performance data not just accessible, but actionable,” said Erin Wester, chief product officer at Optimal Blue. “What makes Ask Obi stand apart is its ability to synthesize information across systems. Most AI tools in our space are focused narrowly on origination workflows, but Ask Obi helps executive teams view their operations holistically and at a level that’s often difficult to achieve without a dedicated analyst.”

Although available as a standalone product, Ask Obi is powered by and seamlessly connected to other Optimal Blue offerings. The more products a client uses, the deeper and more contextual Ask Obi’s insights become. As part of a broader rollout of AI-powered capabilities, Ask Obi complements tools like Optimal Blue’s recently launched Originator Assistant, which helps front-line originators compare and present optimal loan scenarios.

Ask Obi’s general availability comes just ahead of the Mortgage Bankers Association’s Secondary and Capital Markets Conference and marks another milestone in a series of planned enhancements for Optimal Blue clients this year.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-releases-executive-level-ai-insights-tool-ask-obi-to-clients/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P126254 NOREL-3B


Lock Volume Rises 3.2% in April, Driven by Uptick in FHA Loans, Despite Economic Volatility

Optimal Blue's April 2025 Market Advantage data report shows stronger purchase activity, a shifting loan mix, and signs of investor caution

PLANO, Texas, May 13, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its April 2025 Market Advantage mortgage data report showing total loan lock volume rose 3.2% month-over-month (MoM) as the spring homebuying season progressed, with purchase locks up 7.5% despite ongoing economic pressures.

Optimal Blue's April 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s April 2025 Market Advantage mortgage data report.

April kicked off with significant volatility in the bond market as investors responded to tariff announcements. Over the first 10 days of the month, interest rates fluctuated between 6.48% and 6.98%, a 50-basis-point (bps) range. The benchmark OBMMI 30-year conforming fixed rate briefly fell below 6.5% for the first time since October 2024 before climbing to end the month at 6.7%, about 10 bps above where it started.

“Last month’s report showed early signs of spring homebuyer activity, and April confirms the season is underway with a solid increase in purchase locks,” said Brennan O’Connell, director of data solutions at Optimal Blue. “We also saw a shift toward FHA loans, often used by first-time or credit-challenged buyers, and away from non-conforming products, possibly reflecting investor caution in response to broader economic uncertainty.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock data, include:

  • Interest rate turbulence: Rates whipsawed at the start of the month amid market reactions to new tariff developments, dropping by one-eighth essentially overnight. The OBMMI 30-year conforming fixed rate – the benchmark for the CME Mortgage Rate futures contract – finished April at roughly 6.7%, up from 6.6% in March. FHA rates rose 17 bps to 6.44%, VA rates rose 9 bps to 6.28%, and jumbo rates climbed 11 bps to 6.84%.
  • YoY purchase volume down, again: While MoM purchase locks were up 7.5%, they were down 5% YoY. Isolating purchase loan counts reveals a deeper 7% YoY decline, continuing a trend seen each month so far this year.
  • FHA loans gain ground as other categories slip: FHA share rose to 20.2% in April, gaining 50 bps, while non-agency lending fell 46 bps to 16.4%. The shift suggests reduced investor risk tolerance amid economic uncertainty. Conforming loan share dipped slightly to 51%, and VA share also declined modestly to 11.8%. USDA volume remained steady at 0.6%.
  • Adjustable-rate mortgages rise: ARMs accounted for 10.34% of total lock volume in April, up from just under 9% in March, as buyers looked for ways to improve affordability.
  • Refinance activity stalls: After a couple of very strong days early in the month, refinance volume fell off in response to rising interest rates. Rate-and-term refis dropped 15% MoM, and cash-out refis dipped 3%. Refinance share fell from 25% in March to 21% in April.
  • Loan amounts, home prices edge down: The average loan amount declined to $387.5K from $391.7K, while the average purchase price slipped to $483.5K from $486.9K. Regional differences remain stark; average loan amounts ranged from $601,660 in the New York City metro area to $374,945 in greater Minneapolis.

The full Market Advantage report, which provides more detailed findings and additional insights into U.S. mortgage market trends, can be viewed at (PDF): https://www2.optimalblue.com/OB_MarketAdvantage_MortgageDataReport_Apr2025.pdf

This month’s Market Advantage podcast features Optimal Blue Chief Product Officer Erin Wester, discussing the impact of technological innovations in the mortgage industry. Watch or listen to the episode: https://market-advantage.captivate.fm/episode/episode-8/.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage data report each month to provide early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE – the mortgage industry’s most widely used product, pricing, and eligibility engine – the Market Advantage provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders’ pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/25-0513-s2p-opbluapril-300dpi.jpg

Image caption: Optimal Blue’s April 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/lock-volume-rises-3-2-in-april-driven-by-uptick-in-fha-loans-despite-economic-volatility/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P126135 NOREL-3B


Optimal Blue Brings AI-Powered Originator Assistant to Market, Helping Originators Present Best Possible Loan Options to Borrowers

Leader in mortgage capital markets technology delivers on innovations unveiled at Summit user conference

PLANO, Texas, May 1, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced the general availability of Originator Assistant, a powerful addition to the Optimal Blue PPE. Leveraging generative AI, Originator Assistant eliminates human bias in the loan structuring process and helps originators identify all options for a borrower, providing more ways to help consumers realize the American dream of homeownership.

Optimal Blue logo
Image caption: Optimal Blue.

Unveiled at the inaugural Optimal Blue Summit in February and now available to all Optimal Blue PPE clients using the enhanced originator interface, Originator Assistant is an AI-powered recommendation engine that simplifies loan structuring by identifying alternate scenarios with more competitive pricing. The tool automatically detects pricing breakpoints and suggests opportunities for more strategic loan discussions, saving loan officers time and eliminating manual guesswork. The tool evaluates loan options based on various parameters while searching for pricing incentives on the peripheral or opportunities for adjustment to achieve different terms. Combined with Scenario Optimizer, which enables side-by-side comparisons, Originator Assistant gives lenders a distinct advantage in presenting the best options to borrowers.

Further building on its delivery of innovation, Optimal Blue also announced the beta release of enhanced Lock Extensions workflows, a feature reimagined in close collaboration with the company’s clients. The feature gives lenders greater control, automation and flexibility over lock extension policy management. The new Lock Extensions experience allows Optimal Blue PPE users to configure policies across multiple investors using global product groups, significantly reducing manual work and complexity. It also introduces a step-by-step configuration workflow, advanced toggles to support compliance considerations, and automation tools for processing and tracking extension requests. Together, Originator Assistant and Lock Extensions help lenders respond faster to market conditions, reduce manual error and apply lock policies with greater consistency and precision.

“Originator Assistant and our enhanced Lock Extensions feature are great examples of how we listen closely to our customers and build solutions that solve real problems,” said Erin Wester, chief product officer at Optimal Blue. “These latest enhancements demonstrate that innovation is not just a promise at Optimal Blue, it’s a practice. Our clients can continue to expect exciting product updates as Optimal Blue heads toward the MBA Secondary and Capital Markets conference later this month.”

Both enhancements are accessible by Optimal Blue PPE clients with no setup required. Originator Assistant runs automatically, and existing lock extension policies will be migrated to the new Lock Extensions experience, allowing clients to begin making updates right away. Additional innovations introduced at the Optimal Blue Summit, including Rules Optimizer, Ask Obi and the Solution Center, are expected to reach general availability later this spring.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-brings-ai-powered-originator-assistant-to-market-helping-originators-present-best-possible-loan-options-to-borrowers/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P125900 NOREL-3B


Cooler Interest Rates Heat Up Refinances and Spark Early Signs of Purchase Demand

Optimal Blue's March 2025 Market Advantage report shows an increase in non-conforming share as buyers seek greater flexibility and higher loan limits

PLANO, Texas, April 8, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its March 2025 Market Advantage mortgage data report, showing a 24% surge in rate lock volume as early spring buyers returned to the market and homeowners jumped at the chance to refinance into lower rates. While still down 2% on a year-over-year (YoY) basis, purchase volumes were up 21% month-over-month (MoM). Rate-and-term and cash-out refinances jumped 52% and 20% MoM, respectively, together representing 25% of all lock activity.

Optimal Blue's March 2025 Market Advantage mortgage data report.
Image caption: Optimal Blue’s March 2025 Market.

“March brought a notable shift in borrower behavior,” said Brennan O’Connell, director of data solutions at Optimal Blue. “Refinances made up a quarter of all lock activity for the first time in six months, and we saw a clear rise in non-conforming loan share as buyers looked for more flexible options and higher loan amounts. These are key indicators that consumers are actively adapting to the current rate environment.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock data, include:

  • Refinances take share from purchase loans: Strong growth in refi activity during March pushed the share of refinances up to 25%, the highest level seen since September 2024. The pull-through rate for refinances was 63.3%.
  • Purchase volume up MoM, but down YoY: Despite positive MoM momentum, purchase activity was down 2% YoY. Isolating loan counts instead of dollar volume – effectively controlling for home price appreciation – reveals an even steeper 6% decline in purchase activity. The pull-through rate for purchase loans was 82.9%.
  • Non-conforming share rises: Conforming loan production continued to hover near historic lows, while non-Agency loan share hit its highest level since April of 2022. Non-conforming loans, which include jumbo and non-QM loans, accounted for 16.8% of total rate lock volume. Conforming loan share fell to 51% and FHA share dropped to 19.6%, while VA volume inched upward, reaching nearly 12% share.
  • Adjustable-rate mortgages gain steam: ARMs accounted for just below 9% of total rate lock volume in March, a result tied to growing demand for non-conforming loan options. Optimal Blue will continue to monitor this data point as buyers search for greater affordability.
  • Rates stay relatively flat: After a strong rally the last week of February, the OBMMI 30-year conforming fixed rate – the benchmark for the CME Group’s Mortgage Rate futures – finished the month flat at 6.6%. FHA rates fell 8 basis points (bps) to 6.27%, while VA and jumbo rates rose a modest 3 and 4 bps to 6.13% and 6.73%, respectively.
  • Refi credit quality ticks higher: March saw a 3-point increase in average credit scores for both cash-out and rate-and-term refinances, rising to 735 and 699, respectively, as higher-credit homeowners acted quickly on refinance opportunities.
  • DTI trends downward: The average debt-to-income (DTI) ratio across all loans dropped from February’s 37.3% to 36.7% in March, reflecting income growth outpacing the rise in household debt [*note 1]. This fall in DTI represents a healthier balance between monthly income and debt than tracked in previous months.
  • Loan sizes grow alongside home prices: The average home purchase price rose from February’s $480.2K to $486.9K in March, driving a MoM increase in average loan amount from $380.5K to $391.7K.

The full Market Advantage report, which provides more detailed findings and additional insights into U.S. mortgage market trends, can be viewed at (PDF): https://www2.optimalblue.com/wp-content/uploads/2025/04/OB_MarketAdvantage_MortgageDataReport_Mar2025.pdf

This month’s Market Advantage podcast features Optimal Blue Head of Corporate Strategy Mike Vough, offering additional market insights. Watch or listen to the episode: https://market-advantage.captivate.fm/episode/episode-7/.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage data report each month to provide early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE – the mortgage industry’s most widely used product, pricing, and eligibility engine – the Market Advantage provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders’ pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit OptimalBlue.com.

NOTE/CITATION:

[1] https://libertystreeteconomics.newyorkfed.org/2024/11/income-growth-outpaces-household-borrowing/

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/cooler-interest-rates-heat-up-refinances-and-spark-early-signs-of-purchase-demand/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P125367 NOREL-3B


Optimal Blue’s Shawn Chandwani Named to HousingWire’s 2025 Rising Star List

Award recognizes emerging leaders in real estate and mortgage who have achieved remarkable milestones before the age of 40

PLANO, Texas, April 1, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced that Senior Software Engineering Manager Shawn Chandwani, 34, has been named among HousingWire’s Rising Stars. The annual list celebrates young professionals who shoulder significant leadership responsibilities and contribute to the broader industry and business landscape, establishing themselves as influential figures and leaders for tomorrow.

Shawn Chandwani of Optimal Blue
Image caption: Shawn Chandwani of Optimal Blue.

Just a decade into his career, Chandwani already personifies that level of achievement. The senior software engineering manager leads Optimal Blue’s AI initiatives, uniting cross-functional teams to collaborate with partners like Microsoft and ensure Optimal Blue continually differentiates itself in the market with new product innovations.

In 2024, Chandwani led Optimal Blue’s development of two AI-driven products: Ask Obi, an AI assistant that makes it easy for executives to get insights from their Optimal Blue products and data without running and analyzing reports, and Originator Assistant, an AI-powered tool in the Optimal Blue PPE that identifies alternate loan scenarios to help LOs offers more competitive pricing and spark strategic discussions that win borrowers’ business.

Both Ask Obi and Originator Assistant were showcased at Optimal Blue’s inaugural Summit user conference, where 60 customers immediately signed up to be beta testers. Their enthusiastic reception underscores Optimal Blue’s mission to help lenders maximize profitability on every loan, an ethos Chandwani champions each day.

“I really appreciate how we listen to each other here, from the newest member of the team to the most seasoned, because we know great ideas can come from anyone at any level,” said Chandwani. “I am grateful for the opportunity to do what I love and appreciate the external recognition, which really is a recognition of the innovative work done by Optimal Blue’s entire engineering team.”

“The Rising Stars award is a celebration of the incredible energy, innovation and talent shaping the future of housing,” said Sarah Wheeler, editor-in-chief at HousingWire. “This year’s winners are not only excelling in their respective fields but are also redefining what’s possible in the industry. Their creativity and leadership inspire confidence in the industry’s future, and I can’t wait to see how they continue to drive progress.”

For HousingWire’s complete list of 2025 Rising Stars, visit https://www.housingwire.com.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blues-shawn-chandwani-named-to-housingwires-2025-rising-star-list/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P125155 NOREL-3B


Optimal Blue Establishes Alliance with Cotality to Expand the Reach of Its Mortgage Origination and Pricing Data

Cotality to Offer Optimal Blue's Direct-Source Origination Data to Capital Markets, Research, and Investment Firms

PLANO, Texas, March 27, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced a strategic alliance with Cotality™ (formerly CoreLogic®) that expands access to its mortgage origination and pricing data. Through this collaboration, Cotality will offer Optimal Blue’s data to a broader audience, including hedge funds, capital markets participants, and investment firms seeking insights into the mortgage markets.

Optimal Blue logo
Image caption: Optimal Blue logo.

Optimal Blue sources mortgage rate lock data directly from its product, pricing, and eligibility (PPE) engine, which is used to lock more than one-third of U.S. mortgages. By offering mortgage origination and pricing data alongside its extensive suite of real estate data and analytics solutions, Cotality’s clients gain access to more comprehensive housing market data that helps them improve decision-making, forecasting, and risk management strategies.

“Optimal Blue’s growing relationship with Cotality represents our shared commitment to bringing meaningful data and analytics to participants across all segments of financial markets whose businesses can benefit,” said Mike Vough, head of corporate strategy at Optimal Blue. “Optimal Blue offers the most representative, direct-source mortgage rate lock data available – a strategic complement to Cotality’s extensive property insights – giving financial market participants a holistic view of housing market dynamics to enhance investment decisions.”

“Offering Cotality’s comprehensive property data available with Optimal Blue’s direct to source mortgage rate lock dataset gives our customers additional insights and demonstrates our commitment to innovation— making the industry smart and faster,” said Sachin Rajpal, Managing Director of Cotality Data Solutions.

​​Optimal Blue’s Market Data License enables institutions to access loan-level origination and pricing information daily via secure file transfer protocol (SFTP), search over 60 variables per loan – including product type, pricing, credit attributes, property details, and occupancy status – and track primary market production trends and shifting borrower demographics. Additional use cases include supporting advanced market share analysis and portfolio benchmarking while gaining deeper insights into housing and mortgage market movements.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-establishes-alliance-with-cotality-to-expand-the-reach-of-its-mortgage-origination-and-pricing-data/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P125007 NOREL-3B


40% Jump in Rate-and-Term Refis Drives Overall Lock Growth as Purchase Activity Stalls

Optimal Blue's February 2025 Market Advantage report indicates stabilizing conforming loan share amid refinance growth and sluggish purchase activity

PLANO, Texas, March 11, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its February 2025 Market Advantage mortgage data report, showing a 7% month-over-month increase in mortgage lock volume driven primarily by a surge in refinance activity. Rate-and-term refinances saw the biggest jump, rising nearly 40% as homeowners seized the opportunity to lower their monthly payments. Cash-out refinances also edged higher, while purchase lock activity remained subdued for the second consecutive month.

Optimal Blue’s February 2025 Market Advantage mortgage data report.
Image caption: Optimal Blue’s February 2025 Market Advantage mortgage data report.

“Interest rate improvement, while marginal, is attracting refinance activity as homeowners who bought at higher rates work the numbers and find they can reduce their monthly payments or tap into home equity,” said Brennan O’Connell, director of data solutions at Optimal Blue. “The upcoming homebuying season will reveal whether purchase demand is poised for a rebound or if elevated rates will continue to keep buyers on the sidelines.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock data, include:

  • Refi activity drives higher lock volume: Slightly lower interest rates encouraged a surge of refinance activity that pushed lock volume up 7% month-over-month (MoM). Most of the lift came from rate-and-term refinances, which rose nearly 40% in the improving rate environment; cash-out volume climbed a more modest 4%.
  • Purchase locks continue to drag: Purchase activity remained low for the second straight month, with volume down 5% on a year-over-year (YoY) basis. Purchase lock counts – which control for home price appreciation – were down 9% from the same time in 2024.
  • Conforming loan share stabilizes: Conforming loan volume edged higher for a second month, reaching 52% of total volume after hitting a multi-year low in December. FHA share remained just above 20%. VA share grew slightly to sit at around 11.5%. Non-conforming loan volume – which includes jumbo and non-QM loans – was mostly flat at 15.5%.
  • Spread stays above long-term average: The mortgage rate spread to the 10-year Treasury hovered just above 230 basis points, a roughly 30 bps improvement from the same time last year but still roughly 30 to 40 bps above the long-term average.
  • Refi credit quality ticks higher: The average credit score for cash-out and rate-and-term refinances rose by 2 and 4 points, respectively, to 695 and 732. Meanwhile, the average purchase credit score was flat at 737.
  • Home prices, loan amounts edge higher: The average home purchase price rose from $476.2K in January to $480.2K in February, driving a MoM increase in average loan amount from $376.4K to $380.5K.

The full Market Advantage report, which provides more detailed findings and additional insights into U.S. mortgage market trends, can be viewed at (PDF): https://www2.optimalblue.com/wp-content/uploads/2025/03/OB_MarketAdvantage_MortgageDataReport_Feb2025.pdf

This month’s Market Advantage podcast features a guest interview with CoreLogic Chief Economist Selma Hepp. Access the podcast: https://market-advantage.captivate.fm/listen.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage data report each month to provide early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE – the mortgage industry’s most widely used product, pricing, and eligibility engine – the Market Advantage provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders’ pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/40-jump-in-rate-and-term-refis-drives-overall-lock-growth-as-purchase-activity-stalls/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P124645 NOREL-3B


January Mortgage Lock Data Shows Year-Over-Year Improvement in Refinance Volume Despite Higher Rates

Optimal Blue's January 2025 Market Advantage mortgage data report highlights a softening purchase market, boost in refi demand among elevated rates

PLANO, Texas, Feb. 13, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its January 2025 Market Advantage mortgage data report, revealing a sharp rise in year-over-year (YoY) refinance activity alongside a drop in purchase lock counts. The decline in purchase lock counts marks the lowest January count since Optimal Blue began tracking this data in 2019. Meanwhile, refinance lock volume surged even though the Optimal Blue Mortgage Market Indices (OBMMI) 30-year ticked above 7% for the first time since May.

Optimal Blue's January 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s January 2025 Market Advantage mortgage data report.

“January lock data shows two important ways constrained affordability is impacting the housing finance market. On one hand, refinance activity saw impressive YoY growth despite elevated rates, signaling a growing pool of homeowners with mortgage rates high enough to justify a refinance. On the other hand, purchase lock counts declined YoY, marking the lowest January figures since we began tracking this data in 2019,” said Brennan O’Connell, director of data solutions at Optimal Blue. “A combination of high home prices and rates are curbing purchase activity, while at the same time fueling refinance demand among homeowners who purchased when rates were even higher.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock data, include:

  • Refinance activity surges YoY: Despite rates remaining above 6.8%, total refinance lock volume grew more than 20% YoY for both rate-and-term and cash-out refinances. This indicates that a growing share of borrowers with higher-rate mortgages are finding opportunities to refinance, such as those who purchased between August and November of 2023.
  • Purchase lock volume rises MoM but declines YoY: Purchase lock volume climbed 16% from December, reflecting typical seasonal momentum at the start of the year. However, YoY purchase lock counts – which control for home price appreciation – were down 6%, marking the lowest January figures in six years. This follows a strong end to 2024 and will be an important trend to watch moving forward.
  • Rates hold steady after an early-month jump: The OBMMI 30-year conforming rate started January above 7% but rallied late in the month, ending at 6.84% (up just 1 basis point). Other key rate indices followed a similar pattern, with jumbo rates up 2 bps, FHA rates unchanged, and VA rates up 4 bps.
  • Conforming loan share remains near record lows: After hitting a multi-year low in December, conforming loan share edged up slightly to 51% of total production but remained near historical lows. This was offset by small declines in nonconforming and FHA loan share. VA lending share held steady.
  • Credit scores show mixed trends: The average credit score for purchase and rate-and-term refinance loans rose by 1 point to 738 and 728, respectively. Meanwhile, the average credit score for cash-out refinances declined by 4 points to 693.
  • Home prices increase while loan amounts remain stable: The average home purchase price rose from $473.7K to $476.2K, while the average loan amount dipped slightly from $376.9K to $376.4K.

The full Market Advantage report, which provides more detailed findings and additional insights into U.S. mortgage market trends, can be viewed at (PDF): https://www2.optimalblue.com/wp-content/uploads/2025/02/OB_MarketAdvantage_MortgageDataReport_Jan2025.pdf.

This month’s Market Advantage podcast, which was recorded on-site at the Optimal Blue Summit, features HousingWire Editor in Chief Sarah Wheeler as a guest commentator. Access the podcast: https://market-advantage.captivate.fm/listen.

About the Market Advantage Report:

Optimal Blue issues the Market Advantage mortgage data report each month to provide early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE – the mortgage industry’s most widely used product, pricing, and eligibility engine – the Market Advantage provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders’ pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue:

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/january-mortgage-lock-data-shows-year-over-year-improvement-in-refinance-volume-despite-higher-rates/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P124020 NOREL-3B


Optimal Blue Introduces Seven Major Innovations at Its Inaugural User Summit in San Diego

Company continues its streak of aggressive product innovation and no-cost feature additions

SAN DIEGO, Calif., Feb. 4, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today unveiled a series of new products and features, alongside its major Ask Obi AI assistant announcement, at its Summit user conference in San Diego. These innovation announcements underscore the company’s commitment to delivering high-impact solutions, at no additional cost, that tackle real-world challenges and help lenders maximize profitability.

Optimal Blue logo
Image caption: Optimal Blue.

“Today more than ever, lenders need software and data solutions that empower them to make smarter business decisions and operate with efficiency, and Optimal Blue is demonstrating our commitment to helping them navigate and thrive in this complex and highly regulated environment,” said Erin Wester, chief product officer at Optimal Blue. “The products and features announced at our Optimal Blue Summit are not simply software – they are solutions designed specifically to help lenders maximize their profitability, built based on real feedback gathered from our hundreds of clients. These innovations are a testament to Optimal Blue’s state-of-the-art product, research and development, and engineering teams that go to work for the benefit of our clients every day.”

Major product enhancements announced during the Summit include:

ORIGINATOR ASSISTANT

Originator Assistant is an AI-powered tool in the Optimal Blue PPE that identifies alternate loan scenarios that can produce more competitive pricing, helping loan officers have more strategic discussions with borrowers to win more business. Originator Assistant further amplifies Optimal Blue’s Scenario Optimizer tool, which was introduced last fall to allow clients to run up to three pricing scenarios side-by-side. Originator Assistant examines applicable adjustments, margins, and other price components, and identifies where small loan setup/parameter changes could positively impact pricing. Fully embedded within a loan officer’s workflow, Originator Assistant runs behind-the-scenes as part of every scenario search.

RULES OPTIMIZER

Rules Optimizer is a feature in the Optimal Blue PPE that allows lenders to streamline the rule creation process by creating a single rule and applying it to multiple investor relationships. This gives lenders flexibility to take advantage of both one-to-one and one-to-many investor relationships or custom rule writing. Rules Optimizer also offers change history tracking so users can easily see updated rules and investors/products at a granular level, as well as the ability to schedule run periods in advance to support specials and limited-time promotions. Rules Optimizer is built on top of the Optimal Blue PPE’s system-maintained ratesheet content, which is regarded for its industry-leading accuracy.

RATESHEET TOOL

The Ratesheet Tool is a feature that connects front-end pricing (i.e., origination) with back-end pricing (i.e., secondary) to allow lenders to generate ratesheet pricing with a known margin, accurately. Linking to both the Optimal Blue PPE and the CompassEdge hedging and loan trading platform, the Ratesheet Tool allows secondary users to access a back-end price and deliver a more accurate execution price to originators. The Ratesheet Tool offers a new way for lenders to generate ratesheets with their own proprietary pricing, with precision and accuracy from secondary to origination. This solution showcases a distinct benefit lenders can only realize from working with Optimal Blue, given the company’s end-to-end capital markets platform encompassing both product and pricing and hedging and trading.

CONFIRM ASSISTANT

Confirm Assistant is a feature in the CompassEdge hedging and loan trading platform that reduces both the time and potential for manual errors associated with reading TBA trade confirmation files. The tool uses AI to read files from broker-dealers, parsing the documents into usable formats. With Confirm Assistant, users simply drag and drop confirmation files and approve them without having to manually key in data. This benefits users by reducing manual, time-consuming steps and freeing up staff to focus on more complex trades.

MORTGAGE RATE FUTURES

First announced in November 2024, Optimal Blue has partnered with CME Group, the world’s leading derivatives marketplace, to provide the Optimal Blue Mortgage Market Index (OBMMI) as the foundation for CME Group’s new Mortgage Rate futures. Launched on Jan. 13, 2025, Mortgage Rate futures are cash-settled contracts that provide direct exposure to the latest primary mortgage rate available to borrowers, giving mortgage originators an additional instrument to hedge pipeline and servicing risk. The contracts are the first-ever to be based on the 30-Year Fixed Rate Conforming OBMMI, which is designed for IOSCO compliance and tracks real-time rate lock data from more than one-third of U.S. residential mortgage originations.

SOLUTION CENTER

The Solution Center is a partner marketplace within Optimal Blue’s Comergence platform that expands revenue opportunities for mortgage lenders and investors and third-party partners and vendors. The Solution Center provides a platform where users can sell products and services through a two-sided marketplace of vetted integration partners. It supports more streamlined vendor communication, and the Solution Center Academy provides a resource for asynchronous training, helping investors promote strategic relationships, as well as required trainings, for their third-party originators.

ASK OBI

Finally, as announced earlier today, Ask Obi is Optimal Blue’s new standalone AI assistant that gives executives instant, interactive access to granular data insights and trends to improve business decisions. Ask Obi gives lenders the power to view their operations holistically with data aggregation across Optimal Blue’s comprehensive capital markets platform, reaching from loan origination data through hedging and trading.

Optimal Blue’s Summit user conference features multi-track sessions exploring AI and automation trends, profitability strategies, market insights, and more, led by leading economists, policymakers, and lenders, as well as the company’s own subject matter experts.

About Optimal Blue:

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-introduces-seven-major-innovations-at-its-inaugural-user-summit-in-san-diego/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P123799 NOREL-3B


Optimal Blue Announces Ask Obi, an AI Assistant to Provide Mortgage Lending Executives With Real-Time Business Insights

Conversational generative AI chat assistant to provide easy-to-understand, interactive insights and graphical representations to help lenders maximize profitability

SAN DIEGO, Calif., Feb. 4, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced Ask Obi, an AI assistant designed to provide mortgage lending executives with instant, actionable insights from their Optimal Blue products and data. Unveiled during Optimal Blue’s inaugural Summit user conference in San Diego, Ask Obi gives lenders the power to view their operations holistically with data aggregation across Optimal Blue’s comprehensive capital markets platform.

Optimal Blue logo
Image caption: Optimal Blue.

Ask Obi enables executives to inquire about intricate profitability metrics with simple, conversational queries – such as, “What markets had the greatest change in average margins from Q3 2024 to Q4 2024?” or “Which loan officers issued the most concessions over the second week of January 2025?” – and get easy-to-understand answers at a granular level to improve strategic decision-making.

“Our clients operate in a time when speed and accuracy matters, so having to wait for reports to be generated – only to then spend more time poring over those reports to get to the insights needed to make decisions – doesn’t make sense,” said Joe Tyrrell, CEO of Optimal Blue. “With Ask Obi, those hours of generating, compiling, and analyzing reports are replaced with accurate, real-time, personalized information, designed specifically for decision-makers, by delivering the data that matters most to their profitability. While other companies are talking about AI, but in reality are still trying to catch up to our accuracy and core capabilities, Optimal Blue has already embraced generative AI to solve real operational and capital markets challenges, all at no additional cost to our clients.”

“Ask Obi demonstrates the unique value clients realize by working with Optimal Blue, a provider of comprehensive capital markets technology,” said Erin Wester, chief product officer of Optimal Blue. “Through the power of generative AI, users can have an interactive conversation to better understand the data that drives their business. In contrast to other tools that may require filters and manual selections, Ask Obi is designed for ease of use and conversational interactions, while conveniently building off a user’s previous inquiries and suggesting preloaded questions.”

Available to Optimal Blue clients for beta testing later this month, Ask Obi offers complete access to a lender’s PPE data, with development work underway to expand access across Optimal Blue’s complete capital markets platform. This initiative aligns with Optimal Blue’s larger vision to deliver comprehensive interoperability among its end-to-end capital markets products, allowing clients to benefit from synthesized data and machine learning for enhanced margin management and profitability oversight.

Ask Obi is one of several innovations the company announced at its Summit, demonstrating its commitment to continuous investment in its products to help its clients maximize lending profitability.

About Optimal Blue:

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

LOGO link for media: https://www.Send2Press.com/300dpi/14-0625-s2p-optimal-blue-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-announces-ask-obi-an-ai-assistant-to-provide-mortgage-lending-executives-with-real-time-business-insights/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P123793 NOREL-3B


December Mortgage Lock Data Reveals Year-Over-Year Increases Across All Loan Types Despite Seasonal Downturn

Optimal Blue's December 2024 Market Advantage report highlights annual mortgage production gains and record low conforming loan share

PLANO, Texas, Jan. 14, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its December 2024 Market Advantage mortgage data report, showcasing year-over-year (YoY) growth in mortgage activity, even as seasonal trends led to a month-over-month (MoM) decline in rate lock volumes. Overall, December mortgage lock volume was up 26% YoY, driven by an 18% increase in purchase locks, a 43% rise in cash-out refinances, and an 82% jump in rate-and-term refinances.

Optimal Blue December 2024 Market Advantage report
Image caption: Optimal Blue December 2024 Market Advantage report.

“December’s data illustrates how the market can adapt to shifting conditions,” said Brennan O’Connell, director of data solutions at Optimal Blue. “While a seasonal dip was expected, the year-over-year growth reflects resilience and an increasing demand for refinance opportunities driven by rate adjustments. Notably, conforming loan share has hovered around historic lows for the past five months, hitting 51% last month. This trend illustrates how borrowers are relying increasingly on government and non-conforming loans to finance in a challenging market.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock data, include:

  • Rates fluctuate, ending December higher: After initial declines, rates rose throughout the month. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming rate ended December at 6.83%, up 16 bps from the end of November. FHA and VA rates followed suit, rising 14 bps and 18 bps, respectively. Jumbo rates fell slightly, ending just below 7%.
  • Refinance activity spikes: The share of refinance locks climbed to 24%, the highest since September. Rate-and-term refinances surged 33% MoM, while cash-out refinances saw a 3% decline. Purchase volumes dropped 13% MoM, in line with seasonal norms, while cash-out refinances decreased 3%.
  • Production mix shifts continue: The conforming loan share dropped another 1.5% MoM to 51%, the lowest figure since Optimal Blue began reporting lock data in January 2018, marking continued movement away from GSE-eligible products. FHA, VA, and non-conforming loans gained ground, with FHA locks rising to 21%, VA at nearly 11.5%, and non-conforming loans at 16%.
  • Purchase credit quality hits seven-year high: Average homebuyer credit scores were higher each month in 2024 than the previous 72 months.
  • MoM credit trends are stable: Average credit scores for purchase and rate-and-term refinance locks fell by 2 points to 737 and 727, respectively. Cash-out refinance scores rose slightly, increasing by 2 points to 697.
  • Loan amounts plateau as home prices decline: The average loan amount rose by $500 to $376.9K, while average home purchase prices dropped $4.1K to $473.7K.

The full Market Advantage report, which provides more detailed findings and additional insights into U.S. mortgage market trends, can be viewed at: https://www2.optimalblue.com/wp-content/uploads/2025/01/OB_MarketAdvantage_MortgageDataReport_Dec2024.pdf

This month’s Market Advantage podcast features Shant Banosian, executive vice president of sales at Rate, as a guest commentator. Access the podcast: https://market-advantage.captivate.fm/listen.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage data report each month to provide early insight into U.S. mortgage trends. Leveraging lender rate lock data from the Optimal Blue PPE – the mortgage industry’s most widely used product, pricing, and eligibility engine – the Market Advantage provides a view of early-stage origination activity. Unlike self-reported survey data, mortgage lock data is direct-source data that accurately reflects the in-process loans in lenders’ pipelines.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue effectively bridges the primary and secondary mortgage markets to deliver the industry’s only end-to-end capital markets platform. The company helps lenders of all sizes and scopes maximize profitability and operate efficiently so they can help American borrowers achieve the dream of homeownership. Through innovative technology, a network of interconnectivity, rich data insights, and expertise gathered over more than 20 years, Optimal Blue is an experienced partner that, in any market environment, allows lenders to optimize their advantage from pricing accuracy to margin protection, and every step in between. To learn more, visit https://OptimalBlue.com/.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/december-mortgage-lock-data-reveals-year-over-year-increases-across-all-loan-types-despite-seasonal-downturn/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P123332 NOREL-3B