Tag Archives: Home Mortgage Disclosure Act

iEmergent releases 2024 HMDA insights: IMBs dominate, refinances rise, equity gaps persist

Data insights now available in Mortgage MarketSmart highlight rising refi activity, IMB dominance and persistent equity gaps

DES MOINES, Iowa, April 29, 2025 (SEND2PRESS NEWSWIRE) — iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, has released its analysis of 2024 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. The insights, shared by iEmergent CEO Laird Nossuli, highlight a modest market recovery from 2023 alongside deepening disparities in borrower outcomes and a reshuffling of lender dynamics.
iEMERGENT
Image caption: iEmergent.

TOP TAKEAWAYS FROM 2024 HMDA DATA:

  1. Mortgage lending volume rebounded slightly, driven by a resurgence in refinancing.
    In 2024, U.S. lenders originated a combined 4.9 million loans totaling $1.67 trillion in dollar volume across purchase and refi, up from $1.45 trillion in 2023. Refinances surged 63% by dollar volume to $393.7 billion and accounted for nearly a quarter (23.5%) of purchase and refi dollars, up from 16.7% in 2023.
  2. Independent mortgage banks (IMBs) extended their lead.
    IMBs originated 65.4% of all purchase and refinance loans in 2024, up from 61.3% in 2023. They also claimed 16 of the top 25 spots by dollar volume and 17 by loan count, underscoring their continued role as the primary engine of mortgage lending despite representing just 18% of reporting institutions.
  3. Borrowers are taking out bigger loans, amplifying affordability concerns.
    The average size of purchase and refinance loans grew in 2024, reaching $339,903 (up from $323,282 in 2023). Rising home prices and interest rates continue to widen the gap between what buyers can afford and what they must borrow.
  4. Denial rates ticked up, with notable differences by lender type.
    People of color households made up a growing share of applicants in 2024, but approval rates remained unequal. Black borrowers, for instance, faced an 18% denial rate for purchase loans compared to 9% for non-Hispanic white applicants. While banks and credit unions lowered their denial rates year over year, IMBs saw a slight increase—contributing to uneven outcomes, since IMBs originated the majority of loans. Debt-to-income (DTI) ratios remained the most common denial reason across all racial and ethnic groups.​
  5. Dominance by leading lenders continues to intensify.
    The top five lenders accounted for nearly 20% of all loans and dollars originated in 2024, a notable uptick from 2023. This growing market concentration signals intensifying consolidation and competition among top-tier lenders.

“2024 brought modest recovery to the mortgage market, but also highlighted some of the structural inequities and concentration trends that shape lending outcomes today,” said Nossuli. “iEmergent’s Mortgage MarketSmart puts this data into context—geographically, demographically, and competitively—so lenders can find smarter ways to grow and serve their markets.”

LENDERS CAN NOW BENCHMARK PERFORMANCE AND PLAN FOR GROWTH

The integration of 2024 HMDA data into Mortgage MarketSmart allows lenders to benchmark their performance against peers across categories such as:

  • Purchase and refi loan volumes (units and dollars)
  • Borrower race and ethnicity
  • Loan type and size
  • Borrower income levels
  • Denial reasons by demographic group

With side-by-side comparisons of HMDA data, historical trends and forward-looking forecasts, Mortgage MarketSmart empowers lenders to identify gaps, meet Community Reinvestment Act (CRA) obligations and reach underserved markets.

To explore 2024 HMDA insights in Mortgage MarketSmart, request a demo at https://www.iemergent.com/.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com/.

Tags: @iEmergent #HMDA #housing #mortgage #data

Media Kit (PDF):
https://www.iemergent.com/docs/default-source/default-document-library/presskit_digitallinked.pdf

NEWS SOURCE: iEmergent


This press release was issued on behalf of the news source (iEmergent), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/iemergent-releases-2024-hmda-insights-imbs-dominate-refinances-rise-equity-gaps-persist/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P125811 NOREL-3B


iEmergent’s 2024-2026 U.S. Mortgage Origination Forecast is now available in Mortgage MarketSmart

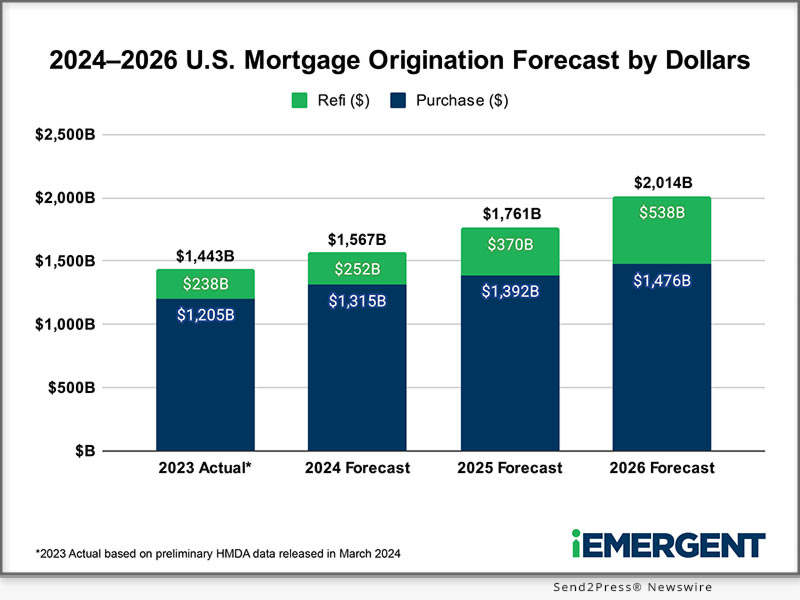
DES MOINES, Iowa /ScoopCloud/ -- iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the availability of its 2024-2026 U.S. Mortgage Origination Forecast. Updated to reflect preliminary 2023 Home Mortgage Disclosure Act (HMDA) data released by the Federal Financial Institutions Examination Council in March, iEmergent's latest projections call for modest growth in purchase originations and a gradual increase in refinance loan units and dollars as a percentage of total originations.

According to iEmergent Chief of Forecasting Mark Watson, persistent economic trends - including inflation, real GDP growth, a strong labor market and tight Federal Reserve monetary policy - will continue to dampen the mortgage origination market for the next three years:

* 2024: Although purchase dollar volume is expected to increase by about 9% in 2024, most of the volume gain will be attributable to larger average loan sizes rather than significant growth in loan count. Refinances are forecast to reach 18% of total mortgage originations, only slightly more than their record low of 17% in 2023.

* 2025: By 2025, deceleration and, ultimately, a mild decline in GDP growth should help reduce long-term interest rates and soften home prices, leading to slightly higher mortgage origination levels. Refi units are anticipated to grow 33% (albeit from historically low levels) on a year-over-year basis.

* 2026: By 2026, total U.S. mortgage origination volume is expected to exceed the $2 trillion mark for the first time since 2022 as refinances continue to recover share in both loan units and dollars.

"The American economy has proven surprisingly resilient, and that very resiliency has kept interest rates higher than anticipated for longer than expected. When you factor in an affordability crisis and an acute housing shortage, it's no wonder origination volumes continue to suffer," said iEmergent CEO Laird Nossuli. "As economic growth slows over the next couple of years, we could finally see some improvement, provided inventory scarcity is addressed. As markets recover, origination opportunities will be unevenly distributed, making our census-level forecasts a critical tool for shaping lenders' growth strategies."

The 2024-2026 forecast is available now in iEmergent's Mortgage MarketSmart platform, where users can map future lending opportunities at the census tract level and overlay them with historical loan production data, real estate agent and property listing intelligence, household demographic and income insights, community points of interest and more.

Read Mark Watson's latest blog for more detailed analysis and commentary on the forecast.

Methodology

For more than two decades, iEmergent has been predicting mortgage market trends with a level of precision that surpasses even the industry's most trusted forecasts from the Mortgage Bankers Association, Freddie Mac and Fannie Mae. In fact, in more than half of the nation's 73,057 census tracts, iEmergent's U.S. Mortgage Origination Forecast has proven accurate to within 10 loans.

iEmergent's proprietary forecasting method is a hybrid of several traditional demand forecast models. Many variables go into these forecasts, but there are two fundamental elements: first, the Purchase Mortgage Generation Rate (PMGR), which is the rate at which an individual market produces purchase mortgages. Second, the homebuyer pool: the number of households that are ready, willing, and able to buy a home. By evaluating the relationship between each census tract's homebuyer pool and PMGR, probability theory can be applied to estimate the number of purchase mortgage loans and dollars that will be originated in that market.

Read more about iEmergent's approach to forecasting here.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com/.

News from IEmergent

iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the availability of its 2024-2026 U.S. Mortgage Origination Forecast. Updated to reflect preliminary 2023 Home Mortgage Disclosure Act (HMDA) data released by the Federal Financial Institutions Examination Council in March, iEmergent's latest projections call for modest growth in purchase originations and a gradual increase in refinance loan units and dollars as a percentage of total originations.

Related link: https://www.iemergent.com

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

iEmergent shares top takeaways from 2022 HMDA data

DES MOINES, Iowa /ScoopCloud/ -- iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the immediate availability of 2022 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. To celebrate providing lenders with early access to HMDA reporting, iEmergent CEO Laird Nossuli shared summary observations drawn from the loan-level origination data.

Top takeaways from 2022 HMDA data:

1. The last 12 months saw the U.S. mortgage market sliced in half.

While it comes as no surprise that lenders originated far fewer loans in 2022 than in 2021, HMDA data illuminates just how steep the dropoff was. Purchase units fell 19% and refinance (refi) units fell 70% year over year. Altogether, the market saw a combined 50.6% drop in purchase and refi units.

2. IMBs continue to carry a heavy load.

In 2022, independent mortgage banks (IMBs) represented just 20% of all U.S. lending institutions, yet they accounted for 58% of purchase and refi units and 56% of purchase and refi dollars originated. By comparison, credit unions were 33% of all lending institutions but represented just 9% of purchase and refi units and 7% of purchase and refi dollars. Banks were 47% of all lending institutions but represented 34% of purchase and refi units and 38% of purchase and refi dollars.

3. Credit unions are still playing catch-up in the pivot to purchase.

Purchase originations dominated in 2022, accounting for 62% of purchase and refi units and 68% of purchase and refi dollar volume industry-wide. But while banks and IMBs have crossed the threshold from mostly-refi to mostly-purchase, refi transactions still accounted for a majority (55%) of loan units originated by credit unions.

4. Select lenders are holding their own in a challenging market.

In 2022's contracting mortgage market, some lenders managed to turn lemons into lemonade. Seven of the year's top overall lenders by unit volume were new to the top 20, as were eight of the year's top overall lenders by dollar volume. Slicing the data by loan purpose shakes up the top 20 considerably, with IMBs taking 14 of the top 20 spots for purchase originations, IMBs and banks splitting the top 20 almost evenly for refi originations, and banks and credit unions dominating the top 20 for home improvement loans.

5. Buyers are borrowing more than ever.

The average size of a purchase loan increased 7.7% year over year from $337,813 in 2021 to $363,978 in 2022, outpacing overall inflation (*SEE NOTE 1) and exacerbating challenges to housing accessibility and affordability.

"In the current mortgage market, lenders face adversity and opportunity in almost equal measure - a story that is borne out in the latest HMDA data," said Nossuli. "iEmergent's Mortgage MarketSmart brings this story to life and puts it into actionable context with rich maps and forecasts that quantify a lender's market gaps all the way down to the neighborhood level."

HMDA data shows lenders how they stack up against peers

The integration of 2022 HMDA data into Mortgage MarketSmart, iEmergent's industry-first market visualization platform, makes it easy for lenders to compare their performance against competitors' across numerous categories including:

* Purchase origination units and dollars
* Refi origination units and dollars
* Borrower race
* Borrower ethnicity
* Loan type (conventional, jumbo, government)
* Borrower income (low, moderate, middle, upper)

By blending current HMDA data with historical market analysis and highly reliable forecasting, Mortgage MarketSmart gives lenders everything they need to quantify and act on market growth opportunities, including diverse lending and recruiting strategies that support financial institutions' fair lending and Community Reinvestment Act (CRA) obligations. In fact, a comparison of iEmergent's U.S. Mortgage Origination Forecast against HMDA actuals shows that iEmergent predicted overall 2022 purchase originations with an accuracy over 99%.

To subscribe to Mortgage MarketSmart and gain access to 2022 HMDA data, request a demo.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change.

For more information, visit https://www.iemergent.com.

CITATION:

*NOTE 1: https://www.bls.gov/opub/ted/2023/consumer-price-index-2022-in-review.htm#:~:text=Consumer%20prices%20for%20all%20items,December%202021%20to%20December%202022

News from IEmergent

iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the immediate availability of 2022 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. To celebrate providing lenders with early access to HMDA reporting, iEmergent CEO Laird Nossuli shared summary observations drawn from the loan-level origination data.

Related link: https://www.iemergent.com

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

ScoopCloud Newswire

IDS Updates Borrower Data Collection Fields, Supports MISMO v 3.4 for HMDA Compliance

SALT LAKE CITY, Utah /ScoopCloud/ -- Mortgage document preparation vendor International Document Services, Inc. (IDS), announced it has updated its flagship mortgage doc prep platform idsDoc to include new borrower data collection fields that support compliance with the 2018 changes to Home Mortgage Disclosure Act (HMDA) reporting.

"Although lenders are not required to collect expanded HMDA data until 2018, they can begin gathering this information in 2017," said Mark Mackey, vice president of IDS. "As such, IDS chose to update idsDoc to include the new data fields and support early collection of revised HMDA data a full year before it was required."

"This gives our clients the opportunity to familiarize themselves with how these changes may affect the loan application process and adjust accordingly to be ready for the January 2018 implementation date," Mackey said.

To further aid clients' efforts in complying with the Consumer Financial Protection Bureau's (CFPB) changes to HMDA, IDS has also updated its system to include the most recent reference model from the Mortgage Industry Standards Maintenance Organization (MISMO). Known as MISMO Version 3.4, this set of standards was designed to support the changes to HMDA, along with the forthcoming Uniform Loan Application Dataset (ULAD) from the government-sponsored enterprises (GSEs) and the TILA-RESPA Integrated Disclosures (TRID) regulations. IDS currently supports MISMO v 3.3.0, 3.3.1 and 3.4 and will support Version 3.5, which is in development.

"IDS has fully supported the GSEs' and MISMO's common goal of enhancing data quality and bringing standardization to the mortgage industry from day one," Mackey said. "The benefits of operating from a shared data standard cannot be overstated, and we have made a considerable investment to ensure our clients have the ability to deliver loan data in accordance with GSE requirements using the latest MISMO standards."

About IDS, Inc.:

IDS, a Reynolds and Reynolds company, was founded in 1986 in Salt Lake City, Utah, and is a nationwide provider of mortgage documents and compliance. IDS services include electronic signatures, closing documents, initial disclosures, document fulfillment and integration with leading loan origination systems and eClosing platforms. The IDS flagship doc prep solution, idsDoc, is recognized in the industry for its ability to be customized to meet specific lender needs, particularly in regards to major industry compliance changes. More information: http://info.idsdoc.com/.

Mortgage document preparation vendor International Document Services, Inc. (IDS), announced it has updated its flagship mortgage doc prep platform idsDoc to include new borrower data collection fields that support compliance with the 2018 changes to Home Mortgage Disclosure Act (HMDA) reporting.

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of the Neotrope® News Network - all rights reserved.