Tag Archives: Mortgage MarketSmart

iEmergent releases 2025 HMDA insights: volume rebounds, but the mortgage market grows more concentrated

Data insights now available in Mortgage MarketSmart show refinance-driven growth amid rising loan sizes

DES MOINES, Iowa, April 29, 2026 (SEND2PRESS NEWSWIRE) — iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, has released its analysis of 2025 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. Presented by iEmergent CEO Laird Nossuli, the findings point to a market that is regaining momentum after a prolonged downturn, with total volume increasing in 2025. That recovery, however, is uneven. Growth is being driven by refinancing activity and larger loan balances, while competitive gains remain concentrated among a relatively small group of lenders.
iEmergent releases 2025 HMDA insights: volume rebounds, but the mortgage market grows more concentrated
Image caption: iEmergent releases 2025 HMDA insights: volume rebounds, but the mortgage market grows more concentrated.

Top takeaways from 2025 HMDA data:

  1. Refinance activity drove a disproportionate share of volume growth.
    S. lenders originated approximately 6.75 million loans totaling $2.12 trillion in 2025, up from $1.82 trillion in 2024. Refinances accounted for a disproportionate share of that growth, rising to $610.4 billion and representing 29% of total lending volume, compared to 22% the prior year. This shift indicates that recent volume gains are being fueled more by rate-driven activity than by underlying purchase demand.
  2. IMBs extended their lead in both share and growth capture.
    Independent mortgage banks (IMBs) increased their share of originations to 57.8% in 2025, up from 55.8% in 2024, and accounted for 61.9% of total lending volume. Notably, they captured $193 billion of the market’s $303 billion year-over-year growth, far outpacing depository institutions. IMBs also dominated lender rankings, representing 18 of the top 25 institutions by both loan count and dollar volume.
  3. Rising loan sizes continue to pressure affordability.
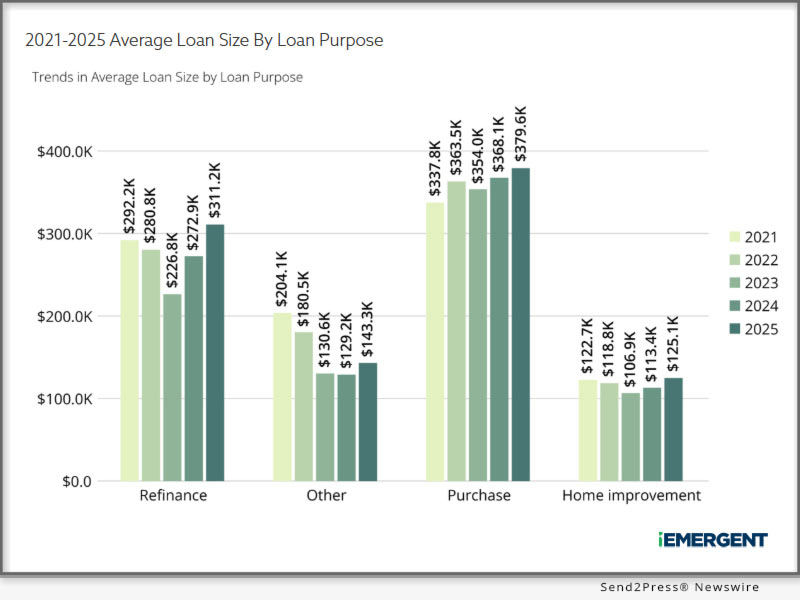
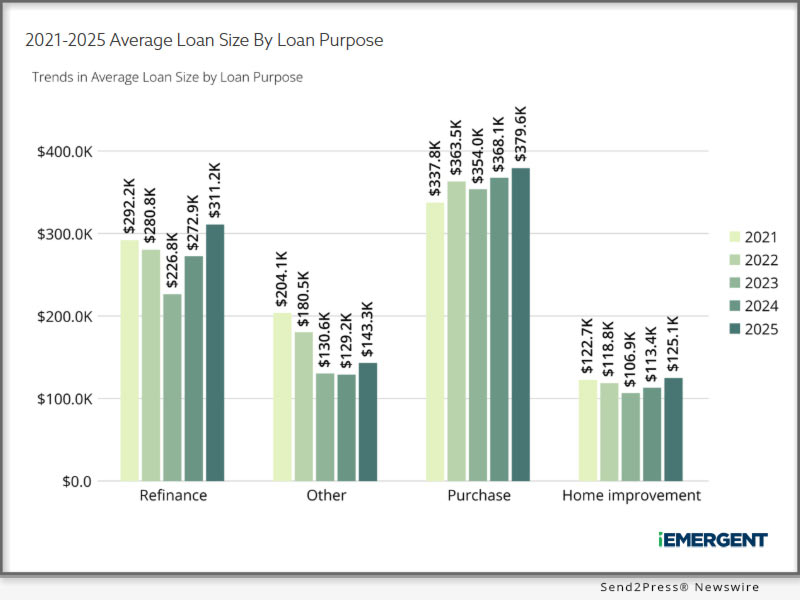
    Average loan sizes increased across both purchase and refinance segments, with purchase loans rising to $379,600 (from $368,100) and refinance loans to $311,200 (from $272,900). These increases align with persistent inventory constraints and elevated home prices, which are pushing borrowers toward higher balances and further limiting access for more price-sensitive buyers.
  4. Denial rates edged down, but elevated fallout points to ongoing borrower friction.
    While denial rates declined modestly, overall application fallout remained high. Approximately 40% of applications from non-Hispanic White borrowers did not result in funded loans, while fallout exceeded 50% for Black, Native American/Alaskan and Pacific Islander applicants. Increased withdrawals and incomplete applications suggest that affordability constraints and valuation challenges are continuing to disrupt borrower progression through the origination process.
  5. Market concentration remains high, with production concentrated among a small group of lenders.
    The top five lenders accounted for just over 20% of both loan count and total volume in 2025. More broadly, only 47 lenders—roughly 1% of all institutions—originated half of total mortgage volume. This concentration underscores a competitive environment in which scale and operational efficiency are increasingly determining market share outcomes.
  6. Loan purpose mix varies significantly by geography, reinforcing the need for localized strategy.
    Purchase-driven markets in the Sun Belt, such as Houston (71% purchase) and Austin (68% purchase), stand in contrast to coastal markets like Los Angeles (40% refinance) and San Diego (38% refinance). These differences highlight the importance of market-specific strategy, as performance in purchase-heavy regions depends more on execution and affordability positioning than on cyclical refinance opportunities

“2025 HMDA data shows a market that is improving, but not uniformly,” said Nossuli. “Growth is being driven by specific products, borrower segments and geographies, while competitive gains are concentrated among lenders with the scale and strategy to capture them. Understanding where those opportunities exist is critical for lenders planning their next phase of growth.”

Lenders can now benchmark performance and identify growth opportunities
The integration of 2025 HMDA data into Mortgage MarketSmart allows lenders to benchmark their performance against peers across categories such as:

  • Purchase and refi loan volume (units and dollars)
  • Borrower race and ethnicity
  • Loan type and size
  • Borrower income levels
  • Denial reasons by demographic group

With side-by-side comparisons of HMDA data, historical trends and forward-looking forecasts, Mortgage MarketSmart empowers lenders to identify gaps, meet Community Reinvestment Act (CRA) obligations and reach underserved markets.

To explore 2025 HMDA insights in Mortgage MarketSmart, request a demo at https://www.iemergent.com.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com.

Tags: @iEmergent

Media Kit:
https://www.iemergent.com/docs/default-source/default-document-library/presskit_digitallinked.pdf

NEWS SOURCE: iEmergent


This press release was issued on behalf of the news source (iEmergent), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/iemergent-releases-2025-hmda-insights-volume-rebounds-but-the-mortgage-market-grows-more-concentrated/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P134985 NOREL-3B


iEmergent’s 2024-2026 U.S. Mortgage Origination Forecast is now available in Mortgage MarketSmart

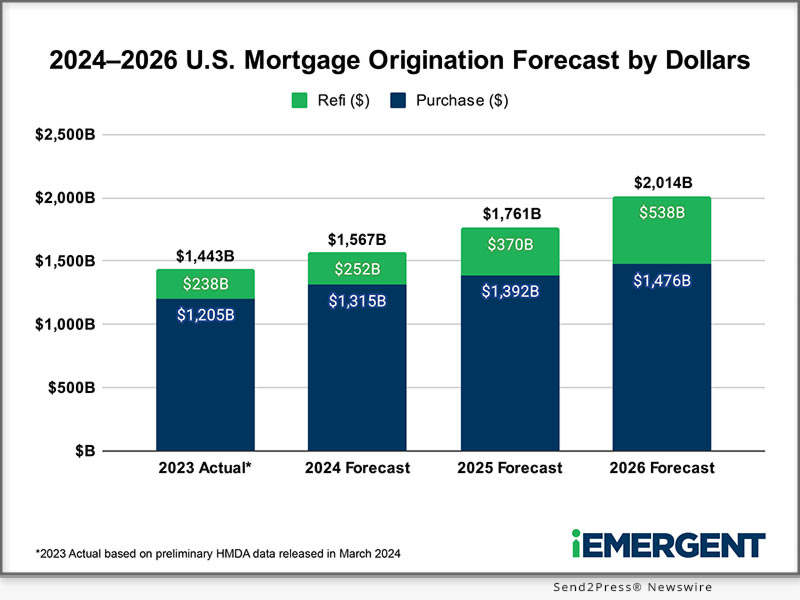
DES MOINES, Iowa /ScoopCloud/ -- iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the availability of its 2024-2026 U.S. Mortgage Origination Forecast. Updated to reflect preliminary 2023 Home Mortgage Disclosure Act (HMDA) data released by the Federal Financial Institutions Examination Council in March, iEmergent's latest projections call for modest growth in purchase originations and a gradual increase in refinance loan units and dollars as a percentage of total originations.

According to iEmergent Chief of Forecasting Mark Watson, persistent economic trends - including inflation, real GDP growth, a strong labor market and tight Federal Reserve monetary policy - will continue to dampen the mortgage origination market for the next three years:

* 2024: Although purchase dollar volume is expected to increase by about 9% in 2024, most of the volume gain will be attributable to larger average loan sizes rather than significant growth in loan count. Refinances are forecast to reach 18% of total mortgage originations, only slightly more than their record low of 17% in 2023.

* 2025: By 2025, deceleration and, ultimately, a mild decline in GDP growth should help reduce long-term interest rates and soften home prices, leading to slightly higher mortgage origination levels. Refi units are anticipated to grow 33% (albeit from historically low levels) on a year-over-year basis.

* 2026: By 2026, total U.S. mortgage origination volume is expected to exceed the $2 trillion mark for the first time since 2022 as refinances continue to recover share in both loan units and dollars.

"The American economy has proven surprisingly resilient, and that very resiliency has kept interest rates higher than anticipated for longer than expected. When you factor in an affordability crisis and an acute housing shortage, it's no wonder origination volumes continue to suffer," said iEmergent CEO Laird Nossuli. "As economic growth slows over the next couple of years, we could finally see some improvement, provided inventory scarcity is addressed. As markets recover, origination opportunities will be unevenly distributed, making our census-level forecasts a critical tool for shaping lenders' growth strategies."

The 2024-2026 forecast is available now in iEmergent's Mortgage MarketSmart platform, where users can map future lending opportunities at the census tract level and overlay them with historical loan production data, real estate agent and property listing intelligence, household demographic and income insights, community points of interest and more.

Read Mark Watson's latest blog for more detailed analysis and commentary on the forecast.

Methodology

For more than two decades, iEmergent has been predicting mortgage market trends with a level of precision that surpasses even the industry's most trusted forecasts from the Mortgage Bankers Association, Freddie Mac and Fannie Mae. In fact, in more than half of the nation's 73,057 census tracts, iEmergent's U.S. Mortgage Origination Forecast has proven accurate to within 10 loans.

iEmergent's proprietary forecasting method is a hybrid of several traditional demand forecast models. Many variables go into these forecasts, but there are two fundamental elements: first, the Purchase Mortgage Generation Rate (PMGR), which is the rate at which an individual market produces purchase mortgages. Second, the homebuyer pool: the number of households that are ready, willing, and able to buy a home. By evaluating the relationship between each census tract's homebuyer pool and PMGR, probability theory can be applied to estimate the number of purchase mortgage loans and dollars that will be originated in that market.

Read more about iEmergent's approach to forecasting here.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com/.

News from IEmergent

iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the availability of its 2024-2026 U.S. Mortgage Origination Forecast. Updated to reflect preliminary 2023 Home Mortgage Disclosure Act (HMDA) data released by the Federal Financial Institutions Examination Council in March, iEmergent's latest projections call for modest growth in purchase originations and a gradual increase in refinance loan units and dollars as a percentage of total originations.

Related link: https://www.iemergent.com

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

iEmergent shares top takeaways from 2022 HMDA data

DES MOINES, Iowa /ScoopCloud/ -- iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the immediate availability of 2022 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. To celebrate providing lenders with early access to HMDA reporting, iEmergent CEO Laird Nossuli shared summary observations drawn from the loan-level origination data.

Top takeaways from 2022 HMDA data:

1. The last 12 months saw the U.S. mortgage market sliced in half.

While it comes as no surprise that lenders originated far fewer loans in 2022 than in 2021, HMDA data illuminates just how steep the dropoff was. Purchase units fell 19% and refinance (refi) units fell 70% year over year. Altogether, the market saw a combined 50.6% drop in purchase and refi units.

2. IMBs continue to carry a heavy load.

In 2022, independent mortgage banks (IMBs) represented just 20% of all U.S. lending institutions, yet they accounted for 58% of purchase and refi units and 56% of purchase and refi dollars originated. By comparison, credit unions were 33% of all lending institutions but represented just 9% of purchase and refi units and 7% of purchase and refi dollars. Banks were 47% of all lending institutions but represented 34% of purchase and refi units and 38% of purchase and refi dollars.

3. Credit unions are still playing catch-up in the pivot to purchase.

Purchase originations dominated in 2022, accounting for 62% of purchase and refi units and 68% of purchase and refi dollar volume industry-wide. But while banks and IMBs have crossed the threshold from mostly-refi to mostly-purchase, refi transactions still accounted for a majority (55%) of loan units originated by credit unions.

4. Select lenders are holding their own in a challenging market.

In 2022's contracting mortgage market, some lenders managed to turn lemons into lemonade. Seven of the year's top overall lenders by unit volume were new to the top 20, as were eight of the year's top overall lenders by dollar volume. Slicing the data by loan purpose shakes up the top 20 considerably, with IMBs taking 14 of the top 20 spots for purchase originations, IMBs and banks splitting the top 20 almost evenly for refi originations, and banks and credit unions dominating the top 20 for home improvement loans.

5. Buyers are borrowing more than ever.

The average size of a purchase loan increased 7.7% year over year from $337,813 in 2021 to $363,978 in 2022, outpacing overall inflation (*SEE NOTE 1) and exacerbating challenges to housing accessibility and affordability.

"In the current mortgage market, lenders face adversity and opportunity in almost equal measure - a story that is borne out in the latest HMDA data," said Nossuli. "iEmergent's Mortgage MarketSmart brings this story to life and puts it into actionable context with rich maps and forecasts that quantify a lender's market gaps all the way down to the neighborhood level."

HMDA data shows lenders how they stack up against peers

The integration of 2022 HMDA data into Mortgage MarketSmart, iEmergent's industry-first market visualization platform, makes it easy for lenders to compare their performance against competitors' across numerous categories including:

* Purchase origination units and dollars
* Refi origination units and dollars
* Borrower race
* Borrower ethnicity
* Loan type (conventional, jumbo, government)
* Borrower income (low, moderate, middle, upper)

By blending current HMDA data with historical market analysis and highly reliable forecasting, Mortgage MarketSmart gives lenders everything they need to quantify and act on market growth opportunities, including diverse lending and recruiting strategies that support financial institutions' fair lending and Community Reinvestment Act (CRA) obligations. In fact, a comparison of iEmergent's U.S. Mortgage Origination Forecast against HMDA actuals shows that iEmergent predicted overall 2022 purchase originations with an accuracy over 99%.

To subscribe to Mortgage MarketSmart and gain access to 2022 HMDA data, request a demo.

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change.

For more information, visit https://www.iemergent.com.

CITATION:

*NOTE 1: https://www.bls.gov/opub/ted/2023/consumer-price-index-2022-in-review.htm#:~:text=Consumer%20prices%20for%20all%20items,December%202021%20to%20December%202022

News from IEmergent

iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the immediate availability of 2022 Home Mortgage Disclosure Act (HMDA) data in Mortgage MarketSmart. To celebrate providing lenders with early access to HMDA reporting, iEmergent CEO Laird Nossuli shared summary observations drawn from the loan-level origination data.

Related link: https://www.iemergent.com

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.

iEmergent appoints Chris Richey as Chief Analytics Officer

DES MOINES, Iowa /ScoopCloud/ -- iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the appointment of Chris Richey as chief analytics officer. In this role, Richey will oversee and expand upon iEmergent's data analytics capabilities, which help mortgage lenders identify gaps in sales coverage and effectively expand into new markets.

Richey, who first joined iEmergent in a consulting capacity in 2016, has been instrumental in building out the data and information technology (IT) frameworks supporting the firm's external Mortgage MarketSmart and internal business intelligence (BI) platforms. With this infrastructure in place, Richey will next turn his attention to enhancing the analytics engine and statistical models that power iEmergent's market-leading data insights.

"Chris' combination of mathematics, economics and IT expertise is quite rare, but what's even more exceptional is his commitment to applying those skills to affect positive change," said iEmergent CEO Laird Nossuli. "For years, iEmergent's data has pointed to diversity in lending as not only the right thing to do for our communities, but also a business imperative for lenders. Chris will play an integral role in advancing our ability to put this imperative into context for individual lenders so they can turn insight into action and measurable growth."

Before joining iEmergent, Richey was a data analyst in the IT business unit of a Fortune 100 government contractor. His work synthesizing and analyzing some of the largest healthcare databases in the United States helped guide Medicare's implementation of regulatory programs designed to improve the quality and lower the cost of healthcare for millions of Americans. Later, during the COVID pandemic, Richey was part of a task force that tracked nursing home outbreaks of COVID-19 and applied data sourced from multiple agencies to coordinate the delivery of training, supplies and vaccinations.

Earlier in his career, Richey worked as a quantitative analyst within the financing arm of a Fortune 100 equipment manufacturer, where he built statistical models for managing credit risk, conducted regulatory compliance stress testing and leveraged his background in IT to create a unified framework for consolidating and reporting data across the global organization.

Richey is a graduate of Iowa State University, where he earned a bachelor's degree in economics and math and a master's degree in economics.

About iEmergent:

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com.

Twitter: @iemergent #housingfinance

News from IEmergent

iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced the appointment of Chris Richey as chief analytics officer. In this role, Richey will oversee and expand upon iEmergent's data analytics capabilities, which help mortgage lenders identify gaps in sales coverage and effectively expand into new markets.

Related link: https://www.iemergent.com

This version of news story was published on ScoopCloud™ (ScoopCloud.com) - part of and © the Neotrope® News Network - all rights reserved.