Tag Archives: Texas Business

Optimal Blue report: Purchase demand rebounds as mortgage market finds balance

Lock volume rises 9% month over month and nearly 40% year over year as lower rates draw borrowers back into the market

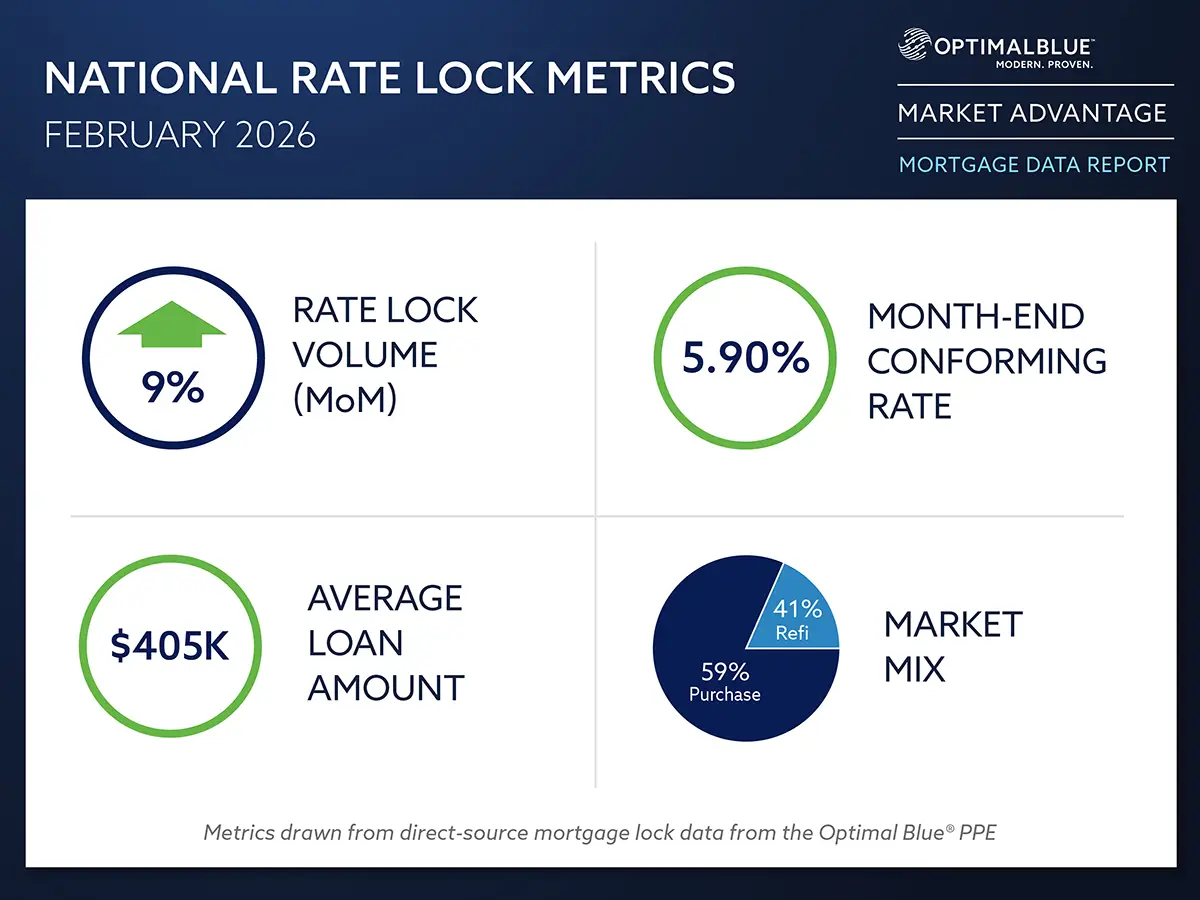
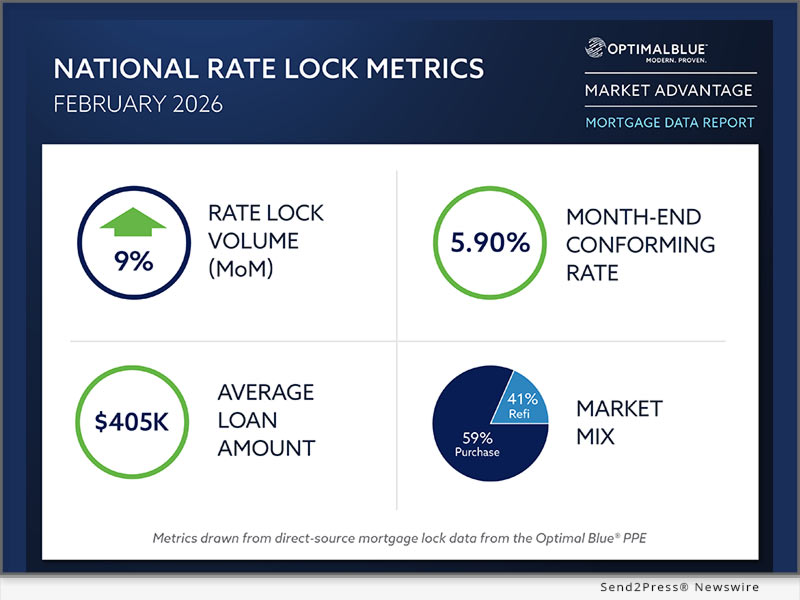
PLANO, Texas, March 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its February 2026 Market Advantage mortgage data report, showing a meaningful improvement in lock activity as lower mortgage rates helped bring purchase borrowers back into the market. Total rate-lock volume rose 9% month over month (MoM) and was nearly 40% higher year over year (YoY). Purchase lock volume increased more than 14% from January and 5% compared with February 2025, driving refinance share down to 41% of locks from 44% in January. Rate-and-term and cash-out refinance activity edged modestly higher from January but remained sharply stronger YoY.
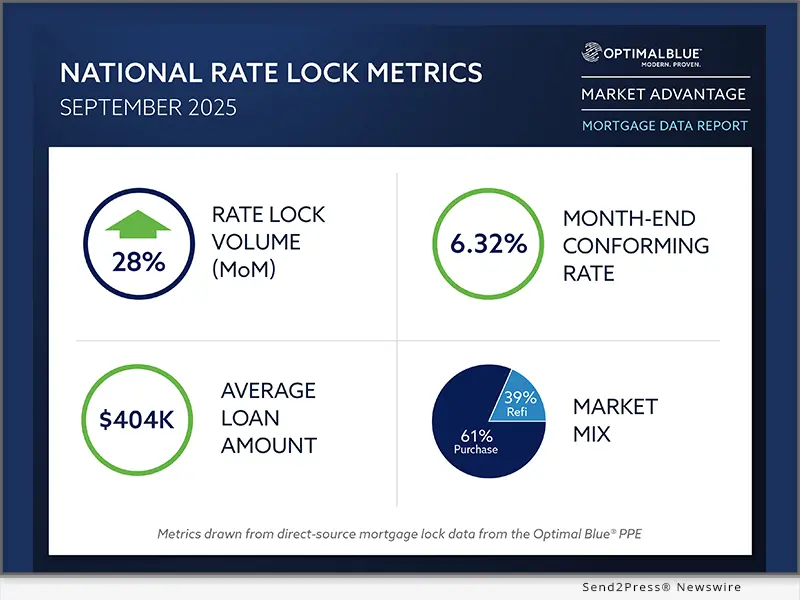
Optimal Blue’s February 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

Mortgage rates declined across all major products in February. The OBMMI 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month at 5.90%, down 17 basis points (bps) from January. Jumbo and VA rates each declined 11 bps during the month, while FHA rates fell 13 bps. The 10-year Treasury yield closed the month at 3.97%, down nearly 30 bps, and the spread between the 10-year Treasury and the OBMMI 30-year rate widened to 193 bps as the mortgage rally lagged the broader bond market.

“February’s data shows the market settling into a healthier balance between purchase and refinance activity as rates moved lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Purchase demand is back after a slow start to the year, but refinance share is still running at 41%, which is higher than anything we saw between early 2022 and late last year.”

Secondary market data in February pointed to shifting execution dynamics as pricing spreads widened and delivery strategies evolved. Best-efforts-to-mandatory spreads widened for conventional products while hedged loan sales moved toward the agency cash window. At the same time, agency mortgage-backed securities (MBS) securitization declined and mortgage servicing rights (MSR) values increased despite falling benchmark rates.

“In an environment like this, lenders are paying close attention to how they execute and manage risk,” said Vough. “We’re seeing more active positioning across delivery channels and servicing assets as lenders balance near-term pricing with longer-term portfolio value.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance activity remains strong: Refinances accounted for 41% of total lock volume in February, down from 44% in January, as purchase demand rebounded. Rate-and-term refinance locks increased 3% MoM and 280% YoY, while cash-out refinance volume rose 1% MoM and 34% YoY.
  • Purchase demand rebounds: Purchase lock volume rose 14% MoM and 5% YoY, marking a meaningful improvement from January’s slower start to the year and helping restore a more balanced mix between purchase and refinance activity.
  • Non-conforming share expands: Conforming loans represented 53% of total lock volume in February, down 28 bps MoM but up 62 bps YoY. Non-conforming share increased to 16%, rising 91 bps MoM and 90 bps YoY. FHA loans accounted for 17% of locks, VA loans for 13% and USDA loans for 1%.
  • ARM utilization rises: Adjustable-rate mortgages comprised 10% of total lock volume in February, up 111 bps MoM and 337 bps YoY from 6.9% last year.

Rates and pricing

  • Rates move lower: The OBMMI 30-year conforming fixed rate declined 17 bps to 5.90%. Jumbo and VA rates each fell 11 bps, while FHA rates declined 13 bps. The 10-year Treasury yield declined nearly 30 bps to 3.97%, while the mortgage-to-Treasury spread widened to 193 bps.
  • MSR values increase: Mortgage servicing rights for conforming 30-year loans rose 2 bps to 1.18%, representing a 4.74 multiple, even as benchmark mortgage rates declined during the month.
  • Spreads adjust across products: Best-efforts-to-mandatory spreads widened for conventional products, with the conforming 30-year spread increasing 3 bps and the conventional 15-year spread rising 1 bp. The government 30-year spread decreased 5 bps.
  • Loan pricing mix shifts slightly: The share of loans sold at the highest price tier declined 100 bps to 78%, while second-tier executions increased 100 bps to 13%.

Channel and execution

  • Securitization share pulls back: Agency MBS securitizations accounted for 42% of hedged executions in February, down from 47% in January.
  • Cash window share jumps: Hedged loan sales to the agency cash window rose 500 bps MoM to 29%, the largest share of cash window deliveries since February 2025.

Product mix and borrower profiles

  • Credit profiles diverge: Purchase FICO scores averaged 734 in February, down 1 point MoM and 3 points YoY. Refinance credit profiles strengthened, with cash-out scores averaging 705 (up 1 point MoM and 10 points YoY) and rate-and-term scores averaging 749 (up 2 points MoM and 18 points YoY).
  • Loan amounts climb: The national average loan amount increased from $400,667 in January to $404,586 in February, marking the first time the average has remained above $400,000 for consecutive months. The national average loan-to-value ratio was 80.32%. Loan amounts ranged from $875,787 in the San Francisco Bay area to $319,743 in San Antonio, with regional LTVs spanning from 68.45% in the Bay area to 89.38% in San Antonio.

To view the full February 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0310-s2p-opblufeb26mk-300dpi.webp

Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-demand-rebounds-as-mortgage-market-finds-balance/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133788 NOREL-3B
 

Optimal Blue to host 2027 Summit February 1-3 in Scottsdale

Third annual event will return to Arizona for three days of capital markets strategy and innovation

PLANO, Texas, Feb. 25, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced it will host its 2027 Optimal Blue Summit February 1–3 at the JW Marriott Desert Ridge Resort & Spa in Scottsdale, Arizona. The annual event convenes Optimal Blue clients, integration partners and capital markets leaders from across the mortgage industry for three days of insight, collaboration and forward-looking strategy.

Optimal Blue
Image caption: Optimal Blue.

Entering its third year, the Optimal Blue Summit has become a forum for mortgage capital markets professionals to explore technology innovation, share best practices and engage in candid discussion about the market dynamics shaping the industry. The 2027 agenda will continue that focus with expert-led sessions, hands-on training and curated networking designed to equip attendees with practical strategies they can apply within their organizations.

“Our Summit is where strategy and execution come together,” said Sara Holtz, chief marketing officer at Optimal Blue. “Each year, we create an environment where clients and partners can engage directly with our leadership team, explore new platform capabilities and exchange ideas with peers facing similar market challenges. We look forward to building on this year’s momentum as we return to Arizona in 2027.”

Event highlights will include:

  • New technology unveilings: Early access to Optimal Blue’s latest platform advancements, including AI-driven capabilities, automation enhancements and expanded integrations
  • Market intelligence and economic insights: Expert perspectives on secondary market dynamics, rate trends and capital markets strategy
  • Execution and performance workshops: Tactical sessions focused on pricing accuracy, margin management, hedging and operational efficiency
  • Executive leadership forums: Discussions centered on navigating volatility and positioning for sustainable growth
  • Interactive feedback sessions: Client roundtables and product forums designed to shape the future direction of the Optimal Blue platform

Registration for the 2027 event is now open at Summit.OptimalBlue.com. Early bird pricing is available for a limited time.

Additional event details will be announced in the coming months.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-to-host-2027-summit-february-1-3-in-scottsdale/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133459 NOREL-3B


Industry-first AI/ML-powered forecasting tool headlines extensive lineup of mortgage capital markets innovations unveiled at 2026 Optimal Blue Summit

On-demand Virtual Economist anchors nine advancements that unify the capital markets profitability experience across the loan life cycle

PLANO, Texas, Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced Virtual Economist, the first on-demand forecasting tool for mortgage capital markets leaders powered by artificial intelligence and machine learning (AI/ML), as the centerpiece of nine platform advancements unveiled at the company’s 2026 Summit. Together, the innovations further unify the capital markets profitability experience by connecting forecasting, pricing, hedging, competitive benchmarking and workflow execution within a single, end-to-end platform.

Optimal Blue
Image caption: Optimal Blue.

“The future of mortgage capital markets belongs to platforms that don’t just respond to volatility, but anticipate it,” said Joe Tyrrell, CEO at Optimal Blue. “Optimal Blue is building and continuously innovating an intelligent, connected and comprehensive ecosystem that gives lenders clarity and confidence from origination to secondary marketing, and back again. The innovations announced at our 2026 Optimal Blue Summit reflect our long-term commitment to redefining how the industry plans, prices and performs in any market environment.”

“Virtual Economist was built to address a real challenge our lender clients face – the disconnect between economic insight and day-to-day execution,” said Erin Wester, chief product officer at Optimal Blue. “By uniting public economic indicators with Optimal Blue’s proprietary lock volume data and applying AI/ML-driven forecasting, teams can test assumptions and prepare immediately through conversational and visual scenario modeling. That same data-driven approach extends across our 2026 innovations, creating a tighter feedback loop among pricing, margin management and hedge analytics so decisions are informed by real-time insight and reflected consistently across the platform.”

The 2026 Summit advancements include:

VIRTUAL ECONOMIST

In a market where profitability planning typically depends on static, macro forecasts and manual what-if exercises, Virtual Economist gives lenders on-demand predictions without the lag, labor or subjectivity of traditional approaches. The mortgage industry’s first and only AI/ML-powered forecasting tool, it combines public economic data with Optimal Blue’s lock volume data into proprietary machine learning models to deliver real-time rate and volume predictions and instant scenario analysis for strategic planning. Users can choose their preferred economist avatar and engage conversationally through voice or text, with forecasts presented visually to enhance clarity and decision-making.

PROFITABILITY CENTER

Profitability Center introduces a unified dashboard across Optimal Blue products, enabling faster navigation while surfacing cross-product market, production and profitability insights that inform decision-making before users move into deeper workflows. This central landing experience includes access to an economic calendar and predictive insights to anticipate market movement and plan hedging or pricing actions accordingly.

COMPETITIVE DATA LICENSE PLUS

Competitive Data License Plus expands Optimal Blue’s benchmarking capabilities by adding anonymized hedging and trading data to its existing lock and pricing dataset. By connecting front-end pricing behavior with back-end loan sale outcomes updated daily, it delivers deeper visibility into pull-through performance, margin from lock to sale, investor turn times and best-efforts versus mandatory execution spreads. The enhanced dataset enables lenders to model competitive positioning and execution strategy with greater precision across the capital markets life cycle.

AGENCY DIRECT (for CompassEdge)

Agency Direct in CompassEdge modernizes retained execution workflows for institutions delivering loans to Fannie Mae, Freddie Mac and the Federal Home Loan Bank system. By replacing manual spreadsheet-based tracking with a centralized environment for loan imports, coverage modeling and commitment management in CompassEdge, the solution strengthens executive visibility while reducing operational risk.

RATESHEET PRICING INSIGHTS (for CompassEdge)

Ratesheet Pricing Insights connects pricing from the Optimal Blue PPE with CompassEdge margin management, reducing the lag and manual processes that can separate pricing decisions from published rates. By syncing margin updates directly between systems and embedding market and competitive context into the workflow, it surfaces competitive insights before ratesheets are published and helps ensure rates reflect current conditions while improving margin discipline.

HEDGE COST IN THE PPE (for the Optimal Blue PPE)

Hedge Cost in the PPE embeds CompassEdge hedge analytics directly within the Optimal Blue PPE, giving lenders immediate visibility into the margin impact of extensions, renegotiations and price concessions. By surfacing hedge coupon, mark-to-market exposure and effective margin at the point of decision, it strengthens alignment between origination and secondary teams while protecting execution performance at the transaction level.

AI RULES ASSISTANT (for the Optimal Blue PPE)

AI Rules Assistant enhances Rules Optimizer, a feature within the Optimal Blue PPE that manages pricing and eligibility rules across investor relationships, by enabling administrators to “speak policy, ship rules” – i.e., input natural language and allow AI automation to generate the new rule. It identifies similar configurations and automatically builds required dependencies for review, accelerating rule creation while strengthening governance and pricing control.

ENHANCED ADMIN EXPERIENCE (for the Optimal Blue PPE and CompassEdge)

Enhanced admin experiences in both the Optimal Blue PPE and CompassEdge hedging and trading platform arm administrators with faster, more intuitive ways to configure pricing and manage investors.

In the Optimal Blue PPE, a redesigned configuration experience consolidates key tools into a straightforward, user-friendly workspace, with embedded entity selection and global Release to Production access from any screen. By reducing clicks and improving visibility across pricing configurations, it accelerates setup and governance workflows for administrators.

In CompassEdge, new administrative configuration for investor management gives users more straightforward visibility into the configuration for valuing their loan pipeline. Users can self-manage investors, execution types and more in a single, accessible place.

LOANSIFTER–COMERGENCE CONNECTION

A new connection between Optimal Blue’s Loansifter PPE for mortgage brokers and its Comergence counterparty oversight solution links promotional pricing visibility with counterparty engagement data, giving investors measurable insight into broker interaction and marketing effectiveness. By connecting broker activity with onboarding and approval workflows, the integration enables investors to capture qualified leads and accelerate TPO network growth.

Several of the announced innovations are live today, with others entering beta or phased rollout throughout 2026.

Optimal Blue’s annual Summit brings together lenders, investors and industry leaders to explore the strategies and technologies shaping the future of mortgage capital markets.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/industry-first-ai-ml-powered-forecasting-tool-headlines-extensive-lineup-of-mortgage-capital-markets-innovations-unveiled-at-2026-optimal-blue-summit/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133391 NOREL-3B


FirstClose and TruStage form partnership to accelerate dynamic credit union lending documentation

AUSTIN, Texas, Feb. 19, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, Inc., a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced a strategic partnership with TruStage to embed TruStage’s dynamic document engine within the FirstClose platform.

FirstClose logo
Image caption: FirstClose and TruStage form partnership to accelerate dynamic credit union lending documentation.

“Partnering with TruStage supports our commitment to giving lenders a modern documentation experience that reduces friction for both teams and members,” said Tedd Smith, chief executive officer of FirstClose. “FirstClose manages the data, workflow and delivery, while TruStage brings deep expertise in applying lender-configured compliance rules to dynamically generate documents, which will add meaningful efficiencies across the lending process.”

Under the partnership, FirstClose provides the structured data captured during initial intake and eligibility and manages document logistics, including borrower delivery and e-sign workflows. TruStage’s dynamic document engine automatically selects the appropriate documents based on real-time analysis of each transaction and lender-defined rules and compliance requirements, generating a warranted list of required disclosures and other documents without requiring lenders to build and maintain custom document groups for each product. This helps support accuracy and consistency across home-equity and mortgage lending processes.

“This collaboration allows TruStage to extend our document capabilities into the FirstClose platform in a way that respects how lenders configure and manage compliance,” said Chris Appie, president of the Compliance Solutions business at TruStage. “By applying lender-defined rules and requirements to data provided by FirstClose, we help institutions maintain control while supporting a more efficient lending experience.”

The integration is expected to be delivered in 2026.

About TruStage

TruStage® is a financially strong insurance and financial services provider, built on the philosophy of people helping people, meeting the needs of middle-market consumers and the businesses that serve them since day one. We believe a brighter financial future should be accessible to everyone, and our products and solutions help people confidently make financial decisions that work for them at every stage of life. With a culture rooted and focused on creating a more equitable society and financial system, we are deeply committed to giving back to our communities and improving the lives of those we serve today and tomorrow. For more information, visit www.trustage.com.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-and-trustage-form-partnership-to-accelerate-dynamic-credit-union-lending-documentation/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133299 NOREL-3B


Optimal Blue report: Sub-6% rates spark refinance surge early in 2026

​​Refinances jump as execution strategies and investor demand shift

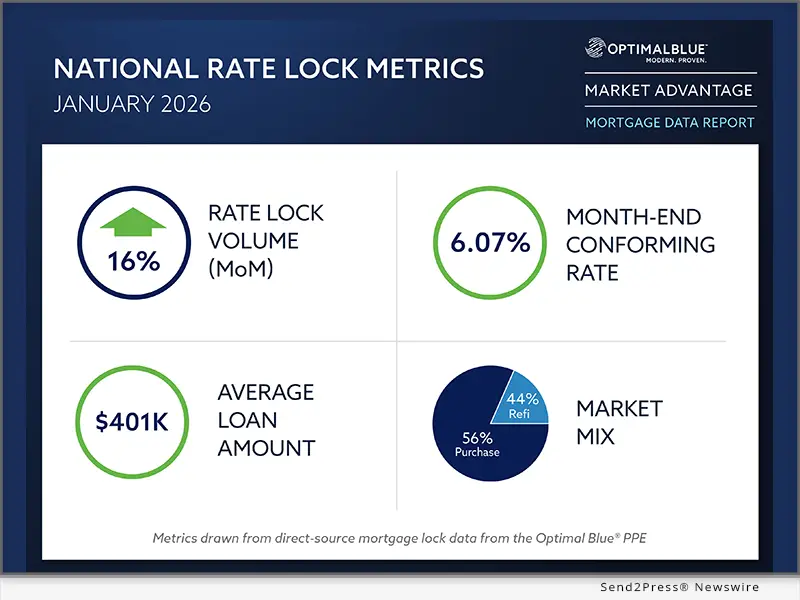
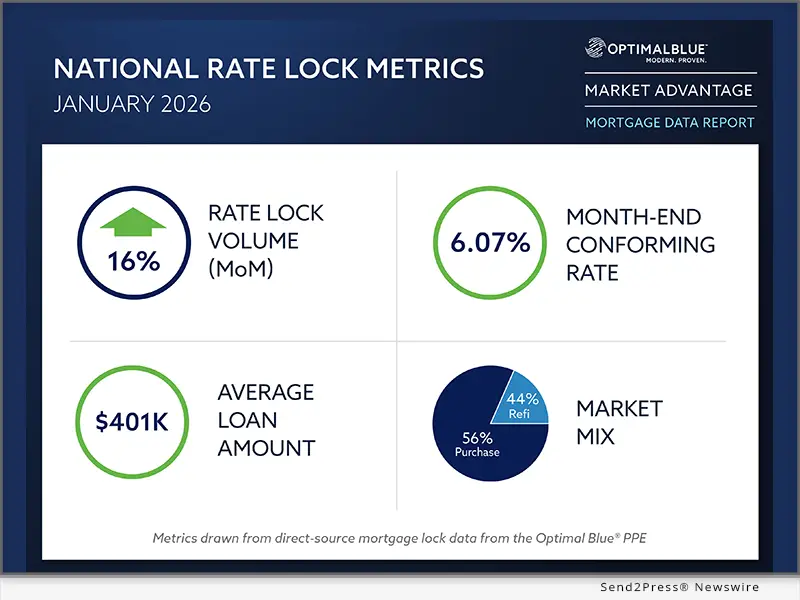
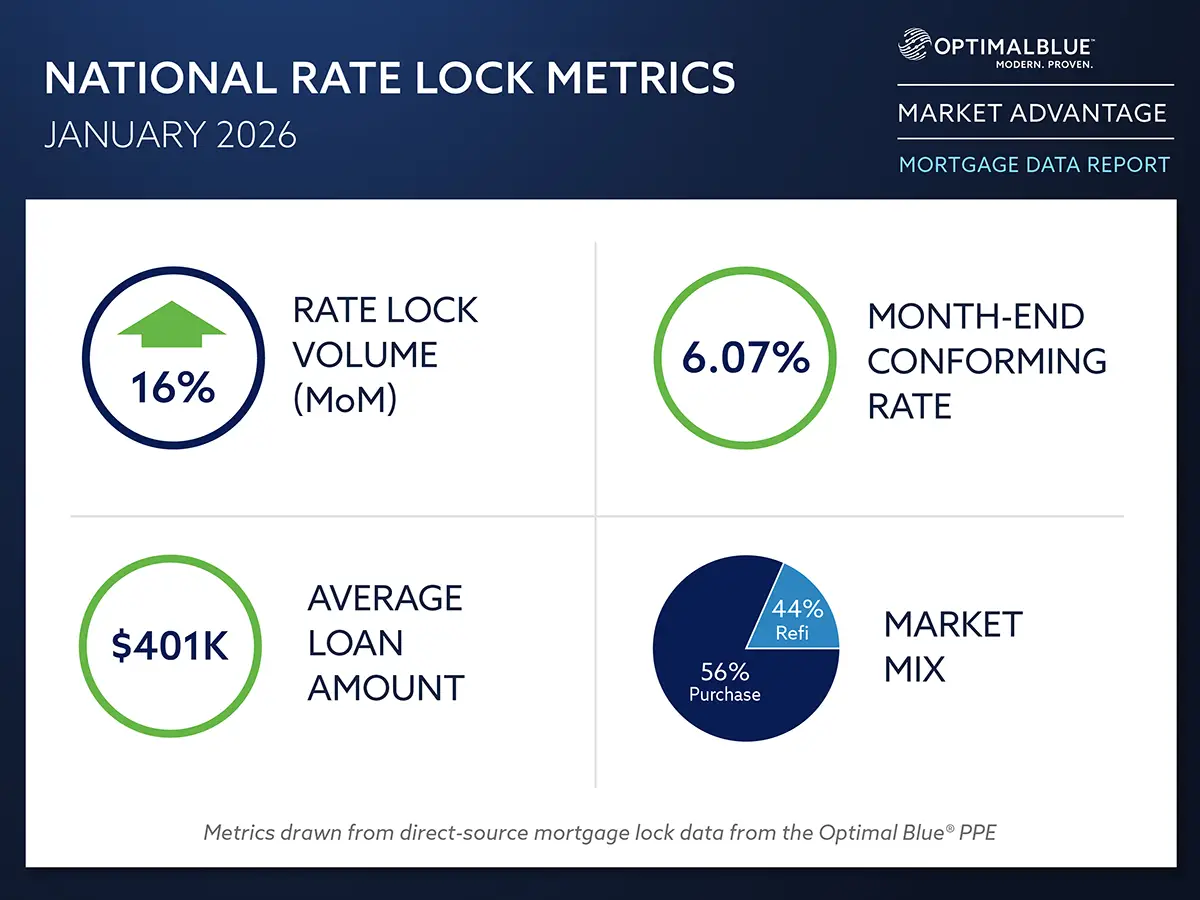
PLANO, Texas, Feb. 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its January 2026 Market Advantage mortgage data report, showing a strong start to the year as falling rates drove a sharp increase in refinance activity. Total rate-lock volume rose 16% month over month (MoM) and finished January 36% higher year over year (YoY), led by a surge in rate-and-term refinances, which climbed 50% from December and more than 400% compared with January 2025. Cash-out refinance activity also increased, rising 11% MoM and 38% YoY. Purchase volume grew a modest 3% from December but remained down 5% from a year earlier, reflecting the slower response of purchase demand to changing rate conditions early in the year.

Optimal Blue’s January 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

Mortgage rates moved lower across most products in January. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, declined 7 basis points (bps) to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely unchanged at 5.99%. The average locked rate on the Optimal Blue PPE fell below 6% for the first time since August 2022.

“January’s data shows just how quickly refinance demand can respond when rates move lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “It’s been more than three years since the market last saw average rates with a ‘5 handle,’ and crossing back below that level appears to have released meaningful pent-up refinance demand. Purchase activity is responding more gradually, which is typical this early in the year, but the shift in borrower behavior is clear.”

On the secondary side, lenders adjusted execution strategies as pricing dynamics shifted and investor demand strengthened. Best-efforts-to-mandatory spreads increased for 30-year products, securitization activity increased and mortgage servicing rights (MSR) values rose despite declining benchmark rates, signaling a continued focus on balance sheet positioning and longer-term value.

“January’s secondary market data reflects lenders positioning early for a potentially more active origination environment,” said Vough. “Pricing trends were increasingly tied to eligibility rather than outright price give-ups, and agency MBS securitization reached its largest share since 2024. Meanwhile, rising MSR values and expanding investor participation point to a market focused on flexibility and long-term execution strategy as 2026 begins.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

VOLUME TRENDS AND MARKET COMPOSITION

  • Sharp pickup in refis: Refinance activity surged in January as falling rates quickly translated into borrower demand. Rate-and-term refinance locks increased 50% MoM and were more than four times higher YoY. Cash-out refinances also gained momentum, rising 11% MoM and 38% YoY.
  • Purchase activity lags: Purchase volume increased a modest 3% MoM but remained down 5% YoY. The slower response reflects the typical lag in purchase demand relative to rate movements, particularly early in the year.
  • Non-QM share pulls back: Non-qualified mortgage share declined to 8% in January, down 160 bps from December but 70 bps higher YoY.
  • VA gains momentum: VA lending captured a larger share of January activity as borrowers moved quickly to take advantage of lower rates, positioning VA portfolios for increased refinance-related payoffs as those loans move through the pipeline. VA loans accounted for 14% of locks, up 125 bps MoM and 212 bps YoY.
  • PUD share retreats: Planned unit developments (PUDs) accounted for 28% of locks in January, down 95 bps MoM and 651 bps YoY.

RATES AND PRICING

  • Rates edge down: Mortgage rates moved lower across most products in January. OBMMI for the 30-year conforming fixed rate declined 7 bps to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely flat at 5.99%.
  • MSR values tick higher: MSR values for conforming 30-year loans increased 2 bps to 1.16%, representing a 4.65 multiple, diverging from declining benchmark rates.
  • Spreads widen on rate moves: Best-efforts-to-mandatory spreads increased for 30-year products in January, with the conforming 30-year spread widening 3 bps and the government 30-year spread increasing 8 bps. The conforming 15-year spread narrowed by 8 bps during the month.
  • Pricing discipline persists: The share of loans sold at the highest price tier remained flat at 79%, while second-tier executions increased 200 bps to 13%, reflecting continued use of eligibility-based delivery strategies with less price concession.

CHANNEL AND EXECUTION

  • Execution mix tilts to securitization: Lenders shifted hedged execution toward agency MBS in January, with securitization share increasing 300 bps MoM to 47%, the largest share since 2024.
  • Aggregator and cash executions ease: Loan sales to bulk aggregators declined 100 bps MoM, while cash window executions also decreased 100 bps during the month.
  • Investor participation continues to expand: The number of active investors increased to 14 in January, extending the expansion in investor participation that began late last year.

PRODUCT MIX AND BORROWER PROFILES

  • Credit quality improves: Average credit scores increased for both cash-out refis (up 2 points) and rate-and-term refis (up 5 points). Credit scores also rose across all major products, including conforming (up 1 point), FHA (up 1 point) and VA (up 4 points) loans.
  • Affordability metrics improve: Purchase debt-to-income (DTI) ratios declined across all loan types in January and fell 1 to 2 percentage points YoY. The share of first-time homebuyers also increased, rising to 45% of conforming loans and 70% of FHA loans.
  • Loan amounts edge up: The average loan amount increased from $394,502 in December to $400,667. January loan amounts ranged from $868,498 in greater San Francisco to $316,638 in San Antonio. Loan-to-value ratios ranged from 70.21% in greater Los Angeles to 88.44% in San Antonio, with a national average of 80.06%.

To view the full January 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Inage link for media: https://www.Send2Press.com/300dpi/26-0210-s2p-opblue-300dpi.webp

Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-sub-6-rates-spark-refinance-surge-early-in-2026/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132992 NOREL-3B


NotaryCam surpasses 2 million lifetime notarizations, doubles credit card transaction volume in 2025

HOUSTON, Texas., Jan. 30, 2026 (SEND2PRESS NEWSWIRE) — NotaryCam®, a Stewart-owned company and leading remote online notarization (RON) provider for real estate and legal transactions, announced a standout year in 2025, having reached more than 2 million successful notarizations to date, including more than 238,000 notarizations completed this year. The company also doubled both its credit card transaction volume and the number of servicers using loss mitigation-related RON transactions through its real estate vertical, exemplifying growing industry adoption of digital solutions.

Infographic: NotaryCam year in review 2025
Image caption: Infographic: NotaryCam year in review 2025.

“2025 was a pivotal year for NotaryCam as we saw record adoption of remote online notarization across real estate, servicing and credit workflows,” said Brian Webster, president and CEO of NotaryCam. “Surpassing the 2 million notarization milestone reflects not only the scalability of our technology, but the trust our clients place in us to deliver secure, compliant and reliable digital transactions. As demand for RON continues to accelerate, we remain focused on expanding access, strengthening integrations and helping the industry modernize with confidence.”

In 2025, NotaryCam also played a central role in Stewart’s launch of Signer’s Choice, a premier, all-in-one signing solution that unifies NotaryCam’s industry-leading remote online notarization technology with Signature Closers’ nationwide in-person signing network. The combination brings together two proven Stewart companies under a single brand, delivering unmatched flexibility for title companies, lenders and institutions navigating increasingly complex signing requirements.

By integrating RON and in-person signing capabilities into one compliant, scalable solution, Signer’s Choice eliminates the fragmentation that has long challenged the signing process, allowing transactions to move seamlessly forward without redraws, rekeying, alternate providers or costly delays.

“The launch of Signer’s Choice was one of the most important milestones of the year for us,” Webster said. “By bringing Signature Closers together with NotaryCam under a single brand, we’ve created a truly unified signing experience that gives our clients the flexibility to move between remote and in-person notarization without disruption. It’s a powerful extension of our mission to modernize transactions while preserving the human-driven service the industry depends on.”

The company onboarded more than 60 new enterprise clients and 149 independent notaries. NotaryCam expanded existing partnerships and integrated with several additional partners expanding its footprint in mortgage servicing and originations. In addition, the company achieved a Trustpilot score of 4.9 and an industry-leading Net Promoter Score (NPS) of 88, based on more than 13,000 responses with an average score of 9.6, reflecting exceptional customer satisfaction.

NotaryCam’s 2025 achievements solidify the company’s position as a trusted provider of digital notarization and mortgage eClosing solutions, powered by its scalable, MISMO-certified eClose360® platform. Featuring secure signing rooms and flexible integration capabilities, the platform continues to set industry benchmarks for reliability and operational efficiency.

Multiple industry recognitions underscored NotaryCam’s expertise:

  • The company was included in the HousingWire Tech100 for the seventh consecutive year.
  • President and CEO Brian Webster was honored as a HousingWire Vanguard.
  • Enterprise Product Manager Joseph Bisaillon was named a HousingWire Tech Trendsetter.

ABOUT NOTARYCAM, A STEWART COMPANY

NotaryCam, a Stewart-owned company, is a leader in online notarization and mortgage eClosing solutions, having notarized documents worldwide for more than a million customers. The company’s eClose360® platform delivers the “perfect” online mortgage closing in every allowable jurisdiction and supports all eClosing scenarios with a flexible workflow for document recording and unparalleled identity verification, security and customer convenience. In addition to real estate transactions, NotaryCam provides RON services to many Fortune 500 companies as well as small and midsize businesses. The company also proudly maintains an industry-leading 99.8 percent customer satisfaction rating and the highest Net Promoter Score (NPS) amongst the best global tech brands.

Visit https://www.notarycam.com for additional information or to get a document notarized today.

NEWS SOURCE: NotaryCam Inc.


This press release was issued on behalf of the news source (NotaryCam Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/notarycam-surpasses-2-million-lifetime-notarizations-doubles-credit-card-transaction-volume-in-2025/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132649 NOREL-3B


Real-World Police Experience Drives 4,000+ Elite Protection and Security Dog Placements Worldwide

ARGYLE, Texas, Jan. 27, 2026 (SEND2PRESS NEWSWIRE) — Scott’s K9 has reached a significant milestone with over 4,000 dogs trained and placed globally. These protection dogs for sale range from police and government contract placements to private protection dogs. This is an achievement founder, Steve Scott, attributes to a differentiator most protection dog companies lack: authentic police K9 experience applied to family protection.

Elite trained protection dogs | Scott's K9
Image caption: Elite trained protection dogs.

Unlike typical protection dog trainers, Scott’s K9 bridges two worlds rarely combined in the civilian market. Scott served as head trainer of his police department’s K9 Unit after military deployments across Europe, where he refined advanced K-9 dog training methods and cultivated relationships with elite European kennels that supply working dogs to law enforcement and military units, worldwide.

“Our competitive advantage is straightforward,” Scott explains. “We apply real-world police K9 training methodologies to family protection dogs. Most companies in this space lack actual law enforcement experience. We’ve trained dogs that have to perform under genuine life-threatening conditions, and we bring that expertise to every family placement.”

Scott notes that when his daughter attended Texas A&M a Malinois was by her side.

So, how does Scott’s law enforcement background manifest? It does so in several ways:

Dual-capability training: Scott’s K9 dogs provide both genuine family companionship and elite-level protection — a balance that requires understanding how working dogs perform in unpredictable real-world scenarios, not just controlled training environments.

Comprehensive family integration: Drawing from police K9 handler training protocols, Scott personally instructs clients, their children and family members on proper deployment of their protection dogs in various situations — teaching civilians to work with their dogs the way law enforcement handlers do.

No-nonsense approach: Scott’s training philosophy reflects his police background which includes direct, practical instruction focused on what families actually need to know and eliminates the marketing rhetoric common in the luxury protection dog industry.

The milestone comes as client inquiries have jumped 47 percent over two years, driven by increased security concerns among high-profile individuals and families in remote estates. Industry observers note that professionally trained protection dogs offer security advantages that alarm systems cannot replicate — a trained dog provides judgment, deterrence and protective capability that technology alone cannot deliver.

Scott’s K9 is a premier provider of elite protection dogs based in Argyle, Texas
Image caption: Scott’s K9.

Scott’s K9’s comprehensive approach, rigorous temperament testing, obedience training and specialized protection work, has established new industry standards in professional security dog placement, with placements now spanning six continents among Fortune 500 executives, high-net-worth families, law enforcement agencies and corporate security teams.

“This milestone validates our approach but doesn’t change our mission,” Scott says. “Our goal is making professional-grade security dog placement accessible to more clients who understand the difference between marketing and genuine protection capability.”

Scott’s K9 continues working exclusively with select breeders across Europe and North America, ensuring each dog meets rigorous health, temperament and working ability standards before beginning specialized training.

Each protection dog is priced at $150,000 USD. They do not offer tiers, levels or sell partial protection and all dogs are trained to one uncompromising global standard. This exceeds what the industry refers to as Level 1, Level 2 or Level 3 protection dogs.

ABOUT SCOTT’S K9

In business for 20 years, Scott’s K9 is a premier provider of elite protection dogs based in Argyle, Texas. Founded by Steve Scott, a U.S. Army veteran and former head trainer of a police department K9 Unit, the company serves executives, families, estates and agencies worldwide.

MORE INFORMATION:

Visit: https://scottsk9.com/

MULTIMEDIA:

Photo link for media: https://www.Send2Press.com/300dpi/26-0127-s2p-scottsk9dogs-300dpi.webp

Photo caption: Elite trained protection dogs.

NEWS SOURCE: Scott's K9


This press release was issued on behalf of the news source (Scott's K9), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/real-world-police-experience-drives-4000-elite-protection-and-security-dog-placements-worldwide/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132540 NOREL-3B


FirstClose Caps Transformational 2025 With Faster Closings, Platform Expansion and Strong Market Momentum

AUSTIN, Texas, Jan. 16, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced 2025 results showing faster closings and measurable efficiency gains as lenders used its technology to meet rising home equity demand in a high-interest-rate environment. The company reduced closing timelines, expanded key integrations and strengthened its operating foundation to support scalable growth in 2026.

FirstClose Caps Transformational 2025 With Faster Closings, Platform Expansion and Strong Market Momentum
Image caption: FirstClose Caps Transformational 2025.

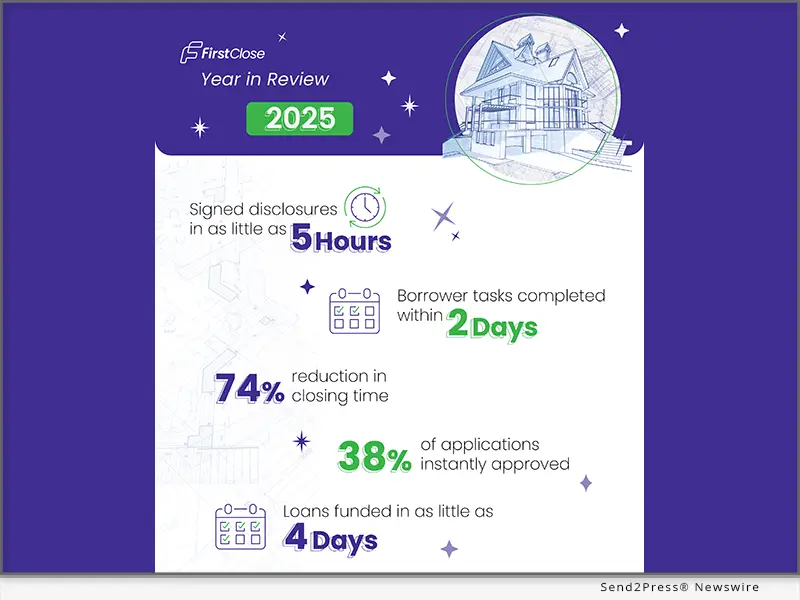
By year’s end, lenders using FirstClose signed disclosures in as little as five hours, completed borrower tasks within two days and funded loans in as few as four days. The platform helped reduce closing timelines by up to 74%, with 38% of applications instantly approved via automated decisioning workflows.

“We were deliberate in 2025 about building a durable foundation rather than chasing short-term growth,” said Tedd Smith, co-founder and chief executive officer of FirstClose. “That work is paying off in faster outcomes for lenders today and positions us well for the opportunities ahead.”

Those performance gains came as home equity lending continued to accelerate nationally. FirstClose has supported over 225 financial institutions and contributed to $129 billion in funded loans since 2015, while lenders using its digital prequalification tools have reported 30-40% increases in application volume.

A major milestone in 2025 was the launch of a certified integration with Optimal Blue, which connects FirstClose’s point-of-sale platform directly to Optimal Blue’s product, pricing, and eligibility engine. The integration brought lender-specific pricing into the borrower application flow, helping to compress home equity closing timelines from roughly 45 days to 10 days or fewer.

FirstClose also secured additional equity funding in October, led by existing investor Lateral Investment Management. The investment reinforced confidence in the company’s strategy and supported continued product development, integrations and operational initiatives across home equity and mortgage lending.

Internally, 2025 was a year of restructuring to prepare the organization for its next phase of growth. FirstClose strengthened leadership in sales, professional services, and client success to improve coordination among teams and reduce implementation times for lenders. The changes focused on operational durability rather than rapid expansion.

The year also coincided with FirstClose’s 25th anniversary, underscoring its long-standing role in modernizing mortgage and home equity lending. From its early days as a property data and settlement services provider to its current end-to-end lending platform, the company has continued to evolve alongside lender needs and market shifts.

With faster funding, deeper integrations and a strengthened operating model in place, FirstClose enters 2026 positioned to help lenders capture growing home equity demand while delivering a more transparent and efficient borrower experience.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-caps-transformational-2025-with-faster-closings-platform-expansion-and-strong-market-momentum/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132356 NOREL-3B


Optimal Blue report: December lock volume closes 2025 on a firm footing

Refinance momentum drives year-end activity despite holiday headwinds

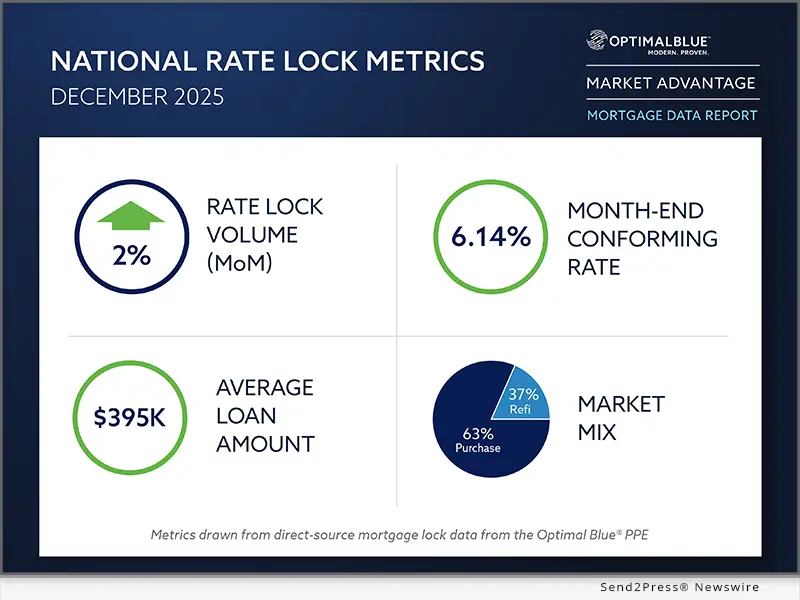
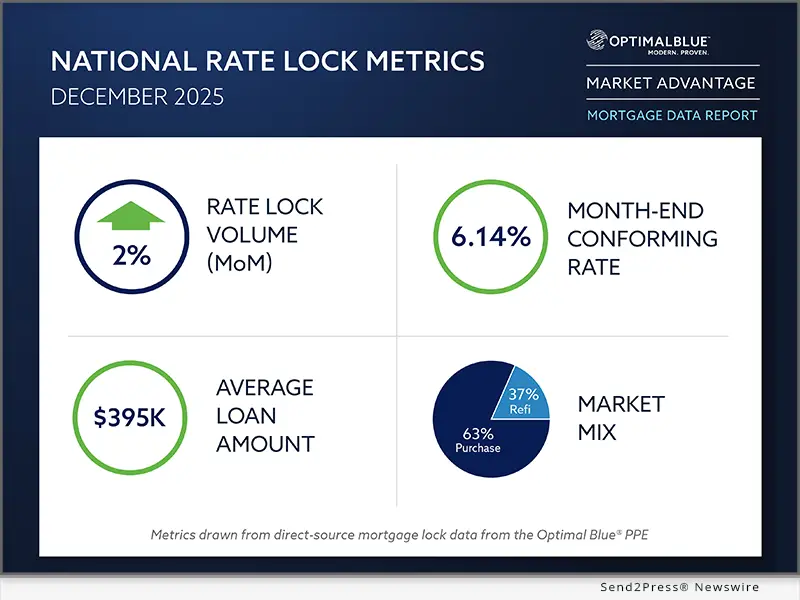
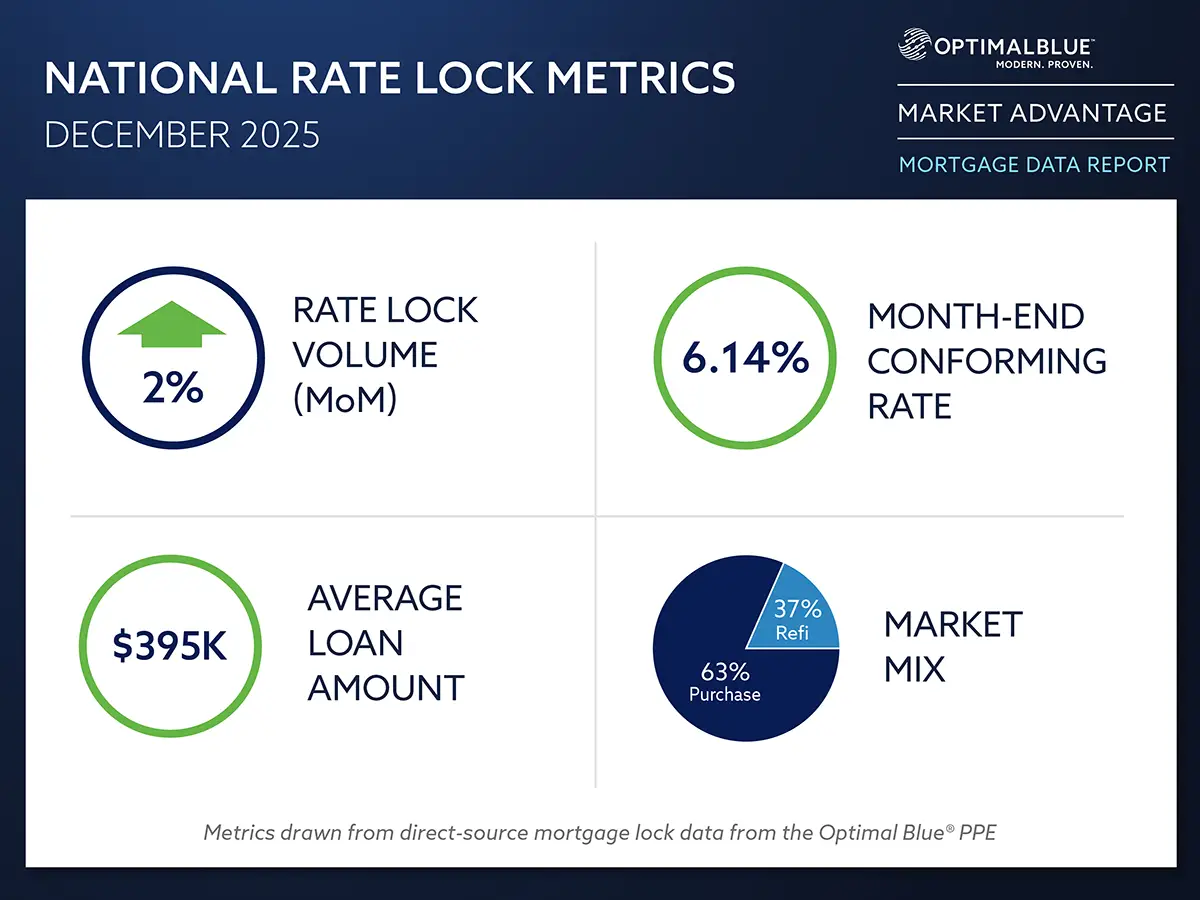
PLANO, Texas, Jan. 13, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its December 2025 Market Advantage mortgage data report, showing that mortgage rate-lock activity ended the year on a firm footing, bucking typical holiday-driven seasonality. Total lock volume rose 2% month over month (MoM) from November and finished 30% higher year over year (YoY), driven primarily by rate-and-term refinances, which climbed 13% from November and more than 170% compared with December 2024. Cash-out refinance volume rose a modest 1% MoM but remained up a strong 35% YoY. Purchase activity dipped just 1% from November despite holiday headwinds to end December up 7% YoY.

Optimal Blue's December 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report.

Mortgage rates were largely stable in December. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month flat at 6.14%. Meanwhile, the 10-year Treasury yield rose 14 basis points (bps) to 4.14%, reversing November’s spread widening and pushing the 10-year-to-OBMMI spread to 200 bps at year-end.

“Finishing the year with higher lock volume in December is a clear signal that borrower demand has adjusted to today’s rate environment,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Refinance activity continues to do the heavy lifting, but the fact that purchase volume held essentially flat month over month and finished the year higher than last December speaks to a market that is more durable than many expected.”

Lenders also made notable adjustments on the secondary side as pricing dynamics and execution strategies evolved. Best-efforts-to-mandatory spreads widened across products, bulk aggregator execution regained share, and mortgage servicing rights (MSR) values increased despite flat primary rates.

“December’s secondary data shows lenders actively recalibrating execution as spreads widened and pricing discipline remained tight,” Vough said. “The shift back toward bulk aggregation, combined with stable top-tier pricing and rising MSR values, reflects investor demand that is focused on end-of-year balance sheet management and long-term value as we head into 2026.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance share expands: Refinances accounted for 37% of all locks in December, up 224 bps MoM and 1,354 bps YoY. Rate-and-term refinance volume increased 13% MoM and more than 170% YoY, while cash-out refinances rose 1% MoM and 35% YoY. Overall refinance pull-through improved 194 bps from November to 69.2%.
  • Purchase market remains resilient: Purchase locks slipped just 1% MoM despite typical holiday-driven seasonality and finished December 7% higher than a year earlier. Pull-through for purchase loans increased 199 bps MoM to 85.7%.
  • Non-QM sets another record: Non-qualified mortgage production maintained its upward trajectory, finishing December above 9% of locks, up 50 bps MoM.
  • Government and non-conforming gain share: Conforming loans accounted for 51% of locks in December, down 86 bps MoM and 18 bps YoY. Non-conforming share rose to 17%, up 17 bps MoM and 141 bps YoY. FHA, VA and USDA loans each gained share during the month.
  • PUD share remains sizable: Planned unit developments (PUDs) accounted for 29% of locks by property type, up 123 bps MoM but below year-ago levels, when PUD share was higher.

Rates and pricing

  • Rates largely unchanged: The OBMMI 30-year conforming fixed rate ended December flat at 6.14%. FHA rates declined 1 bp to 5.98%, VA rates fell 6 bps to 5.71% and jumbo rates dropped 3 bps to 6.41%.
  • MSR values move higher: MSR values for conforming 30-year loans increased 5 bps to 1.14%, representing a 4.57 multiple, rising despite largely stable primary rates.
  • Treasury yields rise as spreads widen: The 10-year Treasury yield increased 14 bps to 4.14% in December, compressing the mortgage–Treasury spread to 200 bps. Best-efforts-to-mandatory spreads widened across products, including a 2-bp increase for conforming 30-year loans and a 3-bp increase for government 30-year loans.
  • Top-tier pricing holds: The share of loans sold at the highest price tier remained flat at 79%, while second-tier share was unchanged at 11%, reflecting continued pricing discipline across the market.

Channel and execution

  • Execution mix shifts back toward aggregators: Lenders adjusted hedged execution strategies in December as bulk aggregators regained share at the expense of agency securitization and cash window channels.
  • Bulk aggregator share rebounds: Hedged loan sales to bulk aggregators increased 200 bps MoM to 29%, reversing a multi-month decline.
  • Securitization and cash window ease: Agency mortgage-backed securities (MBS) executions and cash window sales each declined 100 bps during the month.
  • Investor participation increases: The number of active investors rose to 12 in December after holding steady at 11 for four consecutive months, modestly expanding execution options for lenders.

Product mix and borrower profiles

  • Credit scores edge lower: The average borrower credit score declined to 732 in December from 733 in November, extending a gradual pullback from 746 in September.
  • Loan sizes rise as leverage varies by market: The average loan amount increased to $394,502 from $391,323 in November. Loan sizes ranged from $812,240 in Los Angeles to $315,735 in San Antonio. Loan-to-value ratios ranged from 68.85% in the San Francisco–Oakland Bay Area to 87.69% in San Antonio, with a national average of 80.10%.

To view the full December 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/26-0113-s2p-opbluedec25-300dpi.webp

Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-december-lock-volume-closes-2025-on-a-firm-footing/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132225 NOREL-3B


Nyle Maxwell Collision Center Brings on Collision Industry Veteran, Tammie Harper, as Collision Center Director

AUSTIN, Texas, Jan. 8, 2026 (SEND2PRESS NEWSWIRE) — Nyle Maxwell Collision Center, Austin’s highly respected automotive collision repair center located at 13581 Research Blvd., Austin, Texas 78750, has appointed Austin native and collision industry veteran, Tammie Harper, as the company’s Collision Center Director, Brent Rayfield, General Manager at Nyle Maxwell Supercenter, has announced.

Tammie Harper, Collision Center Director at Nyle Maxwell Collision Center, is an established collision industry veteran with over 25 years of experience.
Image caption: Tammie Harper, Collision Center Director at Nyle Maxwell Collision Center, is an established collision industry veteran with over 25 years of experience.

Her responsibilities as Collision Center Director include overseeing the collision center’s day-to-day operations, hiring and training staff, adding and maintaining key certifications where appropriate, developing dealership and 3rd party vendor relationships, reinforcing OEM partnerships, and new business development.

“Tammie brings over 25 years of collision industry experience to our company,” shares Brent Rayfield, “and in her position as Collision Center Director, she is perfectly positioned to lead our state-of-the-art, 26,000 sq ft collision center to new levels of success. Her focus on quality repairs, superior paint finishes and detailing, and customer satisfaction will enhance our ability to continue delivering premium collision repair to our customers in North Austin and nearby communities.”

“My dad was a NASCAR driver, so my entire life has been immersed in the automotive industry,” says Tammie, “and I’m honored to be working with one of Austin’s best known and highly respected automotive dealership families, Nyle Maxwell. I look forward to securing our position as the premiere North Austin Collision Center offering the finest collision repairs available while excelling in customer satisfaction.”

About Nyle Maxwell Collision Center:

Nyle Maxwell Collision Center is an Austin, Texas collision repair business and is part of the Nyle Maxwell Family of Automotive Dealerships serving the greater Austin metro, opening their first dealership in Taylor, Texas in 1984. The state-of-the-art, 26,000 sq ft collision facility offers high quality collision repair for virtually all makes and models with an emphasis on quality workmanship and the highest level of customer satisfaction available in the Austin region.

The Nyle Maxwell Collision Center utilizes advanced collision technologies, the latest equipment, and continuous training to ensure the highest quality repairs for vehicles damaged in an accident or by hail and extreme weather events. The experienced collision repair specialists at Nyle Maxwell Collision Center collectively represent decades of experience in automotive collision repair.

Nyle Maxwell Collision Center will always recommend the use of OEM replacement parts and services for all makes and models, and will negotiate with the insurance provider on behalf of the customer to ensure all repairs are completed to the customer’s 100% satisfaction. The Nyle Maxwell Family of Dealerships has been a leader in the auto industry for over 40 years. In 2025, Nyle Maxwell was named the TADA Philanthropic Leader of the Year.

For more information about the Nyle Maxwell Collision Center services please call 512-249-3280 or visit https://www.nylemaxwellcollisioncenter.com/.

MEDIA CONTACT:
Tammie Harper
512-249-3280
tharper@nylemaxwell.com

NEWS SOURCE: Nyle Maxwell Collision Center


This press release was issued on behalf of the news source (Nyle Maxwell Collision Center), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/nyle-maxwell-collision-center-brings-on-collision-industry-veteran-tammie-harper-as-collision-center-director/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132157 NOREL-3B


Education Specialist Warns Math Learning Gaps Allow Students to Advance Without True Understanding

New guidance highlights how math learning gaps often remain hidden until academic demands increase

SAN ANTONIO, Texas, Jan. 5, 2026 (SEND2PRESS NEWSWIRE) — MindBridge Math Mastery, a U.S.-based educational services organization specializing in conceptual math instruction, is issuing new guidance regarding widespread math learning gaps that allow students to advance academically without developing true understanding. Founded and led by educational clinician Susan Ardila, M.Ed., the organization reports that these gaps frequently remain undetected for years, particularly among students who rely on memorization to compensate for missing foundational concepts, leading to increased frustration and academic difficulty as math becomes more complex.

A student holds a graded math assignment, illustrating how strong grades can mask underlying gaps in conceptual understanding
Image caption: A student holds a graded math assignment, illustrating how strong grades can mask underlying gaps in conceptual understanding.

Susan Ardila, M.Ed., founder and educational clinician of MindBridge Math Mastery, said this pattern appears consistently across grade levels. “Many students appear successful because they can follow steps or remember procedures,” Ardila said. “When they are asked to explain their reasoning or apply a concept in a new way, the underlying understanding simply is not there.”

According to MindBridge Math Mastery, math learning gaps often affect students with undiagnosed dyscalculia, executive functioning challenges, or subtle learning differences that allow early compensation. As coursework becomes more abstract, those strategies frequently break down, resulting in sudden academic struggle despite years of passing grades.

MindBridge Math Mastery cautions that increased practice alone rarely resolves these issues. Repeated worksheets without conceptual clarity may heighten math anxiety and reinforce confusion. The organization emphasizes instructional approaches that prioritize reasoning, retention, and the ability to transfer learning across contexts.

MindBridge Math Mastery advises families and educators to look beyond grades and consider whether students can explain their thinking, make meaningful connections, and retain understanding over time. When instruction aligns with how students learn, the organization reports, confidence and long-term progress are more likely to follow.

More information: https://www.mindbridgemath.com

ABOUT MINDBRIDGE MATH MASTERY:

Based in the United States, MindBridge Math Mastery is an educational services organization specializing in conceptual math instruction and math learning differences. Founded by educational clinician Susan Ardila, M.Ed., the organization focuses on identifying and addressing math learning gaps through evidence-informed, student-centered approaches.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/26-0105-s2p-mindbridge-300dpi.webp

Image caption: A student holds a graded math assignment, illustrating how strong grades can mask underlying gaps in conceptual understanding.

NEWS SOURCE: MindBridge Math Mastery


This press release was issued on behalf of the news source (MindBridge Math Mastery), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/education-specialist-warns-math-learning-gaps-allow-students-to-advance-without-true-understanding/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132026 NOREL-3B


FirstClose Integrates Stewart Home Equity Solutions into OMS to Streamline Lender Workflows

AUSTIN, Texas, Dec. 10, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, announced today a new partnership with Stewart Lender Services, a division of Stewart Information Services Corporation (NYSE: STC), that enhances FirstClose’s Order Management System (OMS) with expanded home equity fulfillment capabilities.

FirstClose logo
Image caption: FirstClose Integrates Stewart Home Equity Solutions into OMS to Streamline Lender Workflows.

Through this partnership, FirstClose OMS users will gain integrated access to Stewart’s comprehensive suite of home equity title, valuation and closing solutions. By streamlining ordering and fulfillment within a single workflow, lenders can reduce manual steps, accelerate decisioning and improve borrower experiences.

“Our home equity fulfillment solutions are designed to help lenders move with speed and confidence,” said Beth Fowler, President of Stewart Lender Services. “By integrating with FirstClose we’re equipping lenders with the tools needed to accelerate loan decisioning, improve operational efficiency, and provide borrowers with a modern, streamlined home equity experience.”

Stewart’s addition to FirstClose OMS provides lenders with data, property reports, title insurance, and an E&O Policy covering home equity loans, offering options and rapid response. Stewart also offers automated title decisioning tools and a streamlined curative process, which supports faster eligibility checks and quicker clear-to-close outcomes for many loan scenarios.

“Partnering with Stewart Lender Services enhances the power of our Order Management System by giving lenders direct access to a broader set of integrated home equity solutions,” said Tedd Smith, CEO of FirstClose. “By unifying data, title, valuation and closing workflows in one place, lenders can shorten cycle times, manage risk and drive growth in the evolving home equity market while also delivering a more seamless experience for borrowers.”

Lenders using FirstClose OMS can also leverage Stewart Valuation Intelligence’s offerings, which include desktop and field appraisals, AVMs, hybrid inspections and analytics that support accurate property valuation and risk assessment. Stewart’s integrated signing and closing services offer multiple options, including mobile notary, remote online notarization (RON), and in-person electronic notarization (IPEN), which enhance convenience and operational efficiency.

About Stewart Lender Services

Stewart Lender Services, part of the Stewart family of companies (NYSE-STC), delivers an integrated suite of solutions that helps lenders accelerate decisions, reduce friction and create better customer experiences from application to close. Whether you’re a credit union, community bank or national lender, you can rely on Stewart as your single-source partner. With advanced technology, deep industry expertise and a customer-centric delivery model designed to adapt to your needs, we help you reduce cycle times, manage risk and stay Next-Move Ready for whatever the market brings next. Learn more here.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit www.firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-integrates-stewart-home-equity-solutions-into-oms-to-streamline-lender-workflows/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131619 NOREL-3B


Optimal Blue report: Lock volume posts strongest November since 2021

Resilient refinance demand driven by current rates tempers the effects of seasonal slowdown

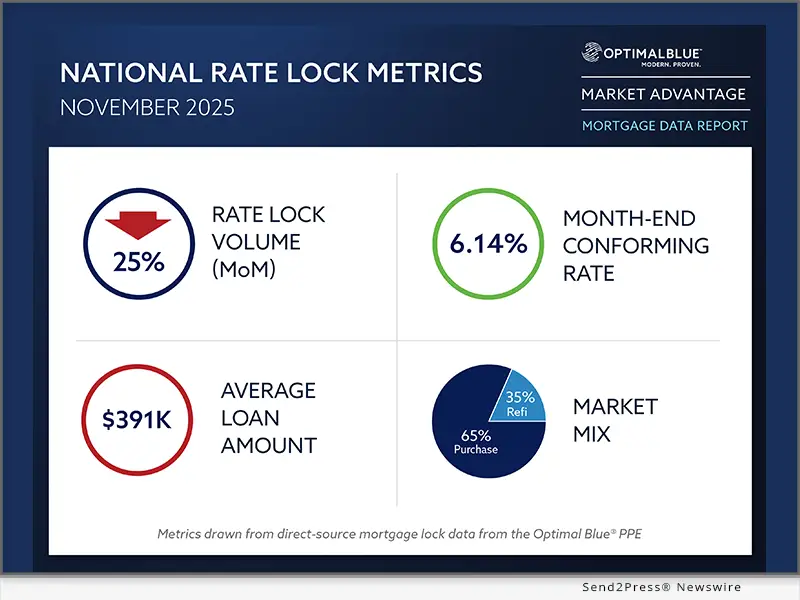
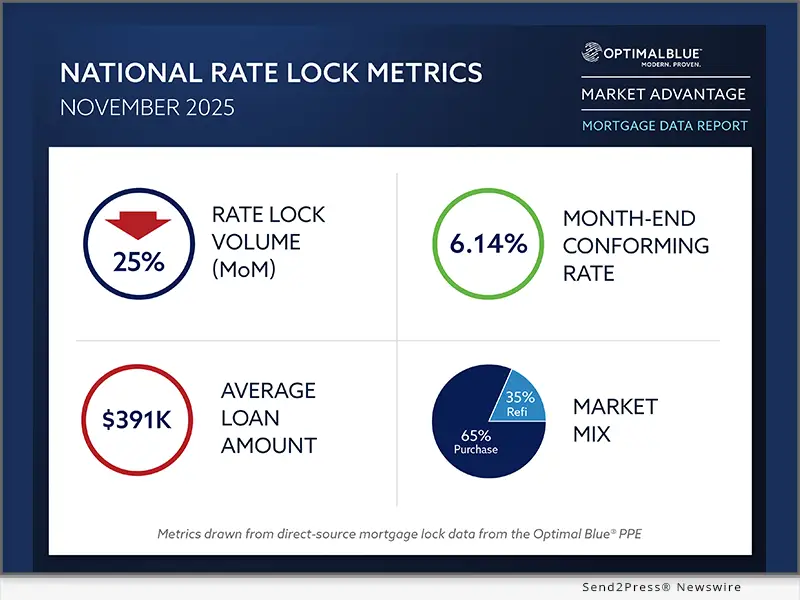
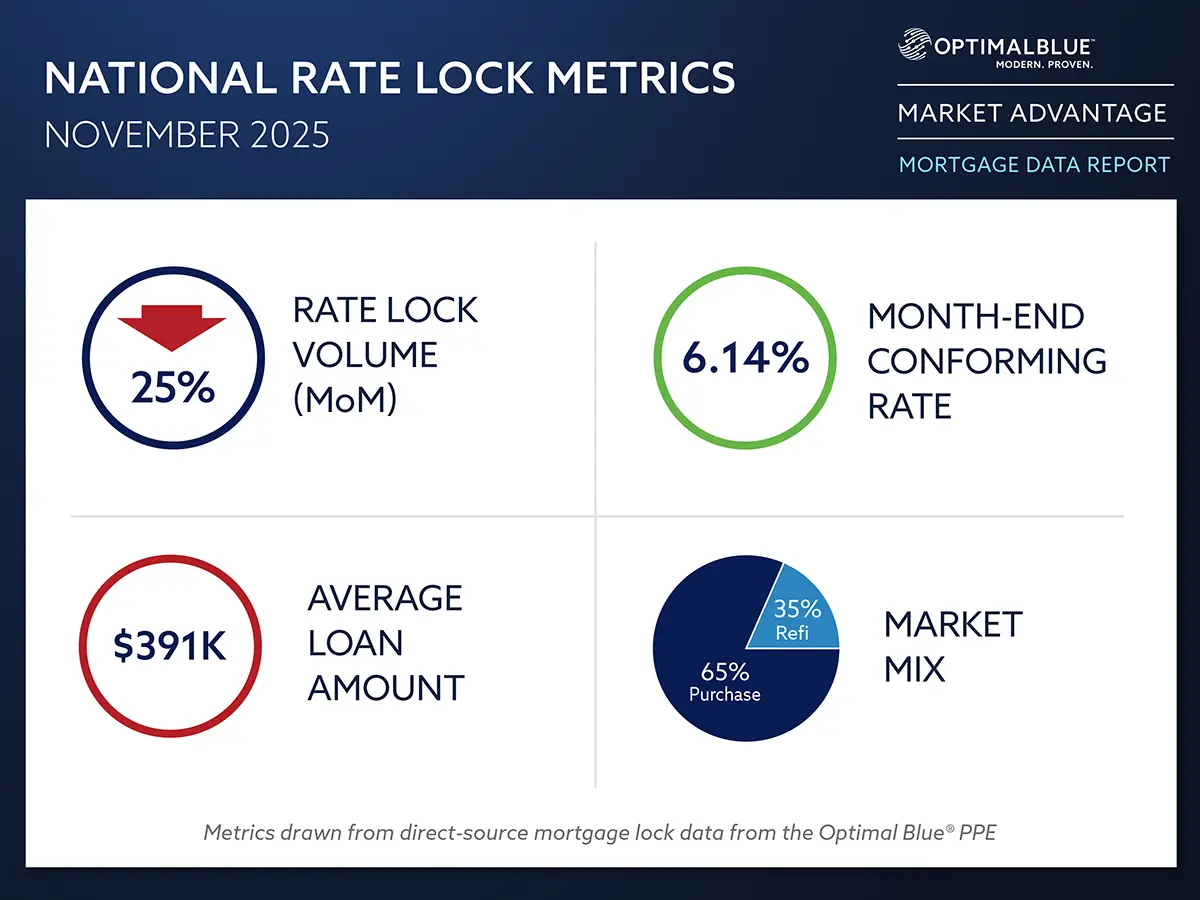
PLANO, Texas, Dec. 10, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its November 2025 Market Advantage mortgage data report, which found that total mortgage rate-lock activity declined with normal late fall seasonality, yet still marked the strongest November in four years. Total lock volume fell 25% month over month (MoM) from October but remained up 17% year over year (YoY), buoyed by historically strong refinance demand and mortgage rates holding near 6%. Rate-and-term refinances continued to outperform 2024 levels by a wide margin, finishing November up 223% YoY despite easing from September’s high. Cash-out refinances rose 29% YoY. Purchase lock activity declined 22% MoM in line with seasonal patterns and slipped 6% YoY as elevated home costs and limited inventory continued to restrain demand.

Optimal Blue's November 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s November 2025 Market Advantage mortgage data report.

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, dipped 1 basis point to 6.14% in November, marking a 53-bps improvement from the same period in 2024. FHA rates fell 5 bps to 5.99%, while VA and jumbo rates rose modestly to 5.76% (up 9 bps) and 6.44% (up 8 bps), respectively. The 10-year Treasury yield fell 11 bps to 4%, widening the mortgage rate spread by roughly 10 bps as OBMMI remained essentially flat.

“November’s data underscores a market still responding to rate relief even as seasonal patterns take hold,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Refinances remain the clear standout, with rate-and-term activity running more than triple last year’s levels and cash-outs continuing to outperform. It was a notably strong November by any measure.”

Lenders adjusted execution strategies in November as agency cash window sales rose 300 bps to 25%, interrupting the recent move toward greater securitization. Agency mortgage-backed securities (MBS) deliveries declined 100 bps to 45% after six consecutive months of gains, while bulk aggregator share dropped 300 bps to 27% and best-efforts executions increased 100 bps to 3%. The share of loans sold at the highest price tier fell 200 bps to 79%, while second- and fourth-tier deliveries increased. Mortgage servicing rights (MSRs) for conforming 30-year loans decreased 3 bps to 1.09% (a 4.36 multiple), in line with an average 15 bps decline across other OBMMI rate series.

“Execution strategies shifted meaningfully in November,” said Vough. “Lenders moved to the cash window as securitization momentum moderated, and pricing spreads broadened as more loans moved out of the top tier. These shifts point to lenders fine-tuning execution to manage price and overall delivery profile as the market settles into late-year conditions.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refis remain a major driver: Refinances accounted for 35% of all locks. Rate-and-term refinances rose 223% YoY despite slowing from early fall peaks, while cash-out refinances increased 29% YoY.
  • Purchases decline: Purchase locks fell 22% MoM and 6% YoY as elevated home costs and limited listings continued to weigh on demand.
  • Non-QM sets new record: Non-qualified mortgage share rose to 9%, the highest level recorded by Optimal Blue, with investor/debt-service-coverage-ratio (DSCR) programs accounting for a growing share of non-QM production.
  • FHA, non-conforming pick up share: Product mix shifted toward FHA and non-conforming loans (including jumbo) at the expense of conforming and VA lending, supported in part by 5.99% FHA rates.
  • PUD share ticks up slightly: Planned unit development (PUD) lock share, a reasonable proxy for new construction, rose relative to other property types but remained well below last year’s unusually high levels.

Rates and pricing

  • Rates stabilize near 6%: The OBMMI 30-year conforming fixed rate ticked down 1 bp to 6.14%. FHA fell to 5.99%, while VA and jumbo rates rose to 5.76% and 6.44%, respectively.
  • MSR values dip: MSRs for conforming 30-year loans fell 3 bps to 1.09% (a 4.36 multiple), moving in line with rate declines.
  • Spread widens to 10-year Treasury: The 10-year Treasury yield fell 11 bps to 4%, widening the mortgage rate spread by roughly 10 bps as OBMMI remained mostly unchanged.
  • Pricing tiers show more dispersion: The share of loans sold at the highest price tier dropped 200 bps to 79%, while second- and fourth-tier shares rose.

Channel and execution

  • Cash window share increases: Cash window deliveries increased to 25% (up 300 bps) as lenders shifted execution away from aggregator and securitization outlets in November.
  • MBS share pulls back: Agency MBS sales fell to 45% (down 100 bps) after six consecutive months of increases.
  • Aggregator share declines: Bulk aggregator executions dropped to 27% (down 300 bps), while best-efforts executions rose to 3% (up 100 bps).

Product mix and borrower profiles

  • Lower-rate programs gain traction: Lenders saw greater uptake in products benefiting from improved pricing, including increased FHA share at 18.8% (up 104 bps) and steady demand for jumbo and other non-conforming offerings at 17% (up 34 bps).
  • S. buyer share rises: U.S. citizens accounted for nearly 94% of locks, extending a multi-month upward trend.
  • Credit scores and loan sizes edge lower: The average credit score fell one point to 733. The average loan amount decreased to $391,323 from October’s $397,438. November loan averages ranged from $592,129 in metro New York to $295,526 in Indianapolis. Average loan-to-value ratios ranged from 69.79% in Los Angeles to 88.22% in San Antonio.

To view the full November 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/25-1210-s2p-opbluenov-300dpi.webp

Image caption: Optimal Blue’s November 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-lock-volume-posts-strongest-november-since-2021/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131605 NOREL-3B


Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer

Promotions elevate two longtime leaders into roles that deepen financial stewardship and strengthen revenue alignment as the company scales

PLANO, Texas, Dec. 8, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced the promotion of Lanny Rogers III, CPA, to chief financial officer (CFO) and Jeremy Moreno to chief revenue officer (CRO). Their combined experience and long track records of leadership position the company to advance its next stage of growth and client success with a dedicated financial strategy function and strengthened revenue oversight.

Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer
Image caption: Optimal Blue names Lanny Rogers chief financial officer and Jeremy Moreno chief revenue officer.

Rogers’ promotion to CFO reflects the company’s continued growth and investment in financial strategy as the business expands. As CFO, he will guide financial planning, forecasting, capital allocation and financial diligence on acquisitions, helping ensure the company grows with the discipline, visibility and long-term thinking required of a market leader.

“As we have continued to experience exponential growth and expansion, Lanny has been central to strengthening the financial nimbleness of our business,” said Joe Tyrrell, CEO of Optimal Blue. “He brings clarity to complex decisions, balances discipline with pragmatism and understands the financial considerations that shape every part of our operations. He has already been helping steer our financial direction, and this role formalizes his leadership as we continue to scale responsibly to continue bringing new innovation and value to our clients.”

Rogers first joined Optimal Blue in 2017 as an accounting manager and advanced to division controller in 2022 before being promoted to vice president of accounting in 2023 – his most recent role. A certified public accountant with deep expertise in financial operations, forecasting and organizational governance, he brings a collaborative approach and a steady, practical perspective to financial leadership across the company.

As CRO, Moreno will lead the company’s unified revenue and client retention function, with a focus on aligning ongoing client success, client acquisition and long-term relationship growth. His leadership brings greater cohesion across the client lifecycle and prepares Optimal Blue to respond to shifting market dynamics with agility and clarity.

“Optimal Blue had a record year in 2025 for both adding new clients and expanding relationships with our existing clients. As we continue to prioritize our current and future clients’ success across all aspects of our business, Jeremy’s leadership in the CRO function creates a unified team dedicated to this essential function,” said Tyrrell. “Jeremy has a track record of focusing on the needs of our clients and driving predictable, long-term growth for Optimal Blue, and he is the right leader to further align our strategies around client retention.”

Moreno has been part of Optimal Blue for more than a decade, most recently serving as vice president of sales, where he led acquisition strategies and supported relationship growth initiatives for lenders and partners nationwide. His experience spans operations, client services, training and retention, giving him deep insight into how customers use the company’s platform and where they need support as markets evolve.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-names-lanny-rogers-chief-financial-officer-and-jeremy-moreno-chief-revenue-officer/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131566 NOREL-3B


FirstClose appoints Alex Sirpis as vice president of sales

AUSTIN, Texas, Dec. 4, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced the appointment of Alex Sirpis as vice president of sales. In this role, Sirpis will lead the company’s sales organization, refine the go-to-market strategy and drive revenue growth as FirstClose continues expanding its presence with mortgage and home equity lenders across the country.

FirstClose appoints Alex Sirpis as vice president of sales
Image caption: FirstClose appoints Alex Sirpis as vice president of sales.

Based in Alexandria, Va., Sirpis will oversee national sales initiatives, mentor and develop a growing team of sales professionals and work closely with the executive leadership team to deepen relationships with lenders and strategic partners. His focus will include aligning sales execution with FirstClose’s product roadmap and client success goals to further accelerate adoption of the company’s technology platform.

“Alex has spent more than 25 years leading sales organizations at some of the most recognizable brands in mortgage technology,” said Tedd Smith, co-founder and chief executive officer of FirstClose. “He has repeatedly grown production in competitive markets, led dispersed sales teams through major technology rollouts and restructuring efforts and elevated performance across organizations. We’re excited to bring his experience in enterprise relationship management and sales execution to FirstClose as we continue to scale.”

Sirpis joins FirstClose with a long record of driving revenue growth and improving sales performance at companies undergoing rapid expansion. At nCino, he directed national relationship-management strategies for financial institutions and supported the company’s continued growth following its acquisition of SimpleNexus. During his tenure at SimpleNexus, he worked with enterprise lenders to expand adoption of digital mortgage and home equity technology, helping teams streamline workflows and increase user engagement.

Prior to that, Sirpis served as vice president of sales at LoanLogics and spent more than five years at Ellie Mae, where he managed enterprise accounts across the Northeast and helped drive retention and expansion among high-volume lenders. Earlier in his career, he led regional and national sales organizations at CARFAX, Prosperity Home Mortgage/Long & Foster Companies and Wachovia Bank, where he managed multi-state teams, opened new sales offices and consistently exceeded production goals. His leadership teams earned multiple President’s Club and Circle of Excellence honors during his tenure.

“I’ve spent my career helping lenders adopt technology that improves the borrower experience and strengthens operational performance,” Sirpis said. “FirstClose is solving real challenges in home equity and mortgage lending, and I’m excited to help scale a platform that gives lenders the speed and efficiency today’s market demands.”

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-appoints-alex-sirpis-as-vice-president-of-sales/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131481 NOREL-3B


FirstClose Appoints Adam Nicholson as Director of Professional Services

AUSTIN, Texas, Nov. 25, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced the appointment of Adam Nicholson as director of professional services. Nicholson will lead the company’s implementation operations, including project delivery, process optimization and cross-functional coordination to enhance the customer experience.

FirstClose Appoints Adam Nicholson as Director of Professional Services
Image caption: FirstClose Appoints Adam Nicholson as Director of Professional Services.

In this new position, Nicholson will oversee implementation strategy, guide project scopes and timelines, establish policies and standard operating procedures, and collaborate with executive leadership to ensure delivery frameworks align with organizational objectives. He will also support the refinement of onboarding practices and client-driven product enhancements to strengthen adoption and long-term value for lenders.

“Adam brings a deep background in professional services leadership across mortgage and financial technology,” said Tedd Smith, co-founder and chief executive officer of FirstClose. “His ability to build strong teams, streamline processes and deliver measurable results will help us further accelerate implementation efficiency and reinforce the value lenders experience when partnering with FirstClose.”

Nicholson has more than 12 years of experience directing implementation, customer success and professional services teams within the fintech sector. He most recently served as an enterprise client success manager at Blend. He previously held director-level roles at Polly and SimpleNexus, where he led implementation groups, established onboarding processes, reduced delivery timelines and collaborated with product and engineering teams to support customer-driven improvements. Earlier in his career, Nicholson spent six years in software implementation leadership roles at Accenture, developing deep expertise in mortgage technology, regulatory compliance and system integration.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce cost for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist the lender’s borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-appoints-adam-nicholson-as-director-of-professional-services/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131308 NOREL-3B


Lake Michigan Credit Union selects FirstClose Equity Order Management for automated home equity settlement workflows

AUSTIN, Texas, Nov. 20, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, announced today that Lake Michigan Credit Union (LMCU) has implemented FirstClose’s Equity Order Management to automate settlement workflows for its home equity lending operations.

FirstClose logo
Image caption: FirstClose, Inc.

With the implementation of FirstClose Equity Order Management, LMCU will be able to generate and track settlement orders directly within its loan origination system, apply business rules for vendor selection and ensure that completed reports and documents flow seamlessly back into the loan record. By reducing manual touchpoints and eliminating redundant data entry, the integration will deliver faster turnaround times, fewer handoffs, improved lien reporting accuracy and greater efficiency for staff and members alike.

“Home equity is an important way we support our members’ financial needs, and implementing FirstClose Equity Order Management allows us to make that process faster, easier and more reliable,” said Eric Schlagheck, vice president of mortgage processing and home equity lending at Lake Michigan Credit Union. “By streamlining the behind-the-scenes work, we’re able to focus more on delivering the level of service our members expect and deserve.”

“LMCU’s implementation of FirstClose Equity Order Management shows how technology can enhance the member experience by making the home equity process faster and more consistent,” said Tedd Smith, CEO of FirstClose. “We’re proud to support LMCU’s commitment to service by delivering automation and integrated workflows that remove friction for both staff and members.”

Headquartered in Grand Rapids, Mich., LMCU is the largest credit union in the state and one of the largest in the nation, serving more than 600,000 members. The credit union continues to invest in technology that simplifies lending processes and improves member experiences across its financial services portfolio.

FirstClose Equity Order Management is part of the company’s broader platform designed to help lenders reduce costs, improve consistency and accelerate home equity closings.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/lake-michigan-credit-union-selects-firstclose-equity-order-management-for-automated-home-equity-settlement-workflows/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131238 NOREL-3B


Velocity Credit Union Introduces ‘Buy Now, Pay Later’ to Give Members Greater Financial Flexibility

New in-house installment payment option offers affordable, flexible, and tech-forward financial solutions to meet evolving member needs

AUSTIN, Texas, Nov. 13, 2025 (SEND2PRESS NEWSWIRE) — Velocity Credit Union (Velocity) has announced the launch of a new Buy Now, Pay Later (BNPL) program designed to give members greater financial flexibility and control over their everyday spending. A financial institution with over $1 billion in assets and serving over 80,000 members, Velocity is introducing this program to further its commitment to offering comprehensive financial services to its members for every stage of their life.

Velocity Credit Union
Image caption: Velocity Credit Union.

Velocity’s BNPL program allows members to split eligible debit card purchases into predictable installment payments through its mobile and online banking platforms. Members may also choose to receive funds in their checking account prior to making a purchase, offering added flexibility when managing planned or unexpected expenses.

“Velocity Credit Union continues to put our members first with financial solutions that grow with them,” said Debbie Mitchell, President & CEO at Velocity Credit Union. “Our new Buy Now, Pay Later program adds another layer of flexibility and control, giving members a responsible, digital-first way to plan purchases, handle the unexpected, and stay financially confident while still receiving the personal support they expect from Velocity.”

The program is powered by equipifi, the leading BNPL platform built for financial institutions. Unlike many third-party BNPL providers, Velocity’s BNPL solution is fully integrated within its digital banking environment. Members can view and accept personalized offers securely and efficiently, without leaving the credit union’s trusted platform.

“BNPL is reshaping banking relationships and is a necessary feature for financial institutions to align with the evolving needs of consumers,” said Bryce Deeney, Co-Founder and CEO of equipifi. “Velocity Credit Union is setting a strong example of how credit unions can meet members’ needs with empathy by offering relevant, smart payment tools designed to improve their financial wellbeing.”

By keeping the solution in-house, Velocity ensures that members can access a safer BNPL product with terms reflective of their financial context and longstanding relationship with the credit union. This approach also enables the credit union to reinvest value generated by the program into enhanced member services, competitive rates, and greater impact in the communities it serves.

For more information, visit https://www.velocitycu.com/.

About Velocity Credit Union

Velocity Credit Union has served Central Texans for over 75 years with a mission to provide exceptional financial products, personal service, and support for the communities it serves. Membership is open to those who live or work in the five-county Austin area. Velocity Credit Union is federally insured by the National Credit Union Administration. Equal Housing Lender.

About equipifi

equipifi is the leading Buy Now, Pay Later (BNPL) platform built for financial institutions in the United States. Its white-label solution integrates with core banking and digital platforms, aligning BNPL offerings with consumers’ financial goals and banking preferences. equipifi enables institutions to boost engagement, grow market share, and deliver transparent, manageable installment options directly through their own apps. Learn more at https://www.equipifi.com/.

LOGO link for media: https://www.velocitycu.com/wp-content/uploads/2025/09/Full-Color-Stacked-scaled.jpg

NEWS SOURCE: Velocity Credit Union


This press release was issued on behalf of the news source (Velocity Credit Union), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/velocity-credit-union-introduces-buy-now-pay-later-to-give-members-greater-financial-flexibility/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P131035 NOREL-3B


Optimal Blue report: October lock volume holds second-highest level in three years

Seasonal cooling offset by resilient refinance demand and rising agency MBS executions

PLANO, Texas, Nov. 11, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its October 2025 Market Advantage mortgage data report, showing that rate-lock activity remained strong despite seasonal cooling and continued to outpace last year’s levels. Total lock volume fell 4.2% month over month (MoM) from September’s peak but was still up 18% year over year (YoY) as borrowers responded to improving affordability and narrower rate spreads.

Optimal Blue's October 2025 Market Advantage mortgage data report.
Image caption: Optimal Blue’s October 2025 Market Advantage mortgage data report.

Purchase locks declined just 1.5% in October, in line with typical seasonal patterns, while refinance lending remained a key driver of activity. Rate-and-term refinances fell 14% from September but stayed up 143% YoY, and cash-out refinances rose 6% MoM and 29% YoY.

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate – the benchmark for CME Group’s Mortgage Rate futures – dropped another 16 basis points (bps) to 6.16%, marking its lowest level since late 2023.

“October’s data speaks to the market’s resilience,” said Mike Vough, head of corporate strategy at Optimal Blue. “Purchase activity held steady and refinance demand – particularly cash-outs – remained strong. Even after September’s record pace, October delivered another standout month for originations.”

Lenders continued to strengthen execution strategies in the secondary market during October. Sales to agency mortgage-backed securities (MBS) climbed 400 bps to 46%, extending a multi-month trend of large-lender securitization growth. Deliveries to the agency cash window fell 200 bps to 30%, while aggregator bulk and best-efforts channels each dipped 100 bps. The share of loans sold at the highest price tier rose to 81%, up 300 bps, underscoring lenders’ ability to capture premium pricing even as servicing values tightened. Mortgage servicing rights (MSRs) for conforming 30-year loans increased 3 bps to 1.12% (a 4.47 multiple), moving in line with an average 6-bps gain across OBMMI rates for the month.

“October’s secondary market data reflected clear strength in execution,” said Vough. “Lenders leaned further into MBS sales and maintained access to top-tier pricing, signaling disciplined hedging and growing investor confidence. With securitization share and pricing quality both on the rise, large lenders appear well positioned to sustain profitability as production remains steady.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

VOLUME TRENDS AND MARKET COMPOSITION

  • Refis stay elevated: Rate-and-term refinances fell 14% MoM but remained up 143% YoY, while cash-outs rose 6% MoM and 29% YoY. Refinance pull-through improved to 71.6%, up 11.4 points from September. Refinances accounted for 37% of all production in October, down 176 bps from September but up 11.4 points YoY.
  • Purchases steady: Purchase locks declined 1.5% aligned to seasonal expectations, remaining strong relative to historical patterns. Purchase pull-through improved to 84.6%, up 91 bps from September.
  • Non-QM share rises: Non-qualified mortgage share edged higher, driven by gains in both investor/debt-service-coverage-ratio (DSCR) and bank statement programs.
  • FHA and conforming gain share: FHA and conforming production increased at the expense of primarily VA lending. VA refinance activity typically reacts fastest to rate reductions, leading to a front-loading of VA locks in September.
  • Single-family share climbs: Single-family production rose relative to all other property types in October, reflecting sustained strength in owner-occupied lending.

RATES AND PRICING

  • Mortgage rates decline: The OBMMI 30-year conforming fixed rate fell 16 bps to 6.16%, with FHA at 6.04%, VA at 5.67% and jumbo at 6.36%.
  • Spread tightens to 10-year: The mortgage rate spread to the 10-year Treasury narrowed 11 bps to just over 200 bps, down 46 bps from 2024 and the tightest since early 2022. The 10-year yield itself fell only 5 bps to 4.11% as the Fed’s recent rate cut was largely priced into the market, indicating that most of the mortgage rate improvement stemmed from spread compression rather than a broader interest rate decline.
  • Lender pricing strengthens: Lenders achieved higher overall pricing levels in October as spreads narrowed and execution improved across delivery channels.
  • Servicing values recover: MSRs for conforming 30-year loans rose 3 bps to 1.12% (a 4.47 multiple).

CHANNEL AND EXECUTION

  • Agency MBS execution expands: Share rose to 46% (+400 bps), while the agency cash window share of execution fell to 30% (–200 bps) and aggregator bulk and best efforts each dipped 100 bps.
  • Investor count steady: The average number of active investors held at 11, reflecting stable liquidity conditions. Historical counts ranged from 8 in November 2024 to 12 in December 2024.
  • Higher-tier pricing dominates: With 81% of loans sold at the highest pricing tier, lenders demonstrated disciplined execution strategies that offset margin pressure from rate compression.

PRODUCT MIX AND BORROWER PROFILES

  • DTIs and affordability flat: Debt-to-income ratios and first-time homebuyer share held steady, signaling sideways affordability movement.
  • Balanced composition: FHA and conforming production growth offset earlier VA surge, keeping overall mix diverse across loan types.
  • Credit profiles, loan amounts dip: The average credit score fell to 734 from 735 MoM. The average loan amount decreased to $397,438 from $403,746. October loan averages ranged from $602,646 in metro New York to $312,177 in Indianapolis. Average loan-to-value (LTV) ratios ranged from 70% in San Francisco to 87% in San Antonio.

To view the full October 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

Access this month’s podcast episode: https://market-advantage.captivate.fm/episode/episode-14.

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/25-1111-s2p-opblueoct-300dpi.webp

Image caption: Optimal Blue’s October 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-october-lock-volume-holds-second-highest-level-in-three-years/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130911 NOREL-3B
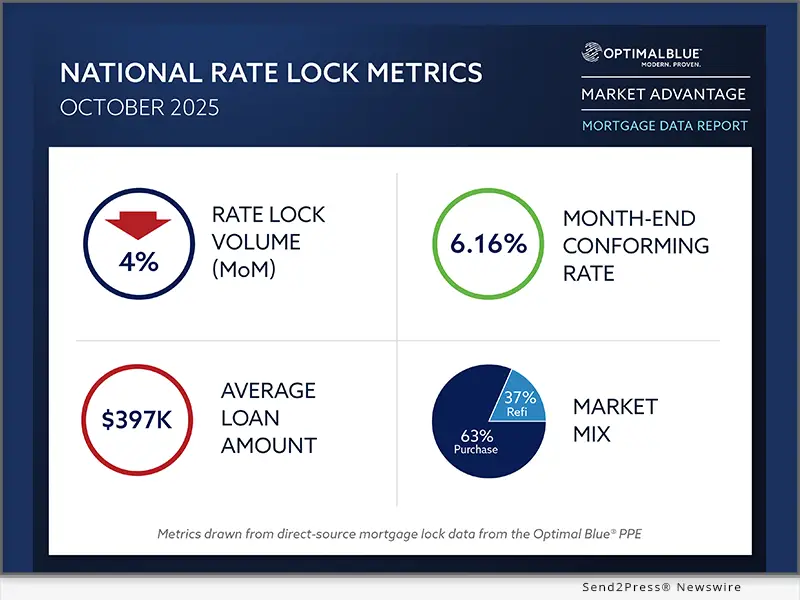
 

Click n’ Close triples warehouse line capacity to support growing One-Time Close demand

ADDISON, Texas, Nov. 6, 2025 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, today announced a significant expansion of its warehouse line capacity dedicated to its growing One-Time Close (OTC) construction-to-permanent wholesale lending business. The expansion, supported by Merchants Bank and other warehouse partners, triples Click n’ Close’s OTC capacity and follows a record fiscal year performance, reinforcing the confidence of its capital partners in the company’s financial strength and specialized business model.

Click n' Close, Inc.
Image caption: Click n’ Close, Inc.

“This expansion is both a reflection of where we’ve been and a catalyst for where we’re going,” said Jeff Bode, CEO of Click n’ Close. “Our record year showed that the One-Time Close program is not only resilient in any market but also transformative for lenders and borrowers. With this additional capacity, we can accelerate that momentum, giving our partners more flexibility and borrowers more opportunities to build and finance their homes.”

Click n’ Close’s One-Time Close program simplifies the construction-to-permanent financing process by combining land, construction, and permanent mortgage financing into a single transaction. Available across FHA, VA, USDA, and Section 184 loan types, the program is designed to make new construction more accessible — particularly for first-time buyers and borrowers in rural or underserved markets.

The program offers up to 100% loan-to-value (LTV) financing, covering land, construction and closing costs, with no down payment or minimum investment required. Borrowers may also finance the USDA Guarantee Fee up to 101% LTV. Other features include flexible debt-to-income ratios, eligibility for credit scores of 640 and above and no prepayment penalties. The program supports first-time homebuyers, allows seller or builder concessions of up to 6%, accepts eligible gifts for closing costs, and offers contingency account financing of up to 10%.

“Demand for our One-Time Close product continues to exceed expectations,” added Ian Kimball, President of Click n’ Close. “By expanding our warehouse capacity, we’re ensuring our partners have the reliable liquidity and operational support needed to serve more borrowers and builders nationwide.”

Click n’ Close’s record fiscal year was driven by growth across its government lending and servicing portfolios, strong market adoption of its SmartBuy™ down payment assistance (DPA) programs and disciplined capital and risk management. The company achieved its highest annual net profit to date while maintaining balanced channel performance across wholesale, correspondent and retail divisions.

Additional contributors included the launch of new leadership initiatives, expanded correspondent relationships and increased operational efficiencies through the use of proprietary technology and process automation. These achievements have strengthened the company’s financial foundation and deepened partner confidence, paving the way for continued investment in strategic areas, such as OTC lending.

With its newly expanded warehouse capacity, Click n’ Close is positioned to further its leadership in the construction-to-permanent lending space, offering the flexibility, scale and stability needed to help more families achieve homeownership through new construction.

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1940, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at https://www.clicknclose.com/.

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-triples-warehouse-line-capacity-to-support-growing-one-time-close-demand/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130803 NOREL-3B
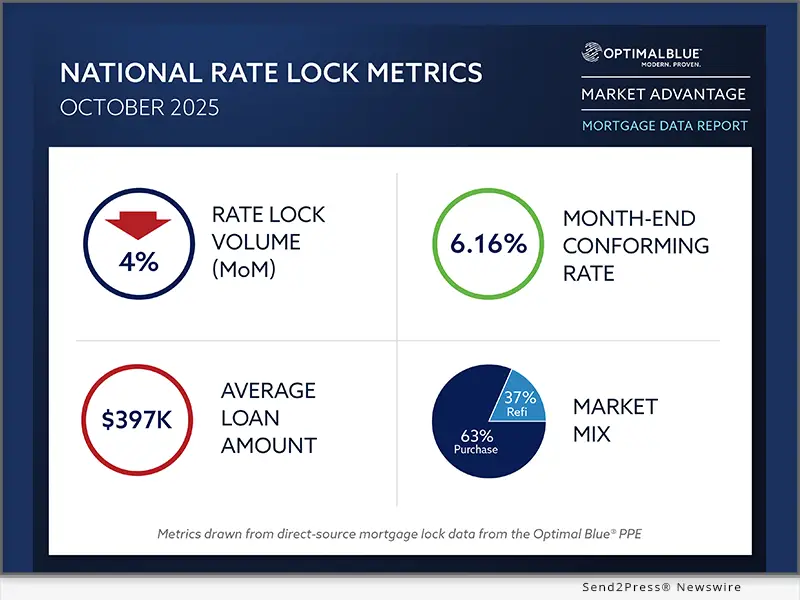
 

FirstClose celebrates 25 years of mortgage and home equity innovation

AUSTIN, Texas, Nov. 5, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, is celebrating its 25th anniversary this month. This marks a quarter-century of innovation in modernizing lending processes for residential mortgage and home equity lenders nationwide.

FirstClose logo
Image caption: FirstClose.

The anniversary comes as homeowners increasingly turn to equity amid limited refinancing opportunities in a high-rate environment. Total homeowner equity in the U.S., including homes owned outright, is estimated at $35 trillion. American homeowners with a mortgage hold about $17.6 trillion in home equity, of which approximately $11.5 trillion is considered tappable while maintaining at least 20% ownership. In addition, HELOCs and home equity loan originations increased by more than 23% year over year from 2023 to 2024, underscoring the growing importance of this lending segment.

With 225 financial institutions leveraging its platform, FirstClose has assisted lenders in meeting this demand through instant decisioning, automated workflows and vendor integrations that ensure transparency and efficiency, resulting in $129 billion in funded loans since 2015. Institutions using FirstClose’s digital prequalification tools have also experienced a 30 to 40% increase in application volume, showcasing the company’s influence on lender growth.

“Reaching 25 years reflects the trust of our clients and the dedication of our team,” said Tedd Smith, chief executive officer of FirstClose. “With demand for home equity products at an all-time high, our mission has never been more relevant: to simplify lending and empower lenders to grow. We are eager to continue shaping the future of mortgage and home equity lending.”

Looking ahead, FirstClose plans to expand its investments in this market. As the leader in home equity workflow management, including its award-winning point-of-sale (POS) platform and order management system (OMS), the company is introducing new integrations with top providers and developing innovative borrower and loan officer engagement tools, reinforcing its role as a long-term partner to lenders navigating evolving borrower needs.

Since its founding in 2000, FirstClose has evolved from a one-stop aggregator of property data and settlement services into a full end-to-end technology platform solution that enables lenders to capture the growing demand of home owners, reduce costs and deliver faster, borrower-friendly closings. Its platform integrates automated workflows, extensive vendor networks, and deep loan origination system integrations to provide a full-service, end-to-end solution that lenders and borrowers can rely upon to access funds within 7 days, compared to an industry average of 42 days. FirstClose leadership is excited to celebrate 25 years of innovation while looking to the future by impacting the entire industry with similar time and cost savings nationwide.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to home equity and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist the lender’s borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit https://www.firstclose.com/.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-celebrates-25-years-of-mortgage-and-home-equity-innovation/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130746 NOREL-3B
 

NotaryCam Enterprise Product Manager Joseph Bisaillon honored as HousingWire Tech Trendsetter

HOUSTON, Texas, Nov. 3, 2025 (SEND2PRESS NEWSWIRE) — NotaryCam®, a Stewart-owned company and a pioneering provider of remote online notarization (RON) and identity verification/authentication technology for real estate and legal transactions, today announced that Enterprise Product Manager Joseph Bisaillon has been honored as a 2025 HousingWire Tech Trendsetter. The award is given to technology leaders driving impactful innovation in the housing industry. Bisaillon is honored for his work bridging the gap between technology development and end-user needs to advance digital closing solutions through automation and integrative closing processes.

NotaryCam Enterprise Product Manager Joseph Bisaillon honored as HousingWire Tech Trendsetter
Image caption: NotaryCam Enterprise Product Manager Joseph Bisaillon honored as HousingWire Tech Trendsetter.

Bisaillon has played a central role in shaping the evolution of digital closings and driving industry-wide adoption of remote online notarization (RON), helping lenders adapt to a more connected, fully digital ecosystem. Previously, he led development of one of the first MISMO-certified RON platforms, contributing to national standards and legislation that paved the way for secure online notarization. Working with NotaryCam, Bisaillon continues driving innovation by integrating previously fragmented processes through AI tools that classify documents, validate compliance and enhance accuracy and efficiency in the signing process. His leadership in unifying RON, eSignature, IPEN, and mobile notarization within a single platform has further helped lenders and title partners accelerate closings while maintaining the highest levels of compliance and borrower trust.

Bisaillon’s guidance has also been instrumental to the success of NotaryCam’s Done For You program, which is designed to minimize disruption and make eClosings accessible through lenders’ title partners. His contributions to behind-the-scenes processes such as eNote creation and registration have enhanced efficiency, introduced innovative solutions, and ensured that lenders and title partners alike experience a seamless transition into electronic closings.

“The mortgage and title industries are at a turning point. Connecting systems, people, and data in ways that drive real efficiency and trust is critical,” said Bisaillon. “It’s a privilege to receive recognition for all that our team at NotaryCam continues to accomplish as we focus on developing technology that meets regulatory standards while simplifying the closing experience for everyone involved.”

“The 2025 Tech Trendsetters exemplify the creativity and execution that define the next generation of housing innovation,” said Clayton Collins, CEO of HW Media. “Whether it’s advancing AI and automation, strengthening data ecosystems, or elevating the digital experience for professionals and consumers alike, these leaders are shaping the future of a more efficient housing sector.”

Explore the full list of 2025 HousingWire Tech Trendsetter award recipients: https://www.housingwire.com/techtrendsetters/.

About NotaryCam, a Stewart Company

NotaryCam, a Stewart-owned company, is the leader in online notarization and mortgage eClosing solutions, having notarized documents worldwide for more than a million customers across the United States and more than 146 countries. The company’s eClose360® platform delivers the “perfect” online mortgage closing in every jurisdiction where RON is allowed and supports all eClosing scenarios with a flexible workflow for document recording and unparalleled identity verification, security and customer convenience. In addition to real estate transactions, NotaryCam provides RON services to many Fortune 500 companies as well as small and midsize businesses. The company also proudly maintains an industry-leading 99.8 percent customer satisfaction rating and the highest Net Promoter Score (NPS) amongst the best global tech brands.

Visit https://www.notarycam.com for additional information or to get a document notarized today.

About HousingWire

HousingWire is an information services company that provides unique data and research, respected business journalism and must-attend events for housing leaders to use to advance their understanding and business outcomes. Our vision is a world in which housing leaders have a complete view of the housing market, and a broad community of peers with whom they can connect. We are committed to delivering the data, analytics, media, and events that advance this vision. Because housing is too important for narrow perspectives and missed connections. Informed housing leaders are better housing leaders. A connected housing industry is a better housing industry. And the full picture always reveals new opportunities.

Explore more at www.housingwire.com.

NEWS SOURCE: NotaryCam Inc.


This press release was issued on behalf of the news source (NotaryCam Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/notarycam-enterprise-product-manager-joseph-bisaillon-honored-as-housingwire-tech-trendsetter/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130705 NOREL-3B
 

Benchmark Mortgage adds Clay McMurray as Chief Marketing Officer

DALLAS, Texas, Nov. 3, 2025 (SEND2PRESS NEWSWIRE) — Benchmark Mortgage, a full-service mortgage lender and broker based in Dallas, has added mortgage marketing professional Clay McMurray as chief marketing officer. McMurray will help Benchmark Mortgage grow its national brand to new heights, bringing the company’s story to life with the goal of helping as many homeowners as possible while attracting top mortgage originators. He brings extensive mortgage industry experience, having led and expanded other national brands.

Benchmark Mortgage Chief Marketing Officer Clay McMurray
Image caption: Benchmark Mortgage Chief Marketing Officer Clay McMurray.

McMurray previously served as vice president of marketing at ValuTrac Software, where he transformed the company’s brand identity through visual and content strategies. He also served as chief marketing and brand officer at Fairway Independent Mortgage Corp., where he expanded the company’s national brand recognition and supported its growth to a top 10 national lender.

At Benchmark Mortgage, McMurray will lead the company’s marketing initiatives as it introduces innovative mortgage strategies and marketing technology. He will also support its national events such as the annual Boot’n & Shoot’n fundraiser.

More information about Benchmark Mortgage’s philanthropic efforts can be found here: https://benchmark.us/the-benchmark-way/giving-back.

“Hiring Clay as our new chief marketing officer is a strategic decision,” said Stewart Hunter, founder and CEO of Benchmark Mortgage. “Innovation and transparency are more than ideals in our always evolving mortgage landscape — they’re necessities. Clay delivers a forward-thinking approach plus a deep understanding of how trust, technology and brand integrity drive long-term growth.”

“Clay’s vision will help us further strengthen our connection with our borrowing families, empower our partners and continue shaping a company that leads through clarity, creativity, community and purpose,” said Jim McMahan, president of Benchmark Mortgage. “Clay understands that marketing is about more than messaging — it’s about building trust. His leadership will help us continue to elevate how we serve our clients, support our team and show up in the communities where we live and work.”

“Benchmark is a built on strong values, outstanding leadership, and a genuine commitment to serving others, especially our nation’s veterans,” said Clay McMurray. “Benchmark has a powerful story and an even brighter future, and I’m thrilled to help bring that story to life in a bigger, bolder way.”

About Benchmark Mortgage

Founded in 1999, Benchmark Mortgage is a nationally recognized brand offering a wide range of mortgage products with a focus on serving veterans and first responders. The company has built a dynamic lending community by focusing on integrity and relationships. The power of creativity and innovation sets Benchmark apart from its competitors. Learn more: https://benchmark.us/

LOGO link for media: https://benchmark.us/wp-content/uploads/2015/11/Benchmark-retina-2x.png

NEWS SOURCE: Benchmark Mortgage


This press release was issued on behalf of the news source (Benchmark Mortgage), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/benchmark-mortgage-adds-clay-mcmurray-as-chief-marketing-officer/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130685 NOREL-3B
 

Click n’ Close appoints Jon Wilson as Vice President of Accounting

ADDISON, Texas, Oct. 30, 2025 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, today announced the addition of Jon Wilson as Vice President of Accounting. In this role, Wilson will oversee corporate accounting, financial reporting and process optimization, supporting the company’s continued growth and operational excellence.

Jon Wilson of Click n' Close
Image caption: Jon Wilson of Click n’ Close.

Wilson brings more than 20 years of experience in accounting and finance leadership within the mortgage and financial services sectors. Prior to joining Click n’ Close, he served as Vice President of Finance for Bay Equity, LLC, a subsidiary of Redfin Inc., where he oversaw financial operations, including audit management, warehouse certification reporting and banking relationships. Previously, Wilson held senior accounting roles at Algentis, LLC (a subsidiary of HUB International) and First Collateral Services (a subsidiary of CitiMortgage).

“Jon’s extensive background in financial management, audit oversight and operational efficiency makes him a tremendous asset to our leadership team,” said Gary McKiddy, CFO of Click n’ Close. “His experience supporting complex financial infrastructures within mortgage lending organizations will strengthen our accounting operations and position us for continued expansion.”

“I’m thrilled to join Click n’ Close and contribute to its mission of delivering innovative lending solutions,” Wilson said. “The company’s reputation for combining strong financial stewardship with forward-thinking programs like One-Time Close construction lending and down payment assistance aligns perfectly with my professional values and experience.”

Wilson holds a Bachelor of Science in Accounting from Chico State University and an MBA in Finance from Golden Gate University.

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1940, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at https://www.clicknclose.com/

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-appoints-jon-wilson-as-vice-president-of-accounting/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130561 NOREL-3B


Denise Donoghue, a.k.a. ‘The Mortgage Nerd,’ is Benchmark Mortgage’s 2025 Blue Jacket Winner

DALLAS, Texas, Oct. 28, 2025 (SEND2PRESS NEWSWIRE) — Benchmark Mortgage, a full-service mortgage lender and broker based in Dallas, has named Denise Donoghue, also known as “The Mortgage Nerd,” as its 2025 Blue Jacket winner.

2025 Blue Jacket winner Denise Donoghue
Image caption: 2025 Blue Jacket winner Denise Donoghue.

The prestigious award is given annually by Benchmark Mortgage, a community of expert mortgage consultants in more than 80 branches nationwide, to members who embody the company’s core values and demonstrate excellence in business execution.

Based in Lewisville, Texas, Donoghue is a nationally recognized mortgage advisor known for her client-first approach and dedication to financial education. A top 1% producer in the U.S., she began her career in financial services in 2006 before shifting her focus to mortgage lending to help families build long-term wealth through homeownership. Branded as “The Mortgage Nerd,” Donoghue has built a reputation for simplifying complex loan options, creating personalized strategies and empowering clients to make confident financial decisions.

“The Blue Jacket is Benchmark’s highest honor,” said Stewart Hunter, founder and CEO of Benchmark Mortgage. “It was inspired by the Masters’ Green Jacket and represents the pinnacle of recognition within our organization. Those who earn it play for it every day. It’s not about one moment — it’s about consistently showing up as your best for your family, your team, your clients and your community.”

“Denise epitomizes our core values in everything she does,” said Marty Preston, president of retail lending. “During her three years at Benchmark, she has demonstrated unwavering resolve to prioritize relationships. She has left a significant imprint on each department and every teammate.”

“Denise does so much more than loans,” Preston added. “She manages an incredibly successful branch, leads a billion-dollar division, has built a successful and revolutionary coaching company, and is growing her brand all over the country. We are incredibly proud to name her the 15th recipient of Benchmark Mortgage’s coveted Blue Jacket Award.”

About Benchmark Mortgage

Founded in 1999, Benchmark Mortgage is a nationally recognized brand offering a wide range of mortgage products with a focus on serving veterans and first responders. The company has built a dynamic lending community by focusing on integrity and relationships. The power of creativity and innovation sets Benchmark apart from its competitors. Learn more: https://benchmark.us/

NEWS SOURCE: Benchmark Mortgage


This press release was issued on behalf of the news source (Benchmark Mortgage), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/denise-donoghue-a-k-a-the-mortgage-nerd-is-benchmark-mortgages-2025-blue-jacket-winner/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130523 NOREL-3B


Click n’ Close offers free USDA lock extensions, accepts new locks during government shutdown

ADDISON, Texas, Oct. 27, 2025 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, today announced a two-part initiative to support lenders during the federal government shutdown: free lock extensions for USDA loans already in its wholesale pipeline and acceptance of new USDA locks, which will be eligible for the same free extensions through Dec. 31, 2025. The program is designed to help lenders manage rate protection and keep loans moving toward closing while normal operations are paused.

Click n' Close, Inc.
Image caption: Click n’ Close, Inc.

“Government shutdowns add uncertainty and delays that neither lenders nor borrowers can control,” said Jeff Bode, CEO of Click n’ Close. “By extending locks on loans already in process and accepting new locks with free extensions through year-end, we’re helping our partners preserve pricing and keep pipelines prepared for when agencies resume regular processing.”

Click n’ Close is one of the nation’s top USDA wholesale lenders, recognized by the U.S. Department of Agriculture as a Top Wholesale Lender Champion for two consecutive years. Through innovative programs like its SmartBuy™ proprietary down payment assistance (DPA) offering and its One-Time Close construction program, Click n’ Close has helped thousands of borrowers achieve affordable homeownership.

The company’s experienced USDA team remains available to help lenders navigate the current environment and identify solutions to keep loans moving forward. Lenders with loans requiring immediate closings are encouraged to contact their Account Executive to explore alternative fast-close options.

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1940, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at https://www.clicknclose.com/.

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-offers-free-usda-lock-extensions-accepts-new-locks-during-government-shutdown/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130464 NOREL-3B


FirstClose and Lateral Investment Management announce additional equity funding to support continued growth

AUSTIN, Texas, Oct. 17, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, Inc., a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced the completion of an additional round of equity funding, which was led by existing investor Lateral Investment Management, based in San Mateo, California.

FirstClose logo
Image caption: FirstClose.

The latest round builds on Lateral’s initial 2022 investment and underscores continued investor confidence in FirstClose’s strategy, technology and leadership team. The funds will support ongoing product development and strategic initiatives as the company strengthens its position within the home equity and mortgage lending markets.

“Lateral has been a great partner and a critical factor in our company’s growth and success to date,” said Tedd Smith, chief executive officer of FirstClose. “This new round of funding reinforces our partnership and allows us to stay focused on delivering the technology lenders need to meet rising demand for home equity lending.”

Since Lateral’s initial investment in 2022, FirstClose has expanded its capabilities and market footprint. The company introduced a real-time debt consolidation feature to its FirstClose Equity platform, which early trials showed boosted conversion rates by more than 10%. It also deepened system integrations with leading platforms, such as Encompass® by ICE Mortgage Technology™, MeridianLink and Optimal Blue, and added new executives in key leadership roles, including chief revenue officer, vice president of marketing and vice president of client success.

“When we first invested in FirstClose, we saw the potential for the company to become the technology leader in home equity lending,” said Stuart Barden, Managing Director at Lateral Investment Management. “Since then, the team has consistently delivered, expanding its client base, deepening integrations and introducing innovations that streamline the lending process. We’re proud to continue supporting FirstClose as it builds on that foundation.”

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce cost for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs and ultimately shorten closing times. For more information, visit https://www.firstclose.com/.

About Lateral Investment Management, LLC

Headquartered in San Mateo, California, Lateral is a growth-oriented private equity firm that invests in bootstrapped, founder-led technology and technology-enabled services businesses. The firm focuses on profitable, U.S. middle market companies with no prior institutional financing and makes $15 million to $75 million investments to accelerate their growth. By pursuing sub-sector focused proprietary deal origination, founder-aligned partnerships, and a systematic and proactive approach to value creation, Lateral helps to transform its portfolio companies into category leaders. For more information, visit: https://lateralim.com/.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-and-lateral-investment-management-announce-additional-equity-funding-to-support-continued-growth/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130274 NOREL-3B


Optimal Blue continues to debut new innovations across complete capital markets platform ahead of MBA Annual Convention and Expo

New data product and three platform enhancements deliver increased market transparency, pricing accuracy, counterparty oversight and trading automation

PLANO, Texas, Oct. 16, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced the launch of a new data solution to deliver increased market transparency, as well as three major platform enhancements focused on pricing accuracy, trade execution and counterparty management. Released ahead of the Mortgage Bankers Association (MBA) Annual Convention and Expo, and as the company prepares for its 2026 Optimal Blue Summit, these innovations reinforce Optimal Blue’s commitment to delivering solutions that position lenders to drive operational excellence and boost competitive performance.

Optimal Blue
Image caption: Optimal Blue.

“We continue to deliver on our promise of innovation at Optimal Blue in areas where it stands to have the greatest impact for our clients,” said Joe Tyrrell, CEO of Optimal Blue. “From AI-powered automation to real-time, transparent market insights, Optimal Blue merges a commitment to modern innovation with decades of proven experience and trust. This will be on full display at our 2026 Optimal Blue Summit, where we will be unveiling more innovations that drive the industry forward.”

  • Broker Search Data License
    Broker Search Data License is a new data product that gives wholesale and non-QM investors a previously unavailable view into broker demand across the market. Delivered monthly from Optimal Blue’s Loansifter platform, the data set includes roughly one million rows of anonymized search activity from more than 6,000 brokers, capturing early signals of what programs and loan types are gaining traction before locks occur. Unlike traditional pricing or lock data, Broker Search Data License reveals broker intent at the top of the funnel, helping investors spot emerging trends, evaluate program competitiveness and refine strategy well ahead of market shifts. Because the data is delivered in a raw, analytics-ready format, users can integrate it directly into internal intelligence environments or combine it with Optimal Blue’s Investor Pricing Insight for a complete view of broker engagement and pricing performance.
  • Pipeline Monitoring for the Optimal Blue PPE
    Pipeline Monitoring is a new feature within Optimal Blue’s product, pricing and eligibility (PPE) engine that automates the oversight of pipeline changes affecting pricing or eligibility post-initial lock. Built for seamless loan origination system (LOS) integrations, it continuously tracks loan detail changes throughout the processing and underwriting of the transaction, such as FICO scores, loan amounts and property information, instantly detecting any change that could alter pricing or eligibility rules. Loan officers receive real-time notifications through email while secondary users can manage these events through an interactive work queue, each specifying which rule triggered the alert, ensuring fast and accurate responses without borrower disruption or pricing-related closing delays. The result is greater workflow automation, reduced manual checks and stronger control over pricing and eligibility risk.
  • Competitive Trade Blotter and TBA Trading Integrations for CompassEdge
    The Competitive Trade Blotter and TBA Trading Integrations are new capabilities within CompassEdge, Optimal Blue’s hedging and loan trading solution, that modernize TBA trading by eliminating manual outreach and fragmented workflows. Traders can collect, compare and execute broker-dealer pricing directly within CompassEdge, reducing error rates and accelerating execution. The Competitive Blotter will track broker-dealer performance trends over time, giving lenders deeper visibility into pricing competitiveness. CompassEdge can connect with any broker-dealer or trading platform that supports APIs. Together, these advancements deliver faster, more accurate and more transparent trading that strengthens broker-dealer relationships and reduces operational risk.
  • Integration Studio for Comergence
    A new capability in Comergence, Optimal Blue’s counterparty oversight solution, Integration Studio lets clients connect seamlessly with external tools such as Salesforce through a no-code integration marketplace. Designed for business users rather than developers, it allows integrations to be configured and deployed in under an hour using an intuitive field mapping wizard with built-in validation and de-duplication. Hourly data syncs and integration logs keep information current and auditable, while self-service admin tools give users full control over their connections. Integration Studio offers a done-for-you approach to data integration that enables lenders, investors and partners to maintain accurate, synchronized and compliant records across systems.

“Innovation at Optimal Blue is about delivering meaningful value that addresses real lending challenges and opportunities,” said Erin Wester, chief product officer at Optimal Blue. “From greater pricing intelligence to seamless system integrations, we’re giving lenders and investors the tools they need to accelerate performance and sharpen their competitive edge.”

Wester will demonstrate Ask Obi – Optimal Blue’s AI-powered assistant that made its debut at the company’s 2025 Summit – at MBA Annual during the Tech Showcase that kicks off at 2:30 p.m. Pacific Time on Monday, October 20. Conference attendees can learn more about Optimal Blue’s new innovations by visiting the company’s booth #200 in the HUB Expo.

Optimal Blue Clients are encouraged to register early for the company’s 2026 Summit taking place February 23–25 in Scottsdale, Arizona, to take advantage of early bird pricing. Registration is open at Summit.OptimalBlue.com.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth.

To learn more about how Optimal Blue delivers measurable ROI, visit https://OptimalBlue.com/.

MULTIMEDIA:

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-continues-to-debut-new-innovations-across-complete-capital-markets-platform-ahead-of-mba-annual-convention-and-expo/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130241 NOREL-3B


Optimal Blue report: Rate rally drives 28% surge in September lock volumes

Affordability gains fuel with biggest refi wave since early 2022, MSR values dip and securitization trends point to rising large-lender market share

PLANO, Texas, Oct. 14, 2025 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its September 2025 Market Advantage mortgage data report, which showed a sharp increase in rate-lock activity as mortgage rates fell throughout the month to their lowest levels in nearly a year. Total lock volume rose 28% month over month (MoM), led by a surge in refinance lending as borrowers seized on the opportunity to lower monthly payments. Purchases also climbed 6% MoM, outperforming typical seasonal trends as improved affordability brought more buyers into the market.

Optimal Blue's September 2025 Market Advantage mortgage data report
Image caption: Image caption: Optimal Blue’s September 2025 Market Advantage mortgage data report.

“The rate rally that began in late summer accelerated in September, and borrowers reacted quickly,” said Mike Vough, head of corporate strategy at Optimal Blue. “Rate-and-term refinance locks jumped 153% month over month, lifting total refi share to 39% – the highest level we’ve seen in more than two years. That momentum also spilled into purchase lending as affordability improved, particularly for first-time homebuyers.”

The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, ended September at 6.32%, down 18 basis points (bps) from August. Jumbo rates dropped 11 bps to 6.47%, FHA fell 18 bps to 6.08% and VA declined 18 bps to 5.82%, reinforcing the broader affordability shift seen across loan types.

The report also highlighted notable movements in capital markets execution. Sales to the agency cash window and aggregators each fell 100 bps to 23% and 32% respectively, while agency mortgage-backed security (MBS) executions increased to 42% from 40%, reflecting stronger securitization activity among large lenders. The share of loans sold at the highest pricing tier climbed to 78%, up 300 bps, suggesting less focus on delivery profiles and fewer eligibility exceptions influenced pricing decisions.

“This combination of stronger pricing and greater securitization participation underscores lenders’ efforts to optimize execution as volume rebounds while maintaining profitability,” Vough said. “Even as MSR values edged down 6 bps in September, nearly eight in ten loans were sold at the highest pricing tier, showing how lenders are offsetting that compression through broader investor engagement.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Lock activity jumps: Total rate-lock volume increased 28% in September as falling rates reignited borrower demand.
  • Purchase volume rises: Purchase locks climbed 6% MoM and 9% year over year (YoY), outperforming typical late-season expectations.
  • Refinances dominate growth: Refi share expanded to 39% of all locks – the highest since early 2022 – driven by a 153% MoM increase in rate-and-term refinances and a 13% gain in cash-outs.
  • Refi pull-through improves: The pull-through rate for purchases climbed 58 bps to 83.6%. Refinance pull-through rose 82 bps to 60.2%.

Rates and pricing

  • Rates retreat across loan types: The OBMMI 30-year conforming fixed rate fell 18 bps to 6.32%. Jumbo rates dropped 11 bps to 6.47%, FHA loan rates fell 18 bps to 6.08% and VA loan rates declined 18 bps to 5.82%.
  • MSR valuations ease: Servicing values for conforming 30-year loans slipped 6 bps to 1.09% (a 4.36 multiple), mirroring rate declines and an average 30 bps drop in OBMMI levels across the month.
  • Lenders capture stronger execution: The share of loans sold at the highest pricing tier climbed to 78%, up 300 bps from August, signaling decreased focus on lender profile and eligibility and stronger focus on improved profitability.

Channel and execution

  • Securitization strengthens: Agency MBS executions increased to 42% from 40%, while deliveries to the agency cash window and aggregators fell 100 bps each to 23% and 32%, respectively.
  • Investor engagement steady: The average number of active investors held at 11, consistent with recent months as secondary market liquidity remained stable.

Product mix and borrower profiles

  • Conforming and VA gain share: Conforming and VA each picked up just over 1 percentage point of market share as borrowers in those segments moved quickly to refinance.
  • Credit profiles strengthen in refis: Average credit scores rose to 746 (up 9 points) for rate-and-term refinances and to 701 (up 7 points) for cash-outs as higher-credit borrowers responded first to lower rates.
  • DTI trends lower: Debt-to-income ratios declined for both conforming and FHA production and were down across all products YoY, signaling improving affordability.
  • FTHB participation increases: First-time homebuyer share rose in both FHA and VA production – up 1 bp each – while conforming was unchanged.
  • Loan amounts edge higher: The average loan amount was $403,746, up from $386,387 in August and $382,476 in July. September averages ranged from $605,542 in metro New York to $305,829 in Indianapolis. Average LTVs ranged from 73.57 in New York to 82.22 in Indianapolis.

To view the full September 2025 Market Advantage report, subscribe for free: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

This month’s Market Advantage podcast features Andria Lightfoot, vice president of client success at FirstClose. Access the podcast: https://market-advantage.captivate.fm/episode/episode-13.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide transparency and insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging, or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MUILTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/25-1014-s2p-optbluesep25-300dpi.webp

Image caption: Optimal Blue’s September 2025 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-rate-rally-drives-28-surge-in-september-lock-volumes/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130114 NOREL-3B


NotaryCam’s eClose 360 platform supports MISMO’s SMART Doc v3 standard for electronic HELOCs

HOUSTON, Texas, Oct. 10, 2025 (SEND2PRESS NEWSWIRE) — NotaryCam®, a Stewart-owned company and a pioneering provider of remote online notarization (RON) and identity verification / authentication technology for real estate and legal transactions, today announced that its eClose360® platform is fully compatible with the Mortgage Industry Standards Maintenance Organization’s (MISMO) newly published SMART Doc® V3 standard for electronic home equity lines of credit (eHELOCs).

NotaryCam logo
Image caption: NotaryCam.

The MISMO eHELOC standard provides a common framework for originating, closing and servicing eHELOCs by defining the data, document structure and process requirements needed to create a SMART Doc® V3 file. It establishes consistent formats for key sections of a HELOC agreement—including agreement details, advance terms, interest terms, payment terms and closing costs—and maps the required fields to ensure interoperability between lenders, settlement service providers and investors.

NotaryCam’s eClose360 platform aligns with these requirements by enabling compliant remote online notarizations, automating document tagging and preparation to reduce errors, generating and managing eNotes through government-sponsored enterprise-approved vendors, and securely depositing and delivering completed eNotes via its integrated eVault. Together, these capabilities allow lenders to originate and close eHELOCs in full compliance with MISMO’s SMART Doc V3 specification while streamlining operations and enhancing borrower convenience.

“By ensuring our platform is compatible with MISMO’s eHELOC standard, we are enabling lenders and settlement partners to confidently bring digital mortgage innovation to the home equity market,” said Brian Webster, president and CEO of NotaryCam. “Our eClose360 platform delivers the consistency and compliance required for eHELOC originations while maintaining the speed, security and borrower-friendly experience lenders expect from modern closings.”

For more information on NotaryCam’s RON and eClosing services, visit https://www.notarycam.com/.

About NotaryCam, a Stewart Company

NotaryCam, a Stewart-owned company, is the leader in online notarization and mortgage eClosing solutions, having notarized documents worldwide for more than a million customers across the United States and more than 146 countries. The company’s eClose360® platform delivers the “perfect” online mortgage closing in every jurisdiction where RON is allowed and supports all eClosing scenarios with a flexible workflow for document recording and unparalleled identity verification, security and customer convenience. In addition to real estate transactions, NotaryCam provides RON services to many Fortune 500 companies as well as small and midsize businesses and includes employment and other documents allowed by law. The company also proudly maintains an industry-leading customer satisfaction rating and the highest Net Promotor Score (NPS) amongst the best global tech brands.

Visit https://www.notarycam.com/ for additional information or to get a document notarized today.

LOGO link for media: https://www.notarycam.com/wp-content/uploads/2025/03/NotaryCam-logo-rgb-2-768×216.png

NEWS SOURCE: NotaryCam Inc.


This press release was issued on behalf of the news source (NotaryCam Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/notarycams-eclose-360-platform-supports-mismos-smart-doc-v3-standard-for-electronic-helocs/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P130021 NOREL-3B


Click n’ Close names mortgage industry veteran Ian Kimball as president

ADDISON, Texas, Oct. 8, 2025 (SEND2PRESS NEWSWIRE) — Click n’ Close, a multi-state mortgage lender, today announced the appointment of Ian Kimball as president. In this role, Kimball will oversee strategic growth initiatives, operational execution and market expansion, reporting to founder and CEO Jeff Bode.

Ian Kimball of Click n' Close
Image caption: Ian Kimball of Click n’ Close.

Kimball brings more than 25 years of leadership experience across strategy, sales, operations, technology, compliance and finance. Most recently, he served as executive director of strategy at Service First Mortgage, where he modernized enterprise technology, streamlined operations and led companywide initiatives to drive scalability and profitability. He previously held senior leadership roles at Caliber Home Loans, Bank of America Home Loans and Wells Fargo Home Mortgage, where he built high-performing sales organizations, drove national business development and executed large-scale transformation programs.

“Ian’s proven ability to scale organizations, modernize operations and forge strong partnerships will be instrumental as Click n’ Close enters its next phase of growth,” said Jeff Bode, CEO of Click n’ Close. “His forward-thinking leadership and deep industry knowledge are exactly what we need to continue delivering innovative solutions to our partners and borrowers.”

“I am honored to join Click n’ Close at such a pivotal time in the company’s journey,” Kimball said. “Jeff and the team have built a culture of innovation and resilience that has positioned the company as a leader in the industry. I look forward to building on that foundation to strengthen partnerships, expand our product offerings and continue helping more borrowers achieve homeownership.”

Kimball is a two-time FHFA Technology Sprint winner with expertise in capital markets, regulatory oversight and enterprise performance management. Known for building high-performance cultures and scalable infrastructures, he has also served as a trusted advisor to fintech firms on artificial intelligence (AI)-driven product development and digital transformation. Kimball earned a Bachelor of Arts in political science from the University of Minnesota Twin Cities.

About Click n’ Close, Inc.

Click n’ Close, Inc. is a multi-state mortgage lender serving consumers and originators through its wholesale, correspondent and retail channels. The company is an industry leader in proprietary down payment assistance (DPA) programs and a recognized leader in One-Time Close construction lending across conventional, FHA, VA, USDA and Section 184 programs. Through its 1st Tribal Lending division—the nation’s largest originator and servicer of Section 184 home loans for Native Americans—Click n’ Close extends its commitment to expanding homeownership opportunities nationwide.

In operation since 1940, Click n’ Close has remained at the forefront of mortgage innovation, pioneering the adoption of eClosings and eNotes. Backed by a strong financial foundation, Click n’ Close has the balance sheet and warehouse capacity to support and scale its specialized loan programs, providing consistent access to capital and reliable execution for its partners. By maintaining direct relationships with Fannie Mae, Freddie Mac, Ginnie Mae and private investors and servicing its loan programs in-house, the company delivers dependable liquidity, loan salability and an enhanced borrower experience.

Learn more at www.clicknclose.com.

NEWS SOURCE: Click n' Close Inc.


This press release was issued on behalf of the news source (Click n' Close Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/click-n-close-names-mortgage-industry-veteran-ian-kimball-as-president/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129944 NOREL-3B


FirstClose integrates with Optimal Blue to accelerate home equity closings

AUSTIN, Texas, Sept. 29, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, Inc., a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced a certified integration with Optimal Blue that connects FirstClose’s point-of-sale (POS) platform to Optimal Blue’s product, pricing and eligibility (PPE) engine. The integration builds on FirstClose’s ability to reduce home equity closing times from 45 days to 10 or fewer, while also giving lenders access to Optimal Blue’s trusted pricing and eligibility data. Together, these capabilities position lenders to better serve growing demand for home equity lines and second mortgages in today’s purchase-slow market.

FirstClose logo
Image caption: FirstClose logo.

Through the integration, lenders can provide borrowers with a seamless, branded application experience that combines FirstClose’s real-time property data and eligibility information with Optimal Blue’s accurate, lender-specific pricing. Together, these capabilities deliver a transparent process where consumers see precise loan options and rates while navigating their application.

“By integrating our point-of-sale experience with Optimal Blue’s pricing engine, lenders can now deliver borrowers a faster, simpler and more transparent path to access their home equity,” said Tedd Smith, chief executive officer of FirstClose.

“Americans are holding tremendous amounts of home equity, and this integration gives lenders a seamless path to present borrowers with real-time, accurate pricing information from Optimal Blue,” said Mike Vough, head of corporate strategy at Optimal Blue. “By creating more transparency of product and pricing for homeowners, lenders are better positioned to help borrowers take advantage of home equity opportunities.”

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce cost for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist the lender’s borrowers more effectively, reduce closing costs and ultimately shorten closing times. For more information, visit https://www.firstclose.com/.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-integrates-with-optimal-blue-to-accelerate-home-equity-closings/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129643 NOREL-3B


Velocity Credit Union Unveils Bold New Brand Identity and Launches Innovative Rewards Checking Account

AUSTIN, Texas, Sept. 23, 2025 (SEND2PRESS NEWSWIRE) — Velocity Credit Union, a trusted financial partner for over 75 years, today announced the launch of its refreshed brand, including a new logo, a modernized website, and updated branch locations. The updated look and feel reflects Velocity’s ongoing commitment to innovation, accessibility, and delivering an exceptional, member-first experience both in person and online.

Velocity Credit Union branches have been updated with new exterior branding and new interior enhancements
Photo caption: Velocity Credit Union Branches, including this facility on New Hope Road in Cedar Park, have been updated with new exterior branding and new interior enhancements. Other updates include a new website and Rewards Checking benefits.

“At Velocity, our brand has always stood for trust, service, and community,” said Debbie Mitchell, President and CEO. “This rebrand reflects our commitment to evolve with our members’ needs while staying true to our core values. From a fresh visual identity to digital tools that make banking easier, every detail was designed with our members in mind.”

The rebrand includes:

  • New Logo: A modern look that reflects growth, connection, and innovation.
  • Modernized Website: Enhanced design, simplified navigation, and mobile-first features.
  • Updated Branch Experience: Refreshed spaces that blend technology with personalized service.

As part of this transformation, Velocity is also introducing its Rewards Checking account—an all-in-one solution designed to help members save, grow, protect, and manage money smarter.

Rewards Checking Benefits Designed For You:

  • Earn Rewards & Build Savings – Earn rewards every time you swipe, with automatic roundups that grow your savings.
  • Get Paid Early – Access your direct deposits up to two days sooner, at no cost.
  • Bank Your Way – Manage your money anytime with mobile and online banking, Zelle®, credit score monitoring, instant transfers, and more.
  • Stay Protected – Get built-in benefits like cellphone insurance, 24/7 telehealth, and ID theft protection.

“Rewards Checking takes the everyday checking account to the next level,” said Mitchell. “Members not only enjoy modern digital convenience, but also real lifestyle and security benefits that bring more value to their financial lives.”

Members can open Rewards Checking today at any branch or online at VelocityCU.com.

For more information, visit https://www.velocitycu.com/.

About Velocity Credit Union:

Velocity Credit Union has served Central Texans for over 75 years with a mission to provide exceptional financial products, personal service, and support for the communities it serves. Membership is open to those who live or work in the five-county Austin area. Velocity Credit Union is federally insured by the National Credit Union Administration. Equal Housing Lender.

MULTIMEDIA:

Photo 300dpi: https://www.velocitycu.com/wp-content/uploads/2025/09/Cedar_Park_PR-scaled.jpg

Photo caption: Velocity Credit Union Branches, including this facility on New Hope Road in Cedar Park, have been updated with new exterior branding and new interior enhancements. Other updates include a new website and Rewards Checking benefits.

NEWS SOURCE: Velocity Credit Union


This press release was issued on behalf of the news source (Velocity Credit Union), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/velocity-credit-union-unveils-bold-new-brand-identity-and-launches-innovative-rewards-checking-account/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129528 NOREL-3B


FirstClose Strengthens Sales Team with Industry Veterans to Support Growth in Home Equity Lending

AUSTIN, Texas, Sept. 18, 2025 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, announced the expansion of its sales organization with the addition of four accomplished industry sales professionals. These new team members bring deep industry experience and proven track records that will support the company’s continued growth in home equity lending:

  • Previously with Volly and ClosingCorp, Austin Wilcox brings a strong background in sales and client success to his new role as regional vice president.
  • Darcy Hall, who most recently worked for MMI, has joined as a business development manager focused on driving pipeline growth and lender outreach.
  • Jon Del Pozo, an accomplished sales leader with experience at ICE and Ellie Mae, rounds out the team as a regional vice president.
  • Tracy Farber joins FirstClose as vice president, sales solution engineer and brings more than 15 years of experience from Ellie Mae, SimpleNexus and nCino.

FirstClose Strengthens Sales Team with Industry Veterans to Support Growth in Home Equity Lending
Image caption: FirstClose Strengthens Sales Team with Industry Veterans to Support Growth in Home Equity Lending.

“This team expansion represents our continued investment in delivering superior solutions and service to the lending community,” said John Aslanian, chief revenue officer at FirstClose. “With experienced professionals joining our sales organization, we’re positioned to help more lenders capitalize on the growing demand for home equity products while improving their operational efficiency and borrower experience.”

These strategic hires join experienced sales leaders Rob Pommier, Paul Friedrichs and Ian Voigt as the company continues to scale its go-to-market efforts. With these additions, FirstClose is now fully staffed on the sales front, positioning the company to meet increasing demand for streamlined home equity lending. The expanded team enhances FirstClose’s ability to strengthen lender relationships, accelerate sales cycles and extend the reach of its end-to-end digital platform.

“As market dynamics shift and home equity continues to gain traction, having the right people in place is essential,” said Tedd Smith, chief executive officer of FirstClose. “By expanding our front-line sales organization, we’re better equipped to support lenders looking to modernize their home equity workflows. Our technology simplifies the process, shortens time to close, and helps unlock new revenue potential, delivering real impact where it matters most.”

About FirstClose

Headquartered in Austin, Texas, FirstClose is a fintech provider delivering digital solutions purpose-built for home equity and mortgage lending. Its platform combines property data intelligence, automated workflows and vendor integrations to streamline home equity originations by reducing costs, accelerating turn times and enhancing the borrower experience. Trusted by lenders nationwide, FirstClose empowers users with configurable technology for instant decisioning and end-to-end order management. Learn more at www.firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-strengthens-sales-team-with-industry-veterans-to-support-growth-in-home-equity-lending/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129416 NOREL-3B


NotaryCam partners with Dovenmuehle and RUTH RUHL, P.C. to streamline loan modifications with remote online notarization

HOUSTON, Texas, Sept. 16, 2025 (SEND2PRESS NEWSWIRE) — NotaryCam®, a Stewart-owned company and a pioneering provider of remote online notarization (RON) and identity verification/authentication technology for real estate and legal transactions, today announced it has partnered with mortgage subservicing leader Dovenmuehle Mortgage Inc. and Texas-based law firm RUTH RUHL, P.C. to offer remote online notarization (RON) services for loan modification agreements. This collaboration aims to modernize the loss mitigation process by improving efficiency, reducing cost and friction and enhancing the borrower experience.

NotaryCam logo
Image caption: NotaryCam logo.

Using NotaryCam’s secure RON platform, Dovenmuehle and RUTH RUHL, P.C. facilitate compliant, real-time digital notarization of loan modification documents. This eliminates the need for borrowers to attend in-person appointments or coordinate limited-time windows with traditional notaries.

“Adding RON to the loss mitigation toolkit doesn’t just simplify the process for borrowers, it creates tangible operational and financial benefits for servicers and their clients,” said Brian Webster, president and CEO of NotaryCam. “By enabling faster turnaround of notarized documents, RON helps servicers meet critical deadlines, limit the accrual of daily interest costs tied to warehouse lines and support more effective hedge execution for lenders.”

For subservicers and legal partners supporting lenders and investors, every day a loan modification is delayed can increase carrying costs, create liquidity strain and risk falling outside of securitization or repooling timelines. RON shortens these cycles by eliminating common bottlenecks associated with traditional notarization, which is often a friction point for both borrowers and servicers.

“At Dovenmuehle, we’re focused on streamlining operations in ways that empower borrowers and protect our clients’ bottom line,” said Dovenmuehle Senior Vice President of Default Servicing Ron Malik. “Partnering with NotaryCam and RUTH RUHL, P.C. supports our ongoing effort to enhance loss mitigation servicing with tools and technologies that make a meaningful difference without compromising compliance.”

“This partnership is rooted in shared values, efficiency, integrity and exceptional customer service,” said Ruth Ruhl, founder and president of RUTH RUHL, P.C. “With NotaryCam’s platform, we’ve significantly reduced turn times and seen strong feedback from both servicers and borrowers. It’s clear that RON is the future of loss mitigation, and we’re proud to help lead that evolution.”

As more lenders explore the benefits of digital notarization, Dovenmuehle plans to expand its use of NotaryCam’s platform across its client base. NotaryCam’s solution is currently available in all states where RON is authorized, which includes 45 states and the District of Columbia. It is supported by a robust nationwide network of experienced, highly trained notaries.

For more information on NotaryCam’s RON services, visit https://www.notarycam.com.

About NotaryCam, a Stewart Company

NotaryCam, a Stewart-owned company, is the leader in online notarization and mortgage eClosing solutions, having notarized documents worldwide for more than a million customers across the United States and more than 146 countries. The company’s eClose360® platform delivers the “perfect” online mortgage closing in every jurisdiction where RON is allowed and supports all eClosing scenarios with a flexible workflow for document recording and unparalleled identity verification, security and customer convenience. In addition to real estate transactions, NotaryCam provides RON services to many Fortune 500 companies as well as small and midsize businesses and includes employment and other documents allowed by law. The company also proudly maintains an industry-leading customer satisfaction rating and the highest Net Promotor Score (NPS) amongst the best global tech brands.

Visit https://www.notarycam.com for additional information or to get a document notarized today.

LOGO link for media (NotaryCam): https://www.notarycam.com/wp-content/uploads/2025/03/NotaryCam-logo-rgb-2-768×216.png

NEWS SOURCE: NotaryCam Inc.


This press release was issued on behalf of the news source (NotaryCam Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/notarycam-partners-with-dovenmuehle-and-ruth-ruhl-p-c-to-streamline-loan-modifications-with-remote-online-notarization/

Copr. © 2025 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P129330 NOREL-3B