Tag Archives: Mortgage

Vertyx Introduces Homeowner Navigator, Delivering Personalized Intelligent Insights and Omnichannel Engagement for Modern Homeownership

NEW YORK, N.Y., March 24, 2026 (SEND2PRESS NEWSWIRE) — Vertyx, a provider of intelligent mortgage servicing technology built for enhanced portfolio performance, today announced Homeowner Navigator, a platform providing AI-driven homeowner insights and omnichannel engagement with borrowers. The platform is designed to help mortgage servicers maintain visibility into borrower needs after closing, when opportunities to support retention, recapture and broader relationship growth are often harder to identify.

Vertyx, Inc.
Image caption: Vertyx, Inc.

Homeowner Navigator provides homeowners a centralized platform for managing all aspects of homeownership, from maintaining their property and monitoring its value to staying on top of important financial decisions. Designed to operate across any interface, the platform delivers guidance through text and voice, online banking portals or any channel the servicer chooses to enable, seamlessly integrating into existing servicing ecosystems without disrupting the homeowner experience.

For servicers, Homeowner Navigator extends borrower engagement beyond origination and routine servicing events by delivering valuable insights from homeowner interactions to improve relationship management, identify refinancing or cross-selling opportunities and inform retention strategies. The platform can integrate data from a variety of systems, including the point-of-sale (POS), product and pricing engine (PPE), loan origination system (LOS) and customer relationship management (CRM). It is also designed to ingest servicing data in both self-serviced and subserviced environments.

“Homeownership doesn’t stop at the closing table. With Homeowner Navigator, we’re giving financial institutions a way to stay meaningfully connected with their customers long after the mortgage is originated,” said Vertyx Co-founder Ayo Opeyemi. “By delivering personalized intelligent insights about home value, equity and maintenance through channels homeowners already use, lenders can provide real value to their borrowers while strengthening long-term relationships and improving portfolio retention.”

About Vertyx

Vertyx delivers intelligent servicing with proven results. Designed to transform loan servicing from a cost center into a profit engine, the Vertyx platform streamlines servicing operations through intelligent workflow automation while converting portfolio data into actionable retention and cross-sell opportunities. With intelligence embedded directly into the servicing lifecycle, Vertyx reduces manual work and delays common in legacy environments, lowering cost-to-serve and operational risk. Vertyx also helps teams move faster with confidence by embedding compliance into everyday workflows—supporting stronger outcomes for homeowners, servicers, and investors across the mortgage lifecycle. Visit https://vertyx.io/ to learn more.

NEWS SOURCE: Vertyx


This press release was issued on behalf of the news source (Vertyx), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vertyx-introduces-homeowner-navigator-delivering-personalized-intelligent-insights-and-omnichannel-engagement-for-modern-homeownership/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P134152 NOREL-3B


MarketWise Advisors study finds mortgage lenders increase efficiency by over $1,000 per loan with Optimal Blue

Hundreds of surveyed lenders report major improvements in accuracy, operational capacity, execution and risk reduction, including 1,193% ROI for PPE clients

PLANO, Texas, March 17, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced key results of an independent analysis by consulting advisory firm MarketWise Advisors LLC quantifying the operational and financial efficiencies of its end-to-end capital markets platform and the significant value it generates per loan. The study found that mortgage lenders using Optimal Blue technology are more efficient and competitive. Optimal Blue mortgage lenders report an average net financial benefit of $1,006 per loan, reflecting measurable gains in execution quality, error reduction, automation and operational efficiency.

Optimal Blue logo.
Image caption: Optimal Blue logo.

Across the institutions studied, lenders reported improvements in accuracy, performance, operational capacity and capital markets execution. The analysis highlights both the cumulative value created when lenders adopt multiple capabilities across the Optimal Blue ecosystem and the value delivered by specific Optimal Blue technology solutions when combined with individual strategic decision-making. By combining pricing, execution, data and secondary marketing tools within a single platform, lenders are able to scale loan production more efficiently and respond more effectively to changing market conditions.

“In mortgage capital markets, every basis point matters. That is why our core goal is providing our clients with data that enables them to be more competitive. When lenders are gaining more than $1,000 per loan and achieving a rate of return of $12 for every $1 spent, that’s more than efficiency, that is operational advantage,” said Joe Tyrrell, CEO of Optimal Blue. “This independent analysis confirms what our clients experience every day: when lenders have better technology, including use-case specific AI tools backed by real expertise, the impact shows up on their bottom line.

“The results confirm that Optimal Blue delivers substantial, measurable value – contributing to clients’ ability to scale efficiently, improve execution, manage risk and achieve strong returns across the ecosystem,” said Jordan Brown, founding principal and CEO of MarketWise Advisors.

KEY FINDINGS

The analysis identified five key findings showing how lenders use Optimal Blue’s solutions to make smarter decisions, resulting in:

  • Average positive impact of more than $1,000 per loan. Across the Optimal Blue ecosystem, lenders reported an average net benefit of $1,006 per closed loan.
  • Nearly 45% increase in operational capacity. Respondents reported a 43.65% improvement in their ability to manage higher loan volume using Optimal Blue technology without requiring an increase in staff.
  • More than $400 per-loan impact from advanced hedging and secondary marketing tools. The AI-driven hedging and trading capabilities supporting strategic execution, trade optimization, MSR valuation and mark-to-market reporting produced an average financial impact of $401.43 per loan.
  • 12X ROI for Optimal Blue PPE clients. Clients reported a median return on investment of 1,193%, representing nearly $12 returned for every dollar spent with Optimal Blue.
  • Universal error reduction with measurable financial impact. 100% of survey respondents indicated that Optimal Blue helps reduce errors, with 98% reporting financial benefits tied to improved pricing and eligibility accuracy. These benefits represent an average additional gain of $181.83 per loan.

Full results from the study will be available in early May. To explore these key findings in greater detail or be notified when the full report is released, visit https://www2.optimalblue.com/2026-study.

METHODOLOGY

The ROI analysis was conducted by MarketWise Advisors LLC, a consulting advisory firm specializing in financial services technology and benchmarking. The study evaluated client-reported outcomes across Optimal Blue’s end-to-end platform, including its Product and Pricing Engine (PPE), hedging and trading solutions, data solutions and Comergence counterparty oversight solution.

More than a quarter of Optimal Blue’s nearly 1,000 unique lender customers participated in the analysis, representing a balanced mix of banks, credit unions, independent mortgage banks and housing authorities. Because Optimal Blue’s client base spans various segments of the mortgage market, the participating institutions collectively provide a representative cross-section of lender types, sizes and business models.

MarketWise Advisors applied a deliberately conservative methodology to assess value delivery, using median production volumes and client-reported outcomes to quantify financial and operational impact while avoiding assumptions that could overstate results.

NOTE ON RESULTS

Results reflect client-reported outcomes collected as part of the MarketWise Advisors analysis. Neither MarketWise Advisors LLC nor Optimal Blue provide any warranty or representation regarding performance outcomes, which rely on clients’ independent business strategies and decision-making. Individual results may vary.

About Optimal Blue

Optimal Blue powers strategic performance across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes optimize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue helps deliver measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/marketwise-advisors-study-finds-mortgage-lenders-increase-efficiency-by-over-1000-per-loan-with-optimal-blue/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133956 NOREL-3B


Argyle launches unified 3-in-1 Verification Suite for mortgage lenders

New verification product brings income, employment and asset verification together in a single, consumer-permissioned workflow

NEW YORK CITY, N.Y., March 16, 2026 (SEND2PRESS NEWSWIRE) — Argyle today announced the launch of its 3-in-1 Verification Suite, a unified verification product that brings verification of income (VOI), verification of employment (VOE) and verification of assets (VOA) together in a single, consumer-permissioned workflow. The consolidated Verification Suite enables mortgage lenders to manage multiple verification types through one interface, reducing the operational complexity of working across multiple vendors, integrations and contracts.

argyle logo
Image caption: Argyle.

The 3-in-1 Verification Suite includes direct source payroll, direct source banking and DOC VOI, which extends automation to document-based income verification when direct-source payroll connections are unavailable. Doc VOI automatically extracts and analyzes data from borrower-uploaded paystubs and W-2s, reducing manual document review while keeping loan files moving forward.

The Verification Suite is designed to streamline pre-approval, processing and underwriting workflows across the mortgage lifecycle. Along with creating a better experience for lending teams, it simplifies the verification experience for borrowers through a combined journey. Argyle is also introducing two-way communication between the point of sale (POS) and loan origination system (LOS), meaning that verifications started in the POS can be viewed and refreshed downstream without the need to toggle between systems.

“In mortgage origination, lenders typically rely on a combination of verification methods to support different borrower scenarios,” said John Hardesty, senior vice president of revenue at Argyle. “Our 3-in-1 Verification Suite brings income, employment and asset verification together into one experience, helping lenders automate more of their pipeline, reduce manual touchpoints and qualify borrowers faster.”

“It’s a really exciting development, and we’re grateful for the folks at Argyle acting on our feedback,” said Chris Sutherland, director of production strategy at American Pacific Mortgage. “With the success we’ve seen using Argyle for income and employment, adding assets was the obvious next step, and they’ve done some serious development to create continuity between the POS and LOS. The result is an intuitive borrower experience, and makes for a streamlined one-stop-shop for our branches.”

For more information about Argyle’s 3-in-1 Verification Suite, visit https://www.argyle.com/.

About Argyle:

Argyle is the leading provider of direct-source, consumer-permissioned income, employment and asset verifications, making it fast and easy to gain secure and reliable access to the most complete real-time datasets stored in consumers’ payroll and bank accounts. With Argyle, lenders automate verification workflows to save time, reduce fraud and compliance risks, lower costs and build better product experiences. As an authorized report supplier for Fannie Mae’s Desktop Underwriter® validation service and an approved service provider supporting Freddie Mac’s Loan Product Advisor® asset and income modeler (AIM), Argyle empowers mortgage lenders to auto-retrieve paystubs and W-2s, understand consumers’ ability to pay and improve loan quality—all at up to 80% less cost. Argyle’s commitment to innovation is backed by investors including Bain Capital Ventures, Checkr, Mastercard, Rockefeller Asset Management and SignalFire.

For more information on Argyle’s industry-leading verification platform, visit https://www.argyle.com/.

Tags: @withArgyle #mortgagelending #lending #underwriting #digitalmortgage #mortgagetech

NEWS SOURCE: Argyle


This press release was issued on behalf of the news source (Argyle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/argyle-launches-unified-3-in-1-verification-suite-for-mortgage-lenders/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133922 NOREL-3B


Floify powers launch of Timberline Mortgage

Community bank selects scalable point-of-sale platform to support growth across Colorado markets

BOULDER, Colo., March 16, 2026 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced that Timberline Bank has selected its platform to power its recently launched mortgage division. Founded in 2004, Timberline Bank is a Colorado-based community bank serving customers across western Colorado with locations in Grand Junction, Montrose and Aspen, delivering relationship-focused banking tailored to the needs of its local communities.

Floify powers launch of Timberline Mortgage
Image caption: Floify powers launch of Timberline Mortgage.

Launched in December 2025, Timberline Mortgage delivers personalized, competitive home financing solutions to local borrowers at each branch, backed by the strength and local commitment of its parent company.

As part of standing up the mortgage division, the six-person lending team conducted a comprehensive review of loan origination systems (LOS) and POS providers. “What became clear through the process was that Floify was offering a true partnership,” said Justin Harris, president of Timberline Mortgage. “As a newly launched mortgage division, it was critical for us to have a team that would support us as we grow. Floify’s onboarding and ongoing support gave us confidence that they’ll evolve alongside us.”

Timberline Mortgage worked closely with Floify’s implementation and training teams through twice-weekly working sessions tailored to the bank’s specific needs. Rather than requiring dedicated internal staff to manage the technology stack, Timberline has relied on Floify’s support team to configure workflows, milestones, and integrations with its LOS and pricing engine.

“We’re proud to support Timberline Bank as they launch Timberline Mortgage and deepen their commitment to community lending,” said Joshua Steffan, SVP and Group General Manager at Porch Group and Interim President and General Manager of Floify. “Community banks excel at relationship-driven service, and our role is to equip them with intuitive, scalable technology that strengthens that advantage. Floify will enable Timberline to grow confidently while delivering the seamless, high-touch experience their customers expect.”

ABOUT FLOIFY:

Floify is a fully configurable point of sale (POS) platform that streamlines the loan process with a secure application, communication and document portal between lenders, borrowers, referral partners and other mortgage stakeholders. Its Dynamic AI feature reimagines the mortgage application process by moving document collection and AI-driven data extraction to the very beginning of the process, allowing borrowers to upload key documents and have applications prepopulated with verified information, accelerating pre-approvals and simplifying the borrower experience. Floify is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more, visit https://floify.com/ or find us on social media at Facebook, LinkedIn or Twitter / X.

X: @Floify #mortgage #fintech #housingfinance

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/floify-powers-launch-of-timberline-mortgage/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133906 NOREL-3B


The Mortgage Collaborative launches enhanced benchmarking platform under new TMC Insight brand

SAN DIEGO, Calif., March 12, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s largest independent cooperative network for mortgage lenders, announced enhancements to its benchmarking platform and a rebrand from Benchmark to TMC Insight, delivering expanded dashboards and peer performance analysis for mortgage lenders.

TMC - The Mortgage Collaborative
Image caption: The Mortgage Collaborative.

TMC Insight provides participating lenders with benchmarking across operational, financial and production metrics through interactive dashboards and monthly executive summaries. The platform offers a 13-month rolling view of performance data, allowing lenders to compare current results with the previous 12 months and identify trends in their business.

The enhanced platform consolidates several reporting views into a unified dashboard where lenders can evaluate performance against peer averages across metrics, including technology costs, gain or loss on sale, loan officer compensation, warehouse operations and loan production trends.

Data can be submitted manually or integrated directly with loan origination systems to automate reporting and improve consistency.

“TMC Insight is designed to give our members a meaningful report card for their business each month,” said Jodi Hall, CEO of The Mortgage Collaborative. “When lenders can benchmark operational and financial performance against their peers, they gain insights that help them identify opportunities and make better strategic decisions.”

Future enhancements will focus on expanding available datasets and additional dashboards based on participant feedback. A planned phase of development in partnership with iEmergent will incorporate public record data to provide broader market context, enable additional benchmarking insights and support preferred partner engagement.

TMC Insight is available to participating lender members of The Mortgage Collaborative, with benchmarking insights delivered through monthly dashboards and executive summaries. Non-member lenders will have the option to subscribe to the benchmarking data in the future.

Lenders interested in participating in TMC Insight can learn more at mortgagecollaborative.com or email info@themortgagecollaborative.com.

About The Mortgage Collaborative

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders across the United States through networking, education, and advocacy. TMC fosters an environment of collaboration and innovation, ensuring its members succeed regardless of market conditions. For more information, visit mortgagecollaborative.com.

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/the-mortgage-collaborative-launches-enhanced-benchmarking-platform-under-new-tmc-insight-brand/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133861 NOREL-3B


The Mortgage Collaborative launches enhanced benchmarking platform under new TMC Insight brand

SAN DIEGO, Calif., March 12, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s largest independent cooperative network for mortgage lenders, announced enhancements to its benchmarking platform and a rebrand from Benchmark to TMC Insight, delivering expanded dashboards and peer performance analysis for mortgage lenders.

TMC - The Mortgage Collaborative
Image caption: The Mortgage Collaborative.

TMC Insight provides participating lenders with benchmarking across operational, financial and production metrics through interactive dashboards and monthly executive summaries. The platform offers a 13-month rolling view of performance data, allowing lenders to compare current results with the previous 12 months and identify trends in their business.

The enhanced platform consolidates several reporting views into a unified dashboard where lenders can evaluate performance against peer averages across metrics, including technology costs, gain or loss on sale, loan officer compensation, warehouse operations and loan production trends.

Data can be submitted manually or integrated directly with loan origination systems to automate reporting and improve consistency.

“TMC Insight is designed to give our members a meaningful report card for their business each month,” said Jodi Hall, CEO of The Mortgage Collaborative. “When lenders can benchmark operational and financial performance against their peers, they gain insights that help them identify opportunities and make better strategic decisions.”

Future enhancements will focus on expanding available datasets and additional dashboards based on participant feedback. A planned phase of development in partnership with iEmergent will incorporate public record data to provide broader market context, enable additional benchmarking insights and support preferred partner engagement.

TMC Insight is available to participating lender members of The Mortgage Collaborative, with benchmarking insights delivered through monthly dashboards and executive summaries. Non-member lenders will have the option to subscribe to the benchmarking data in the future.

Lenders interested in participating in TMC Insight can learn more at mortgagecollaborative.com or email info@themortgagecollaborative.com.

About The Mortgage Collaborative

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders across the United States through networking, education, and advocacy. TMC fosters an environment of collaboration and innovation, ensuring its members succeed regardless of market conditions. For more information, visit mortgagecollaborative.com.

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/the-mortgage-collaborative-launches-enhanced-benchmarking-platform-under-new-tmc-insight-brand/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133861 NOREL-3B


iEmergent introduces free webinar series to help lenders turn market data into mortgage growth

New educational series gives lenders a practical roadmap for identifying strategy gaps and increasing loan production

DES MOINES, Iowa, March 11, 2026 (SEND2PRESS NEWSWIRE) — iEmergent, a forecasting and advisory services firm for the financial services, mortgage and real estate industries, today announced a new webinar series, “From Gaps to Growth: A Data-Driven Roadmap to Increase Production.” The free, multi-episode series will help mortgage lenders navigate an increasingly complex mortgage environment and translate market intelligence into practical strategies for sustainable origination growth.

iEmergent introduces free webinar series to help lenders turn market data into mortgage growth
Image caption: Webinar, From Gaps to Growth: A Data-Driven Roadmap to Increase Production.

Across the series, which will span 2026 into 2027, iEmergent will walk lenders through the core elements of a successful mortgage growth strategy. Sessions cover topics such as:

  • Mapping mortgage opportunity
  • Setting production goals and aligning resources
  • Refining marketing strategies around the homebuyer journey
  • Strengthening loan products and programs to increase applications
  • Building high-performing sales teams
  • Expanding referral networks and community partnerships

The series is designed for professionals across the mortgage enterprise, including executives, sales and revenue leaders, marketing professionals, data and analytics teams, compliance professionals and loan officers. Individual episodes focus on different elements of the roadmap and are tailored to the priorities of each role.

“Many lenders know they need a clearer strategy for growth, but they lack a practical roadmap for getting there,” iEmergent CEO Laird Nossuli said. “We developed this series as a free resource to show lenders how to connect market data to real production strategies. The roadmap we’re sharing reflects strategies we’ve developed with banks, credit unions and independent mortgage banks across the country that have proven effective in helping them identify opportunity and drive measurable mortgage growth.”

Episodes will be available on demand. To register for the series kickoff, visit: https://www.iemergent.com/playbook-webinar-series/overview/

About iEmergent

Founded in 2000, iEmergent provides mortgage lending forecasts and analytics to the lending, housing and real estate industries. The company offers an extensive variety of forecast and market intelligence products, including Mortgage MarketSmart, a visualization tool that helps lenders quantify how mortgage markets will change. For more information, visit https://www.iemergent.com.

Tags: @iEmergent #MortgageLending #MortgageStrategy #HousingMarket #MortgageData #LoanProduction

Media Kit:
https://www.iemergent.com/docs/default-source/default-document-library/presskit_digitallinked.pdf

NEWS SOURCE: iEmergent


This press release was issued on behalf of the news source (iEmergent), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/iemergent-introduces-free-webinar-series-to-help-lenders-turn-market-data-into-mortgage-growth/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133817 NOREL-3B


Floify launches Dynamic Apps 2.0, enabling lenders to create fully customizable loan applications

New capability allows mortgage teams to tailor borrower applications by loan purpose while embedded AI automates data capture and underwriting preparation

BOULDER, Colo., March 10, 2026 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced the release of Dynamic Apps 2.0, a major platform enhancement that allows lenders to create fully customizable loan applications tailored to specific loan purposes, borrower scenarios and business workflows without relying on engineering resources or third-party integrations.

Floify logo
Image caption: Floify.

With Dynamic Apps 2.0, lenders can configure application experiences for loan types beyond traditional purchase and refinance mortgages, including HELOCs, construction loans, agricultural lending, non-QM products and other specialized financing options, without requiring custom development or separate application flows.

This new capability enables lenders to control which application sections and questions appear for each loan type and automate downstream processes such as document requests and disclosures, allowing them to expand into new lending categories while maintaining a single, scalable technology platform.

Dynamic Apps 2.0 works in sync with Floify’s previously embedded AI capabilities to extract borrower data from uploaded documents, auto-populate portions of the 1003 loan application, validate document uploads and assist with income calculations and underwriting preparation. By combining configurable workflows with automation, lenders can reduce manual data entry, improve application accuracy and accelerate file readiness earlier in the loan process.

“Dynamic Apps 2.0 allows lenders to design application experiences that match their workflows and product mix, whether that’s a traditional mortgage, a HELOC or a specialty lending program,” said Sydney Barber, head of product at Floify. “By tailoring the application structure to the loan purpose, lenders can capture the right information upfront and eliminate unnecessary friction for both borrowers and lending teams.”

“This is a major step forward in turning the POS into a configurable growth platform for lenders,” said Joshua Steffan, SVP and Group General Manager at Porch Group and Interim President and General Manager of Floify. “By pairing configurable applications with embedded AI automation, lenders can streamline data capture, reduce manual work and move cleaner loan files through the process faster.”

Dynamic Apps 2.0 is available now. Learn more at booth 713 at ICE Experience, March 16–18 and request a demo at https://bit.ly/3NgpE5j

ABOUT FLOIFY:

Floify is a fully configurable point of sale (POS) platform that streamlines the loan process with a secure application, communication and document portal between lenders, borrowers, referral partners and other mortgage stakeholders. Its Dynamic AI feature reimagines the mortgage application process by moving document collection and AI-driven data extraction to the very beginning of the process, allowing borrowers to upload key documents and have applications prepopulated with verified information, accelerating pre-approvals and simplifying the borrower experience. Floify is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more, visit https://floify.com/ or find us on social media at Facebook, LinkedIn or Twitter / X.

X: @Floify #mortgage #fintech #housingfinance

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/floify-launches-dynamic-apps-2-0-enabling-lenders-to-create-fully-customizable-loan-applications/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133794 NOREL-3B


Optimal Blue report: Purchase demand rebounds as mortgage market finds balance

Lock volume rises 9% month over month and nearly 40% year over year as lower rates draw borrowers back into the market

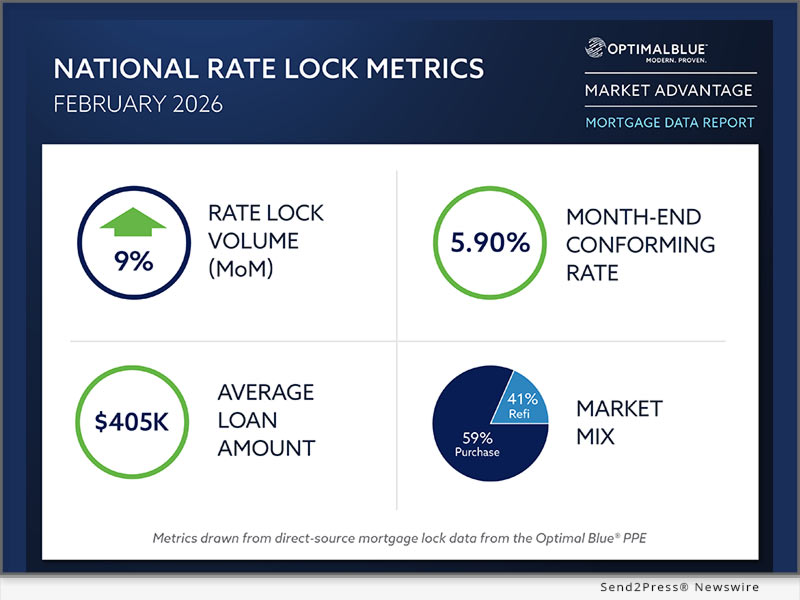
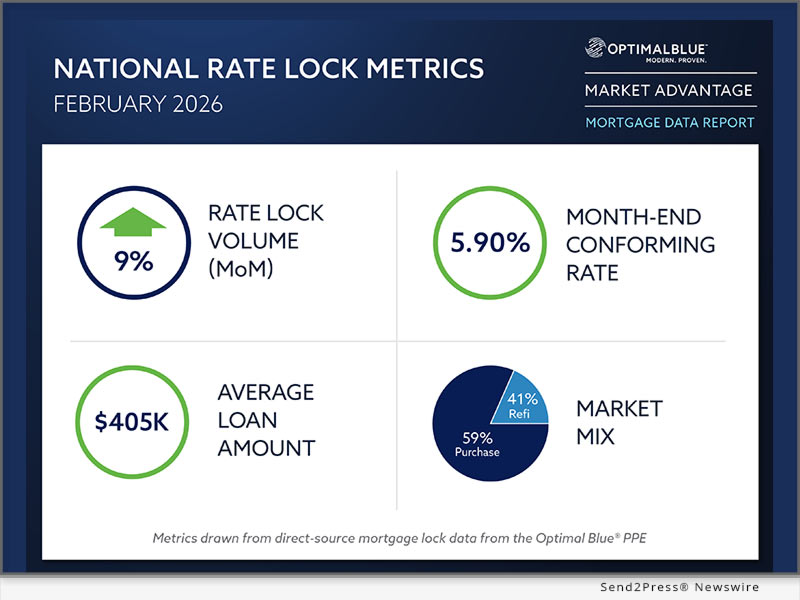
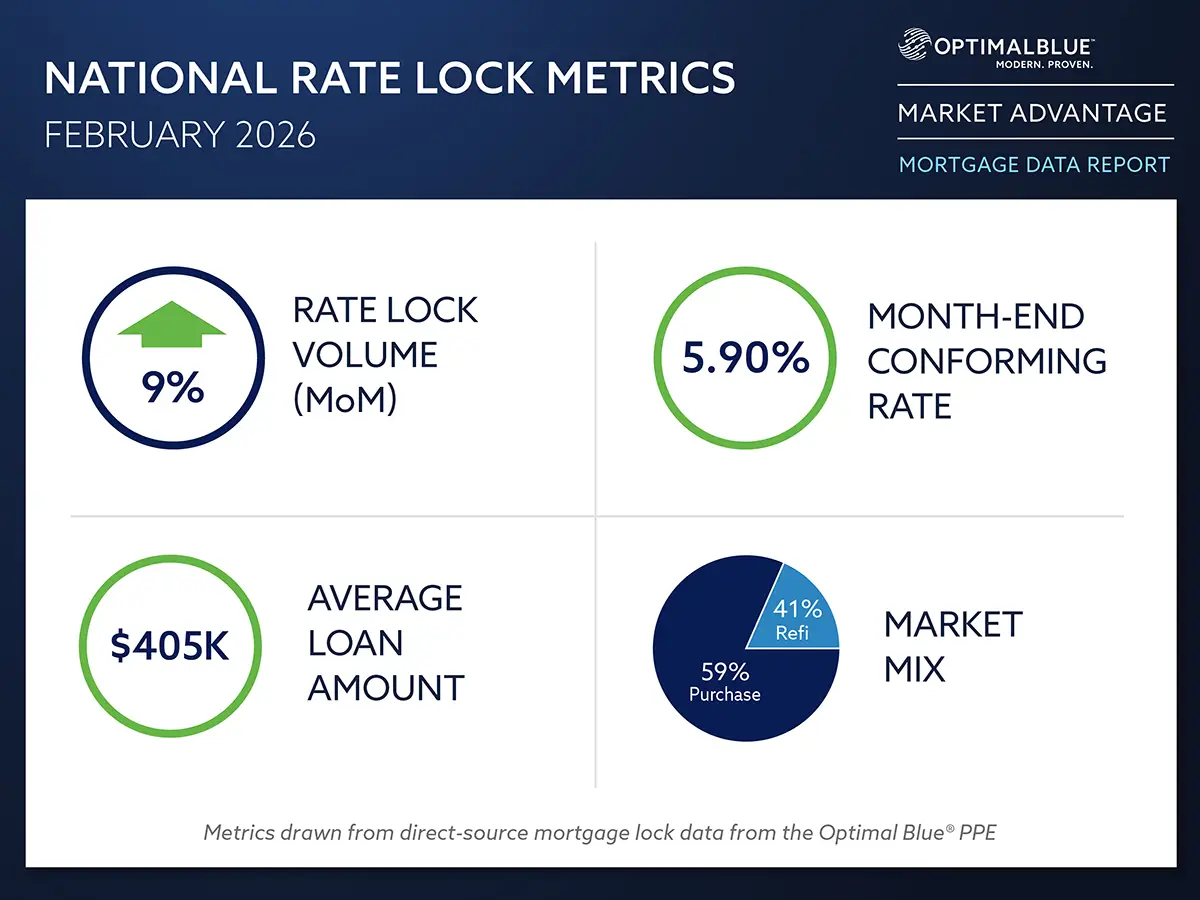
PLANO, Texas, March 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its February 2026 Market Advantage mortgage data report, showing a meaningful improvement in lock activity as lower mortgage rates helped bring purchase borrowers back into the market. Total rate-lock volume rose 9% month over month (MoM) and was nearly 40% higher year over year (YoY). Purchase lock volume increased more than 14% from January and 5% compared with February 2025, driving refinance share down to 41% of locks from 44% in January. Rate-and-term and cash-out refinance activity edged modestly higher from January but remained sharply stronger YoY.

Optimal Blue’s February 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

Mortgage rates declined across all major products in February. The OBMMI 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month at 5.90%, down 17 basis points (bps) from January. Jumbo and VA rates each declined 11 bps during the month, while FHA rates fell 13 bps. The 10-year Treasury yield closed the month at 3.97%, down nearly 30 bps, and the spread between the 10-year Treasury and the OBMMI 30-year rate widened to 193 bps as the mortgage rally lagged the broader bond market.

“February’s data shows the market settling into a healthier balance between purchase and refinance activity as rates moved lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Purchase demand is back after a slow start to the year, but refinance share is still running at 41%, which is higher than anything we saw between early 2022 and late last year.”

Secondary market data in February pointed to shifting execution dynamics as pricing spreads widened and delivery strategies evolved. Best-efforts-to-mandatory spreads widened for conventional products while hedged loan sales moved toward the agency cash window. At the same time, agency mortgage-backed securities (MBS) securitization declined and mortgage servicing rights (MSR) values increased despite falling benchmark rates.

“In an environment like this, lenders are paying close attention to how they execute and manage risk,” said Vough. “We’re seeing more active positioning across delivery channels and servicing assets as lenders balance near-term pricing with longer-term portfolio value.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance activity remains strong: Refinances accounted for 41% of total lock volume in February, down from 44% in January, as purchase demand rebounded. Rate-and-term refinance locks increased 3% MoM and 280% YoY, while cash-out refinance volume rose 1% MoM and 34% YoY.
  • Purchase demand rebounds: Purchase lock volume rose 14% MoM and 5% YoY, marking a meaningful improvement from January’s slower start to the year and helping restore a more balanced mix between purchase and refinance activity.
  • Non-conforming share expands: Conforming loans represented 53% of total lock volume in February, down 28 bps MoM but up 62 bps YoY. Non-conforming share increased to 16%, rising 91 bps MoM and 90 bps YoY. FHA loans accounted for 17% of locks, VA loans for 13% and USDA loans for 1%.
  • ARM utilization rises: Adjustable-rate mortgages comprised 10% of total lock volume in February, up 111 bps MoM and 337 bps YoY from 6.9% last year.

Rates and pricing

  • Rates move lower: The OBMMI 30-year conforming fixed rate declined 17 bps to 5.90%. Jumbo and VA rates each fell 11 bps, while FHA rates declined 13 bps. The 10-year Treasury yield declined nearly 30 bps to 3.97%, while the mortgage-to-Treasury spread widened to 193 bps.
  • MSR values increase: Mortgage servicing rights for conforming 30-year loans rose 2 bps to 1.18%, representing a 4.74 multiple, even as benchmark mortgage rates declined during the month.
  • Spreads adjust across products: Best-efforts-to-mandatory spreads widened for conventional products, with the conforming 30-year spread increasing 3 bps and the conventional 15-year spread rising 1 bp. The government 30-year spread decreased 5 bps.
  • Loan pricing mix shifts slightly: The share of loans sold at the highest price tier declined 100 bps to 78%, while second-tier executions increased 100 bps to 13%.

Channel and execution

  • Securitization share pulls back: Agency MBS securitizations accounted for 42% of hedged executions in February, down from 47% in January.
  • Cash window share jumps: Hedged loan sales to the agency cash window rose 500 bps MoM to 29%, the largest share of cash window deliveries since February 2025.

Product mix and borrower profiles

  • Credit profiles diverge: Purchase FICO scores averaged 734 in February, down 1 point MoM and 3 points YoY. Refinance credit profiles strengthened, with cash-out scores averaging 705 (up 1 point MoM and 10 points YoY) and rate-and-term scores averaging 749 (up 2 points MoM and 18 points YoY).
  • Loan amounts climb: The national average loan amount increased from $400,667 in January to $404,586 in February, marking the first time the average has remained above $400,000 for consecutive months. The national average loan-to-value ratio was 80.32%. Loan amounts ranged from $875,787 in the San Francisco Bay area to $319,743 in San Antonio, with regional LTVs spanning from 68.45% in the Bay area to 89.38% in San Antonio.

To view the full February 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Image link for media: https://www.Send2Press.com/300dpi/26-0310-s2p-opblufeb26mk-300dpi.webp

Image caption: Optimal Blue’s February 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-purchase-demand-rebounds-as-mortgage-market-finds-balance/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133788 NOREL-3B


Dovenmuehle earns Fannie Mae STAR award for servicing excellence for the seventh time

LAKE ZURICH, Ill., March 9, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (DMI), a leading mortgage subservicing company, announced today that Fannie Mae has again honored the company with their Servicer Total Achievement and Rewards™ (STAR™) Servicer Award for outstanding servicing performance during the 2025 program year. This is the seventh occasion Fannie Mae has recognized DMI for servicing excellence.

Dovenmuehle Mortgage
Image caption: Dovenmuehle Mortgage, Inc. (DMI).

Servicers achieving operational excellence across key performance metrics may receive the recognition, which underscores the expertise and dedication of DMI’s servicing team. The award also demonstrates ongoing alignment with Fannie Mae’s key performance goals and objectives. DMI earned STAR Performer recognition for General Servicing and Timeline Management.

“Being named a STAR Performer once again is a testament to the collaboration between our team, clients and industry partners,” said Matt Budy, senior vice president at DMI. “We continue to drive results and uphold the highest standards in mortgage servicing to better serve homeowners and the housing industry.”

Fannie Mae’s STAR Program provides a consistent methodology to evaluate servicer performance in accordance with Fannie Mae’s goals, sets targets and expectations to reduce Fannie Mae’s credit losses and identifies its highest-performing servicers. The majority of Fannie Mae’s total credit risk exposure is represented by servicers in the program, which are evaluated based on both the Servicer Capability Framework (SCF) operational assessment and metrics and the STAR Performance Scorecard. Servicers selected are recognized in three categories: Timeline Management, Solution Delivery and General Servicing. DMI was recognized for its General Servicing and Timeline Management.

Learn more about the STAR program here: https://singlefamily.fanniemae.com/servicing/star-program.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehle-earns-fannie-mae-star-award-for-servicing-excellence-for-the-seventh-time/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133757 NOREL-3B


Optimal Blue to host 2027 Summit February 1-3 in Scottsdale

Third annual event will return to Arizona for three days of capital markets strategy and innovation

PLANO, Texas, Feb. 25, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced it will host its 2027 Optimal Blue Summit February 1–3 at the JW Marriott Desert Ridge Resort & Spa in Scottsdale, Arizona. The annual event convenes Optimal Blue clients, integration partners and capital markets leaders from across the mortgage industry for three days of insight, collaboration and forward-looking strategy.

Optimal Blue
Image caption: Optimal Blue.

Entering its third year, the Optimal Blue Summit has become a forum for mortgage capital markets professionals to explore technology innovation, share best practices and engage in candid discussion about the market dynamics shaping the industry. The 2027 agenda will continue that focus with expert-led sessions, hands-on training and curated networking designed to equip attendees with practical strategies they can apply within their organizations.

“Our Summit is where strategy and execution come together,” said Sara Holtz, chief marketing officer at Optimal Blue. “Each year, we create an environment where clients and partners can engage directly with our leadership team, explore new platform capabilities and exchange ideas with peers facing similar market challenges. We look forward to building on this year’s momentum as we return to Arizona in 2027.”

Event highlights will include:

  • New technology unveilings: Early access to Optimal Blue’s latest platform advancements, including AI-driven capabilities, automation enhancements and expanded integrations
  • Market intelligence and economic insights: Expert perspectives on secondary market dynamics, rate trends and capital markets strategy
  • Execution and performance workshops: Tactical sessions focused on pricing accuracy, margin management, hedging and operational efficiency
  • Executive leadership forums: Discussions centered on navigating volatility and positioning for sustainable growth
  • Interactive feedback sessions: Client roundtables and product forums designed to shape the future direction of the Optimal Blue platform

Registration for the 2027 event is now open at Summit.OptimalBlue.com. Early bird pricing is available for a limited time.

Additional event details will be announced in the coming months.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-to-host-2027-summit-february-1-3-in-scottsdale/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133459 NOREL-3B


Dark Matter Technologies enables secure AI agents inside the Empower LOS for regulated lending

This release makes Dark Matter the first LOS provider to support AI agents to securely interact with Dark Matter's LOS platform using Model Context Protocol

JACKSONVILLE, Fla., Feb. 25, 2026 (SEND2PRESS NEWSWIRE) — Dark Matter Technologies (Dark Matter®), an innovative leader in mortgage technology, today announced the launch of a new capability on the Dark Matter Developer Platform, enabling lenders to use AI agents securely within the regulated mortgage environment.

Dark Matter Technologies
Image caption: Dark Matter Technologies.

Lenders are increasingly exploring AI to reduce manual work and speed access to information, but they need to do so while remaining secure and compliant. Building on top of a traditional loan origination system (LOS), APIs require significant programming skills. AI agents, on the other hand, can be built and managed by business teams and still benefit from the security, auditability and compliance of the API platform.

Model Context Protocol, an open-source standard for connecting AI applications to external systems, addresses that gap by enabling AI agents to interact with the Empower® LOS platform through a secure, managed gateway. Rather than giving AI tools direct access to loan data, the gateway validates user identity, enforces permissions, limits data exposure and creates a complete audit trail for every request. Dark Matter manages all gateway infrastructure and monitoring, while lenders remain responsible for building and deploying their AI agents.

In practice, lenders can deploy AI agents, allowing employees to ask natural-language questions about pipeline status, tasks or upcoming closings. Users see only the information they are authorized to access. All requests pass through Dark Matter’s gateway, where security and compliance controls are applied before results are returned. This capability also allows lenders to connect AI agents to other internal systems, such as customer relationship management (CRM), servicing or billing platforms, to bring new innovative solutions to life.

“By managing the secure communication layer — identity, permissions, monitoring and auditability — we give lenders the freedom to innovate with AI on top of Empower while maintaining full control and compliance,” said Vikas Rao, chief technology officer at Dark Matter Technologies. “This is the foundation lenders have been missing.”

“We believe in helping clients realize their innovative ideas, while still staying secure and compliant,” said Sean Dugan, chief executive officer of Dark Matter Technologies. “This capability allows teams to use AI to surface information faster, reduce manual effort and support day-to-day workflows — all while keeping humans firmly in control of lending decisions. It’s all about driving measurable efficiency gains without introducing new compliance risk.”

​​​​​Empower LOS customers can enable the capability now through the Dark Matter Developer Platform with support from Dark Matter’s implementation team.

ABOUT DARK MATTER TECHNOLOGIES:

Operating with the nimble nature of a startup and the disciplined maturity of one of the industry’s leading providers, Dark Matter Technologies delivers powerful technology with unparalleled automation and relentless innovation to leading mortgage lenders, servicers and companies nationwide. For more information, visit https://www.dmatter.com.

X: @dmattertech #fintech #mortgage

LOGO link for media: https://dmatter.com/wp-content/uploads/dark-matter-logo.svg

NEWS SOURCE: Dark Matter Technologies


This press release was issued on behalf of the news source (Dark Matter Technologies), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dark-matter-technologies-enables-secure-ai-agents-inside-the-empower-los-for-regulated-lending/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133447 NOREL-3B


Friday Harbor introduces dynamic pre-underwriting to help LOs structure deals that qualify and close

Income and Asset Sandbox lets lenders run income and asset scenarios against product guidelines and investor requirements in real time

SEATTLE, Wash., Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Friday Harbor, an AI pre-underwriting platform that helps loan officers assemble complete and compliant loan files in real time, today announced the launch of Income and Asset Sandbox, a new set of capabilities that allows lending teams to structure income and asset decisions in real time without committing changes prematurely or stepping outside program guidelines. The capabilities are designed to help loan officers structure deals that qualify and close earlier in the origination process.

Friday Harbor logo
Image caption: Friday Harbor.

Qualification of income and assets is among the most judgment-intensive and error-prone areas of mortgage underwriting. Small decisions about which documents to include, how to average variable income or whether to count a particular asset can materially affect eligibility and loan structure. Income and Asset Sandbox brings structure and visibility to that process earlier, when teams still have flexibility.

With Income and Asset Sandbox, lenders can instruct Friday Harbor’s AI income agent to include or exclude specific income streams, assets and supporting documentation within a live loan file and see qualifying income recalculated immediately. Teams can toggle the inclusion of documents, adjust averaging periods for variable earnings or test asset-based scenarios, all according to the loan product’s specific program, AUS findings and applicable guidelines.

Income and Asset Sandbox operates within Friday Harbor’s AI pre-underwriting platform. It reads borrower documents, compares them to the loan application and evaluates them against agency rules and lender overlays. Calculations are grounded in the documentation in real time, ensuring results reflect what can actually be supported, not hypotheticals.

“Income decisions rarely fit into neat templates, especially as borrower scenarios grow more complex,” said Theo Ellis, founder and CEO of Friday Harbor. “Our Income and Asset Sandbox gives teams a way to structure deals earlier in the process, with transparency into how each income and asset decision impacts eligibility and the path to close.”

Income and Asset Sandbox is supported by Friday Harbor’s Loan File Companion, a file-scoped AI assistant that helps teams understand how specific structuring decisions impact eligibility. Users can ask questions directly within the loan file and receive responses tied to source documents, AUS findings and policy references, keeping scenario analysis grounded in documentation while preserving lender judgment and underwriting accountability.

Lenders can learn more about Friday Harbor’s Income and Asset Sandbox or request a demo at https://fridayharbor.ai.

About Friday Harbor

Friday Harbor is an AI pre-underwriting platform that helps lenders identify and resolve potential issues earlier in the origination process. By analyzing borrower documents, appraisals and income calculations against investor guidelines and lender overlays, the platform helps teams deliver cleaner files, achieve fewer underwriting touches and improve individual productivity. For more information, visit https://fridayharbor.ai/.

Tags: #mortgagetech #AI #fintech #underwriting #incomesandbox

NEWS SOURCE: Friday Harbor


This press release was issued on behalf of the news source (Friday Harbor), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/friday-harbor-introduces-dynamic-pre-underwriting-to-help-los-structure-deals-that-qualify-and-close/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133429 NOREL-3B


Industry-first AI/ML-powered forecasting tool headlines extensive lineup of mortgage capital markets innovations unveiled at 2026 Optimal Blue Summit

On-demand Virtual Economist anchors nine advancements that unify the capital markets profitability experience across the loan life cycle

PLANO, Texas, Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today announced Virtual Economist, the first on-demand forecasting tool for mortgage capital markets leaders powered by artificial intelligence and machine learning (AI/ML), as the centerpiece of nine platform advancements unveiled at the company’s 2026 Summit. Together, the innovations further unify the capital markets profitability experience by connecting forecasting, pricing, hedging, competitive benchmarking and workflow execution within a single, end-to-end platform.

Optimal Blue
Image caption: Optimal Blue.

“The future of mortgage capital markets belongs to platforms that don’t just respond to volatility, but anticipate it,” said Joe Tyrrell, CEO at Optimal Blue. “Optimal Blue is building and continuously innovating an intelligent, connected and comprehensive ecosystem that gives lenders clarity and confidence from origination to secondary marketing, and back again. The innovations announced at our 2026 Optimal Blue Summit reflect our long-term commitment to redefining how the industry plans, prices and performs in any market environment.”

“Virtual Economist was built to address a real challenge our lender clients face – the disconnect between economic insight and day-to-day execution,” said Erin Wester, chief product officer at Optimal Blue. “By uniting public economic indicators with Optimal Blue’s proprietary lock volume data and applying AI/ML-driven forecasting, teams can test assumptions and prepare immediately through conversational and visual scenario modeling. That same data-driven approach extends across our 2026 innovations, creating a tighter feedback loop among pricing, margin management and hedge analytics so decisions are informed by real-time insight and reflected consistently across the platform.”

The 2026 Summit advancements include:

VIRTUAL ECONOMIST

In a market where profitability planning typically depends on static, macro forecasts and manual what-if exercises, Virtual Economist gives lenders on-demand predictions without the lag, labor or subjectivity of traditional approaches. The mortgage industry’s first and only AI/ML-powered forecasting tool, it combines public economic data with Optimal Blue’s lock volume data into proprietary machine learning models to deliver real-time rate and volume predictions and instant scenario analysis for strategic planning. Users can choose their preferred economist avatar and engage conversationally through voice or text, with forecasts presented visually to enhance clarity and decision-making.

PROFITABILITY CENTER

Profitability Center introduces a unified dashboard across Optimal Blue products, enabling faster navigation while surfacing cross-product market, production and profitability insights that inform decision-making before users move into deeper workflows. This central landing experience includes access to an economic calendar and predictive insights to anticipate market movement and plan hedging or pricing actions accordingly.

COMPETITIVE DATA LICENSE PLUS

Competitive Data License Plus expands Optimal Blue’s benchmarking capabilities by adding anonymized hedging and trading data to its existing lock and pricing dataset. By connecting front-end pricing behavior with back-end loan sale outcomes updated daily, it delivers deeper visibility into pull-through performance, margin from lock to sale, investor turn times and best-efforts versus mandatory execution spreads. The enhanced dataset enables lenders to model competitive positioning and execution strategy with greater precision across the capital markets life cycle.

AGENCY DIRECT (for CompassEdge)

Agency Direct in CompassEdge modernizes retained execution workflows for institutions delivering loans to Fannie Mae, Freddie Mac and the Federal Home Loan Bank system. By replacing manual spreadsheet-based tracking with a centralized environment for loan imports, coverage modeling and commitment management in CompassEdge, the solution strengthens executive visibility while reducing operational risk.

RATESHEET PRICING INSIGHTS (for CompassEdge)

Ratesheet Pricing Insights connects pricing from the Optimal Blue PPE with CompassEdge margin management, reducing the lag and manual processes that can separate pricing decisions from published rates. By syncing margin updates directly between systems and embedding market and competitive context into the workflow, it surfaces competitive insights before ratesheets are published and helps ensure rates reflect current conditions while improving margin discipline.

HEDGE COST IN THE PPE (for the Optimal Blue PPE)

Hedge Cost in the PPE embeds CompassEdge hedge analytics directly within the Optimal Blue PPE, giving lenders immediate visibility into the margin impact of extensions, renegotiations and price concessions. By surfacing hedge coupon, mark-to-market exposure and effective margin at the point of decision, it strengthens alignment between origination and secondary teams while protecting execution performance at the transaction level.

AI RULES ASSISTANT (for the Optimal Blue PPE)

AI Rules Assistant enhances Rules Optimizer, a feature within the Optimal Blue PPE that manages pricing and eligibility rules across investor relationships, by enabling administrators to “speak policy, ship rules” – i.e., input natural language and allow AI automation to generate the new rule. It identifies similar configurations and automatically builds required dependencies for review, accelerating rule creation while strengthening governance and pricing control.

ENHANCED ADMIN EXPERIENCE (for the Optimal Blue PPE and CompassEdge)

Enhanced admin experiences in both the Optimal Blue PPE and CompassEdge hedging and trading platform arm administrators with faster, more intuitive ways to configure pricing and manage investors.

In the Optimal Blue PPE, a redesigned configuration experience consolidates key tools into a straightforward, user-friendly workspace, with embedded entity selection and global Release to Production access from any screen. By reducing clicks and improving visibility across pricing configurations, it accelerates setup and governance workflows for administrators.

In CompassEdge, new administrative configuration for investor management gives users more straightforward visibility into the configuration for valuing their loan pipeline. Users can self-manage investors, execution types and more in a single, accessible place.

LOANSIFTER–COMERGENCE CONNECTION

A new connection between Optimal Blue’s Loansifter PPE for mortgage brokers and its Comergence counterparty oversight solution links promotional pricing visibility with counterparty engagement data, giving investors measurable insight into broker interaction and marketing effectiveness. By connecting broker activity with onboarding and approval workflows, the integration enables investors to capture qualified leads and accelerate TPO network growth.

Several of the announced innovations are live today, with others entering beta or phased rollout throughout 2026.

Optimal Blue’s annual Summit brings together lenders, investors and industry leaders to explore the strategies and technologies shaping the future of mortgage capital markets.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data, and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing transparency and accuracy to pipeline risk management and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data, and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

LOGO link for media: https://www.Send2Press.com/300dpi/25-0811-s2p-opblue-logo-300dpi.jpg

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/industry-first-ai-ml-powered-forecasting-tool-headlines-extensive-lineup-of-mortgage-capital-markets-innovations-unveiled-at-2026-optimal-blue-summit/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133391 NOREL-3B


Vertyx and Great Lakes Credit Union launch CUSO to support modernized mortgage servicing for credit unions

BANNOCKBURN, Ill., and NEW YORK, N.Y., Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Vertyx, a provider of intelligent mortgage servicing technology built for enhanced portfolio performance, today announced it has partnered with Great Lakes Credit Union (GLCU), through its CUSO holding company GLCU Holdings LLC, to launch Vertyx CUSO LLC, a newly formed credit union service organization (CUSO) dedicated to transforming mortgage servicing with a member-first philosophy and shared, credit union focused technology.

Vertyx, Inc.
Image caption: Vertyx, Inc. logo.

The launch follows a year of significant growth for Vertyx within the credit union ecosystem. The formation of Vertyx CUSO LLC formalizes the company’s commitment to serving as a long-term technology partner for innovative mortgage servicing teams across the credit union industry.

“Mortgage servicing has traditionally been treated as a cost center and a source of friction for both members and operations teams,” said Vertyx Co-Founder Ayo Opeyemi. “Vertyx CUSO was created to change that dynamic by enabling credit unions to retain key member relationships while transforming servicing into a driver of loyalty, efficiency and portfolio growth.”

As a credit union service organization, Vertyx CUSO LLC enables credit unions to share technology and expertise while accessing modern servicing capabilities that would be difficult to build independently. The CUSO structure reinforces Vertyx’s commitment to collaboration, scalability and long-term value creation for the credit union industry.

Vertyx delivers a mortgage servicing platform designed to help financial institutions retain servicing, modernize operations and reduce dependence on legacy systems. The platform provides a single source of truth by centralizing portfolio data, embedding automated compliance into daily workflows and supporting faster, data-driven decision-making, while an API-first architecture allows credit unions to connect with existing vendors without costly proprietary integrations and reduce operational risk.

“Vertyx has been a phenomenal partner for Mortgage Forward, our wholly owned CUSO, in helping us elevate the mortgage servicing experience for our members,” said Michael Abraham, CEO of GLCU Holdings LLC and Chief Strategy Officer at Great Lakes Credit Union. “We are excited to deepen this partnership and continue to innovate on mortgage servicing solutions that provide real value to the credit union movement.”

Learn more about Vertyx CUSO LLC here: https://vertyx.io/company/cuso.

About GLCU

Founded in 1938 and headquartered in Northern Illinois, Great Lakes Credit Union is banking for a greater good. As a not-for-profit financial cooperative with more than $1.4 billion in assets, GLCU is proud to serve 115,000 members in Chicagoland and surrounding areas, and to give back to its members and communities through education, volunteerism, and partnerships. Learn more about GLCU’s accounts, educational initiatives, and community development programs at www.glcu.org.

About Vertyx

Vertyx delivers intelligent servicing with proven results. Designed to transform loan servicing from a cost center into a profit engine, the Vertyx platform streamlines servicing operations through intelligent workflow automation while converting portfolio data into actionable retention and cross-sell opportunities. With intelligence embedded directly into the servicing lifecycle, Vertyx reduces manual work and delays common in legacy environments, lowering cost-to-serve and operational risk. Vertyx also helps teams move faster with confidence by embedding compliance into everyday workflows—supporting stronger outcomes for homeowners, servicers, and investors across the mortgage lifecycle. Visit https://vertyx.io/ to learn more.

NEWS SOURCE: Vertyx


This press release was issued on behalf of the news source (Vertyx), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vertyx-and-great-lakes-credit-union-launch-cuso-to-support-modernized-mortgage-servicing-for-credit-unions/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133384 NOREL-3B
 

Dovenmuehle’s 2025 SOC 1 and SOC 2 Type 2 reports underscore high data security standards and robust internal controls

LAKE ZURICH, Ill., Feb. 24, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc., a leading mortgage subservicing company, today announced it has successfully completed its 2025 Service Organization Control (SOC) 1® Type 2 and SOC 2® Type 2 audits. The independent examinations, conducted by public accounting and business advisory firm Plante Moran, PLLC, confirm that Dovenmuehle’s internal controls, operational processes and information security practices meet stringent standards for financial reporting integrity and the safeguarding of client data.

Dovenmuehle Mortgage
Image caption: Dovenmuehle Mortgage.

The SOC 1 Type 2 report examines the design and operating effectiveness of Dovenmuehle’s controls over financial reporting, while the SOC 2 Type 2 report reviews controls governing security, availability, processing integrity, confidentiality and privacy. The two reports offer clients independent, third-party validation of Dovenmuehle’s proven commitment to safeguarding sensitive information and delivering consistent, reliable service. The SOC 1 Type 2 report is now available to all Dovenmuehle clients via DMIConnect under the “DMI Corporate Documents” tab. Clients can also request the reports from their Account Manager.

“Our clients trust us to protect their data and support their business with the highest operational standards,” said Dovenmuehle Senior Vice President Matthew Budy. “The successful completion of our SOC audits reinforces our dedication to strong governance, system integrity, and delivering reliable service our partners can count on.”

Dovenmuehle’s SOC 2 Type 2 audit reviews the following specific trust services criteria:

  • Security: The system is protected against unauthorized access.
  • Availability: The system is available for operation and use as agreed.
  • Processing Integrity: System processing is complete, accurate, timely and authorized.
  • Confidentiality: Confidential information is safeguarded as committed.
  • Privacy: Personal information is collected, used, retained and disclosed in accordance with the company’s privacy policy.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/dovenmuehles-2025-soc-1-and-soc-2-type-2-reports-underscore-high-data-security-standards-and-robust-internal-controls/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133363 NOREL-3B
 

FirstClose and TruStage form partnership to accelerate dynamic credit union lending documentation

AUSTIN, Texas, Feb. 19, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, Inc., a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced a strategic partnership with TruStage to embed TruStage’s dynamic document engine within the FirstClose platform.

FirstClose logo
Image caption: FirstClose and TruStage form partnership to accelerate dynamic credit union lending documentation.

“Partnering with TruStage supports our commitment to giving lenders a modern documentation experience that reduces friction for both teams and members,” said Tedd Smith, chief executive officer of FirstClose. “FirstClose manages the data, workflow and delivery, while TruStage brings deep expertise in applying lender-configured compliance rules to dynamically generate documents, which will add meaningful efficiencies across the lending process.”

Under the partnership, FirstClose provides the structured data captured during initial intake and eligibility and manages document logistics, including borrower delivery and e-sign workflows. TruStage’s dynamic document engine automatically selects the appropriate documents based on real-time analysis of each transaction and lender-defined rules and compliance requirements, generating a warranted list of required disclosures and other documents without requiring lenders to build and maintain custom document groups for each product. This helps support accuracy and consistency across home-equity and mortgage lending processes.

“This collaboration allows TruStage to extend our document capabilities into the FirstClose platform in a way that respects how lenders configure and manage compliance,” said Chris Appie, president of the Compliance Solutions business at TruStage. “By applying lender-defined rules and requirements to data provided by FirstClose, we help institutions maintain control while supporting a more efficient lending experience.”

The integration is expected to be delivered in 2026.

About TruStage

TruStage® is a financially strong insurance and financial services provider, built on the philosophy of people helping people, meeting the needs of middle-market consumers and the businesses that serve them since day one. We believe a brighter financial future should be accessible to everyone, and our products and solutions help people confidently make financial decisions that work for them at every stage of life. With a culture rooted and focused on creating a more equitable society and financial system, we are deeply committed to giving back to our communities and improving the lives of those we serve today and tomorrow. For more information, visit www.trustage.com.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-and-trustage-form-partnership-to-accelerate-dynamic-credit-union-lending-documentation/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133299 NOREL-3B


ACES Q3 2025 Mortgage QC Industry Trends Report shows concentrated rise in critical defects as income and compliance findings increase

DENVER, Colo., Feb. 18, 2026 (SEND2PRESS NEWSWIRE) — ACES Quality Management® (ACES), the leading provider of enterprise quality management and control software for the financial services industry, today announced the release of its quarterly ACES Mortgage QC Industry Trends Report covering Q3 2025. The report analyzes post-closing quality control data derived from the ACES Quality Management & Control® software.

ACES Quality Management
Image caption: ACES Quality Management.

Key findings from the Q3 2025 ACES Mortgage QC Industry Trends Report include:

  • The overall critical defect rate increased 18.5%, rising from 1.51% in Q2 2025 to 1.79% in Q3 2025.
  • Income/Employment defects increased 47.6%, rising from 18.45% to 27.24% of all critical defects and remaining the largest defect category.
  • Legal/Regulatory/Compliance defects increased 16.8%, rising from 16.24% to 18.97%.
  • Borrower/Mortgage Eligibility defects decreased 56.5%, declining from 15.87% to 6.90%.
  • Purchase defect share decreased to 62.65%, while refinance defect share increased to 37.35% as refinance review share expanded.
  • Conventional loans accounted for 57.18% of all critical defects, FHA for 31.10% and VA for 11.00%, reflecting relative stability across products with modest shifts in defect concentration.

“While the overall critical defect rate increased again in Q3 2025, the underlying data points to a market adjusting to a shifting mix rather than a broad decline in manufacturing quality,” said Nick Volpe, executive vice president of ACES Quality Management. “The increase was driven primarily by concentrated deterioration in income- and compliance-related findings, reinforcing the importance of documentation integrity and disciplined validation as refinance activity expands and lenders continue to operate lean.”

Findings for the Q3 2025 ACES Mortgage QC Industry Trends Report are based on post-closing quality control data derived from the ACES Quality Management and Control® benchmarking system and incorporate data from prior quarters, where applicable. All reviews and defect data evaluated for the report were based on loan audits selected by lenders for full file reviews. The Mortgage QC Industry Trends Reports are available for download, free of charge, at https://www.acesquality.com/resources/reports.

About ACES Quality Management

ACES Quality Management is the leading provider of enterprise quality management and control software for the financial services industry. The nation’s most prominent lenders, servicers and financial institutions rely on ACES Quality Management & Control® Software to improve audit throughput and quality while controlling costs, including:

  • Over 70% of the top 20 independent mortgage lenders;
  • 7 of the top 10 loan servicers;
  • 11 of the top 30 banks; and
  • 3 of the top 5 credit unions in the United States.

Unlike other quality control platforms, ACES Flexible Audit Technology® enables independent mortgage lenders and financial institutions to easily manage and customize the system to their specific needs without relying on IT or outside resources. With ACES’ AI-powered capabilities, audit teams can translate complexity into clear insights and accelerate performance.

Using a customer-centric approach, ACES clients get responsive support and access to our experts to maximize their investment. For more information, visit https://www.acesquality.com/ or call 1-800-858-1598.

LOGO link for media: https://www.acesquality.com/assets/images/aces-logo.svg

NEWS SOURCE: ACES Quality Management


This press release was issued on behalf of the news source (ACES Quality Management), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/aces-q3-2025-mortgage-qc-industry-trends-report-shows-concentrated-rise-in-critical-defects-as-income-and-compliance-findings-increase/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133256 NOREL-3B
 

OCCU selects Floify to support scalable, member-centric lending

AI-enabled point-of-sale platform to streamline the lending experience from application to funded loan

BOULDER, Colo., Feb. 17, 2026 (SEND2PRESS NEWSWIRE) — Floify, the mortgage industry’s leading point-of-sale (POS) solution, today announced that OCCU has selected Floify to support its next phase of member-centric lending and long-term growth. OCCU is a member-owned, not-for-profit credit union based in Eugene, Oregon, with more than 284,000 members.

OCCU selects Floify to support scalable, member-centric lending
Image caption: OCCU selects Floify to support scalable, member-centric lending.

OCCU evaluated new technology as part of a broader effort to modernize its mortgage operations, focusing on improving workflow efficiency, strengthening communication, and ensuring the organization could support future growth in an increasingly competitive marketplace.

During its evaluation, OCCU found that while many vendors offered similar baseline functionality, Floify differentiated itself through its collaborative approach, best-in-class service model and ability to support future growth without disruption.

“Member expectations continue to evolve, and we wanted a solution that supports a truly holistic lending experience while giving us the ability to scale,” said Bill Bolton, vice president, mortgage strategy and planning at OCCU. “Floify stood out not just for its core functionality, but for its approach to partnership. Early on, it was clear that the Floify team understood our vision, where we want to grow and how their forward-thinking roadmap, including enhancements and AI, can get us there.”

Through the partnership, OCCU expects to improve file flow visibility, reduce back-and-forth communication, and deliver more seamless experiences for both loan officers and borrowers. Floify’s streamlined integrations will also help OCCU scale operations while maintaining a high standard of service.

“We’re proud to partner with OCCU as they continue to invest in technology that puts members first,” said Joshua Steffan, SVP and Group General Manager at Porch Group and Interim President and General Manager, Floify. “Their focus on experience, scalability and long-term growth aligns perfectly with how we build and evolve our platform.”

ABOUT FLOIFY:

Floify is a fully configurable point of sale (POS) platform that streamlines the loan process with a secure application, communication and document portal between lenders, borrowers, referral partners and other mortgage stakeholders. Its Dynamic AI feature reimagines the mortgage application process by moving document collection and AI-driven data extraction to the very beginning of the process, allowing borrowers to upload key documents and have applications prepopulated with verified information, accelerating pre-approvals and simplifying the borrower experience. Floify is a subsidiary of Porch Group, Inc. (“Porch Group”) (NASDAQ: PRCH). For more, visit https://floify.com/ or find us on social media at Facebook, LinkedIn or Twitter / X.

ABOUT OCCU:

OCCU is a not-for-profit financial cooperative with more than $3.5 billion in assets. The credit union was founded in Eugene, Oregon, in 1956 and remains headquartered there. OCCU has an expanding network of branches and digital tools to provide its more than 284,000 member-owners with a full suite of financial products and services. Membership is open to anyone living or working in most of Oregon, southwest Idaho and anywhere in Washington. Learn more at MyOCCU.org.

X: @Floify #mortgage #fintech #housingfinance @oregonccu

NEWS SOURCE: Floify


This press release was issued on behalf of the news source (Floify), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/occu-selects-floify-to-support-scalable-member-centric-lending/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133193 NOREL-3B
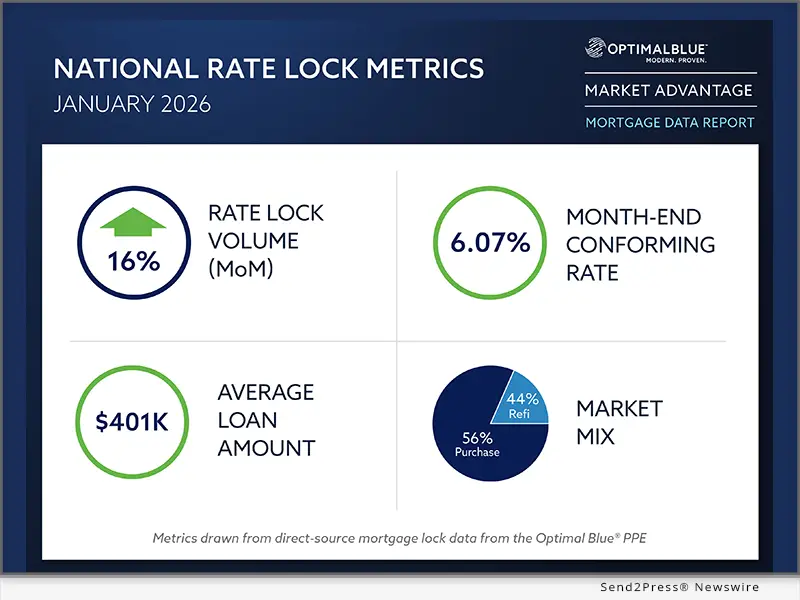
 

Vertyx to showcase intelligent loan servicing technology at MBA Servicing Solutions Conference & Expo

NEW YORK, N.Y., Feb. 10, 2026 (SEND2PRESS NEWSWIRE) — Vertyx, a provider of intelligent mortgage servicing technology built for enhanced portfolio performance, today announced that company Co-Founders Ayo Opeyemi and Moyin Opeyemi will participate in a live demo session during the Mortgage Bankers Association (MBA) Servicing Solutions Conference & Expo, which runs from Feb. 16–19.

Vertyx, Inc.
Image caption: Vertyx, a provider of intelligent mortgage servicing technology.

Hosted by Julian Hebron of The Basis Point, MBA’s Tech Showcase brings together innovative technology providers for rapid-fire demonstrations designed to help servicers navigate today’s challenging market conditions. Vertyx will showcase its Borrower Relationship Management capability on Tuesday, Feb. 17, 2026, from 12:30-1:30 p.m. on The HUB Stage in Longhorn Hall DE.

Borrower Relationship Management is a new addition to Vertyx’s end-to-end mortgage servicing platform that enables servicers and investors to identify and track retention and recapture opportunities earlier. Using those opportunities, servicing and retention teams can then run outreach campaigns promoting engagement across all borrower touchpoints, including within the borrower portal. Investors using Borrower Relationship Management are able to surface data insights to help provide a clear view of each mortgage’s return and risk profile, enabling well-informed investment decisions to boost returns across their portfolios.

“In today’s environment, servicers face increasing pressure to balance cost control with borrower experience and risk management,” said Co-Founder Ayo Opeyemi. “We’re thrilled to demonstrate how our modern servicing platform is designed to meet those demands by embedding intelligence directly into servicing workflows, reducing manual work, accelerating decision-making and uncovering retention and cross-sell opportunities within servicing portfolios.”

As origination volume fluctuates and new applications decrease, retained servicing and the opportunity it provides has become a critical component for building a sustainable revenue stream. Pre-pandemic borrowers with low rates are locked in with their current servicers and may be interested in second-lien products such as HELOCs or home equity loans offered by a timely servicer. On the other hand, post-pandemic borrowers with mortgage rates as high as 7% are beginning to seek out better options and lower rates. Borrower Relationship Management helps lenders identify borrowers who may be considering these expanded loan options and conduct timely, efficient outreach to bolster retention and cross-sell efforts.

“Servicing is no longer just about managing loans. It is a direct lever for profitability, borrower loyalty, and long-term portfolio performance,” said Co-Founder Moyin Opeyemi. “By surfacing the right opportunities and enabling targeted campaigns across borrower touchpoints, Vertyx helps servicers move from reactive servicing to proactive relationship management that drives measurable results.”

Vertyx executives will be available at booth 412 to provide additional information throughout the conference. Learn more about Vertyx here: https://vertyx.io/.

About Vertyx

Vertyx delivers intelligent servicing with proven results. Designed to transform loan servicing from a cost center into a profit engine, the Vertyx platform streamlines servicing operations through intelligent workflow automation while converting portfolio data into actionable retention and cross-sell opportunities. With intelligence embedded directly into the servicing lifecycle, Vertyx reduces manual work and delays common in legacy environments, lowering cost-to-serve and operational risk. Vertyx also helps teams move faster with confidence by embedding compliance into everyday workflows—supporting stronger outcomes for homeowners, servicers, and investors across the mortgage lifecycle. Visit https://vertyx.io to learn more.

NEWS SOURCE: Vertyx


This press release was issued on behalf of the news source (Vertyx), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vertyx-to-showcase-intelligent-loan-servicing-technology-at-mba-servicing-solutions-conference-expo/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P133000 NOREL-3B
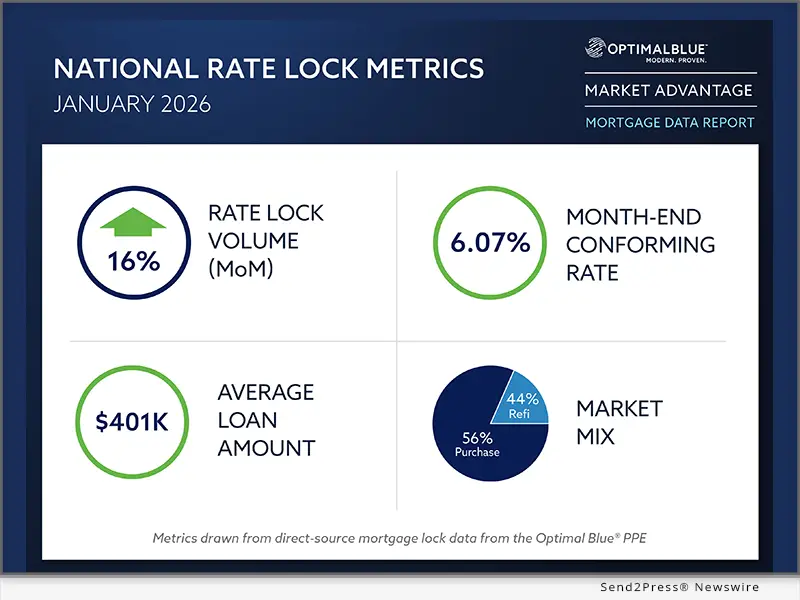
 

Optimal Blue report: Sub-6% rates spark refinance surge early in 2026

​​Refinances jump as execution strategies and investor demand shift

PLANO, Texas, Feb. 10, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its January 2026 Market Advantage mortgage data report, showing a strong start to the year as falling rates drove a sharp increase in refinance activity. Total rate-lock volume rose 16% month over month (MoM) and finished January 36% higher year over year (YoY), led by a surge in rate-and-term refinances, which climbed 50% from December and more than 400% compared with January 2025. Cash-out refinance activity also increased, rising 11% MoM and 38% YoY. Purchase volume grew a modest 3% from December but remained down 5% from a year earlier, reflecting the slower response of purchase demand to changing rate conditions early in the year.

Optimal Blue’s January 2026 Market Advantage mortgage data report
Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

Mortgage rates moved lower across most products in January. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, declined 7 basis points (bps) to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely unchanged at 5.99%. The average locked rate on the Optimal Blue PPE fell below 6% for the first time since August 2022.

“January’s data shows just how quickly refinance demand can respond when rates move lower,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “It’s been more than three years since the market last saw average rates with a ‘5 handle,’ and crossing back below that level appears to have released meaningful pent-up refinance demand. Purchase activity is responding more gradually, which is typical this early in the year, but the shift in borrower behavior is clear.”

On the secondary side, lenders adjusted execution strategies as pricing dynamics shifted and investor demand strengthened. Best-efforts-to-mandatory spreads increased for 30-year products, securitization activity increased and mortgage servicing rights (MSR) values rose despite declining benchmark rates, signaling a continued focus on balance sheet positioning and longer-term value.

“January’s secondary market data reflects lenders positioning early for a potentially more active origination environment,” said Vough. “Pricing trends were increasingly tied to eligibility rather than outright price give-ups, and agency MBS securitization reached its largest share since 2024. Meanwhile, rising MSR values and expanding investor participation point to a market focused on flexibility and long-term execution strategy as 2026 begins.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

VOLUME TRENDS AND MARKET COMPOSITION

  • Sharp pickup in refis: Refinance activity surged in January as falling rates quickly translated into borrower demand. Rate-and-term refinance locks increased 50% MoM and were more than four times higher YoY. Cash-out refinances also gained momentum, rising 11% MoM and 38% YoY.
  • Purchase activity lags: Purchase volume increased a modest 3% MoM but remained down 5% YoY. The slower response reflects the typical lag in purchase demand relative to rate movements, particularly early in the year.
  • Non-QM share pulls back: Non-qualified mortgage share declined to 8% in January, down 160 bps from December but 70 bps higher YoY.
  • VA gains momentum: VA lending captured a larger share of January activity as borrowers moved quickly to take advantage of lower rates, positioning VA portfolios for increased refinance-related payoffs as those loans move through the pipeline. VA loans accounted for 14% of locks, up 125 bps MoM and 212 bps YoY.
  • PUD share retreats: Planned unit developments (PUDs) accounted for 28% of locks in January, down 95 bps MoM and 651 bps YoY.

RATES AND PRICING

  • Rates edge down: Mortgage rates moved lower across most products in January. OBMMI for the 30-year conforming fixed rate declined 7 bps to 6.07%. Jumbo rates fell 16 bps to 6.25%, VA rates declined 7 bps to 5.64% and FHA rates were largely flat at 5.99%.
  • MSR values tick higher: MSR values for conforming 30-year loans increased 2 bps to 1.16%, representing a 4.65 multiple, diverging from declining benchmark rates.
  • Spreads widen on rate moves: Best-efforts-to-mandatory spreads increased for 30-year products in January, with the conforming 30-year spread widening 3 bps and the government 30-year spread increasing 8 bps. The conforming 15-year spread narrowed by 8 bps during the month.
  • Pricing discipline persists: The share of loans sold at the highest price tier remained flat at 79%, while second-tier executions increased 200 bps to 13%, reflecting continued use of eligibility-based delivery strategies with less price concession.

CHANNEL AND EXECUTION

  • Execution mix tilts to securitization: Lenders shifted hedged execution toward agency MBS in January, with securitization share increasing 300 bps MoM to 47%, the largest share since 2024.
  • Aggregator and cash executions ease: Loan sales to bulk aggregators declined 100 bps MoM, while cash window executions also decreased 100 bps during the month.
  • Investor participation continues to expand: The number of active investors increased to 14 in January, extending the expansion in investor participation that began late last year.

PRODUCT MIX AND BORROWER PROFILES

  • Credit quality improves: Average credit scores increased for both cash-out refis (up 2 points) and rate-and-term refis (up 5 points). Credit scores also rose across all major products, including conforming (up 1 point), FHA (up 1 point) and VA (up 4 points) loans.
  • Affordability metrics improve: Purchase debt-to-income (DTI) ratios declined across all loan types in January and fell 1 to 2 percentage points YoY. The share of first-time homebuyers also increased, rising to 45% of conforming loans and 70% of FHA loans.
  • Loan amounts edge up: The average loan amount increased from $394,502 in December to $400,667. January loan amounts ranged from $868,498 in greater San Francisco to $316,638 in San Antonio. Loan-to-value ratios ranged from 70.21% in greater Los Angeles to 88.44% in San Antonio, with a national average of 80.06%.

To view the full January 2026 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage.

Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Leslie Colley to be added to the media list.

ABOUT THE MARKET ADVANTAGE REPORT

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

ABOUT OPTIMAL BLUE

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA

Inage link for media: https://www.Send2Press.com/300dpi/26-0210-s2p-opblue-300dpi.webp

Image caption: Optimal Blue’s January 2026 Market Advantage mortgage data report.

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-sub-6-rates-spark-refinance-surge-early-in-2026/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132992 NOREL-3B
 

The Mortgage Collaborative and Mortgage Bankers Association announce partnership agreement

SAN DIEGO, Calif., Feb. 9, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s largest independent cooperative network for mortgage lenders and the Mortgage Bankers Association (MBA), the national association representing the real estate finance industry, announced today that they have entered into a strategic partnership to expand advocacy, education and engagement opportunities for their members.

The Mortgage Collaborative and Mortgage Bankers Association announce partnership agreement
Image caption: The Mortgage Collaborative and Mortgage Bankers Association announce partnership agreement.

The partnership is designed to strengthen connections between independent lenders and national industry advocacy by creating new pathways for lender perspectives to be elevated and shared. MBA will engage with TMC members through advocacy-focused discussions, programming, panels and webinars that reflect real-world lender experiences and priorities.

“TMC and MBA share a commitment to advancing the mortgage industry through education, advocacy and collaboration,” said Jodi Hall, president and CEO of The Mortgage Collaborative. “This partnership was formed after thoughtful consultation with our advisory council, lender advocacy committee leaders and lender members to ensure it aligns with the needs and values of our network.”

The collaboration is structured to preserve TMC’s lender-led model while expanding opportunities for member voices to be heard at the national level.

“The goal is to create stronger pathways for lender perspectives to be heard while giving members optional access to additional resources so they can engage at the level that fits them,” Hall said. “The partnership is designed to add value and amplify member voices.”

From MBA’s perspective, the partnership expands its connection to independent mortgage lenders and their on-the-ground experiences, helping to better inform broader industry conversations and initiatives.

“MBA is the leading voice for the real estate finance industry and we draw our strength and credibility from the active engagement of a diverse cross-section of members of all sizes and business models,” said Bob Broeksmit, CMB, president and CEO of MBA. “Increasing participation of TMC lender members in MBA advocacy and education activities will help build an even stronger industry.”

Through the partnership, MBA will offer exclusive benefits to the TMC lender network. Current TMC lender members interested in learning more are encouraged to contact their member benefits advocate. Lenders interested in exploring membership with The Mortgage Collaborative may contact referrals@mtgcoop.com for additional information.

About The Mortgage Collaborative

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders across the United States through networking, education, and advocacy. TMC fosters an environment of collaboration and innovation, ensuring its members succeed regardless of market conditions. For more information, visit mortgagecollaborative.com

About Mortgage Bankers Association

The Mortgage Bankers Association (MBA) is the national association representing the real estate finance industry, an industry that employs more than 275,000 people in virtually every community in the country. Headquartered in Washington, D.C., the association works to ensure the continued strength of the nation’s residential and commercial real estate markets, to expand homeownership, and to extend access to affordable housing to all Americans. MBA promotes fair and ethical lending practices and fosters professional excellence among real estate finance employees through a wide range of educational programs and a variety of publications. Its membership of more than 2,000 companies includes all elements of real estate finance: independent mortgage banks, mortgage brokers, commercial banks, thrifts, REITs, Wall Street conduits, life insurance companies, credit unions, and others in the mortgage lending field. For additional information, visit MBA’s website: mba.org

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/the-mortgage-collaborative-and-mortgage-bankers-association-announce-partnership-agreement/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132943 NOREL-3B


The Big Picture webcast to cover policy, compliance, lender strategy and digital transformation in February

CLEVELAND, Ohio, Feb. 3, 2026 (SEND2PRESS NEWSWIRE) — Top mortgage industry webcast The Big Picture, broadcast live every Thursday at 3 p.m. ET, announced its February lineup of guests, representing a broad swath of expertise from across the mortgage industry. Co-hosted by mortgage business consultant and executive coach Rich Swerbinsky and capital markets authority Rob Chrisman, author of the widely read Chrisman Commentary newsletter, the webcast delivers timely, thought-provoking conversations with mortgage professionals, innovators and thought leaders.

The Big Picture webcast to cover policy, compliance, lender strategy and digital transformation in February
Image caption: The Big Picture webcast to cover policy, compliance, lender strategy and digital transformation in February 2026.

The February lineup will explore key challenges facing mortgage lending, including legislative and regulatory shifts, affordability and how lenders can grow their business in the current climate. With expertise spanning government affairs, compliance, lender strategy, digital transformation, technology standards and borrower education, this slate reflects the depth of insight audiences expect from The Big Picture.

  • Thursday, February 5:
    Bob Broeksmit is president and CEO of the Mortgage Bankers Association. He will discuss broad trends across the industry, including recent legislation, the Fed and rates, the future of Fannie Mae and Freddie Mac, homebuyer affordability and rising credit reporting costs. A Certified Mortgage Banker and Yale graduate, Broeksmit has overseen multibillion-dollar origination, servicing and balance sheet operations while serving in senior roles at leading institutions including Chevy Chase Bank, Prudential Home Mortgage and The Money Store.
  • Thursday, February 12:
    Natalie Alexander, CPA, AMP, is president and chief financial officer of Willow Bend Mortgage, where she leads company strategy, operations and financial management. She will discuss how domestic migration is shaping the housing market in Dallas, where Willow Bend operates, and why increasing housing supply is vital to the mortgage industry. Alexander will also cover how lenders with a strong company culture are better positioned to capture business as volume rises.
  • Thursday, February 19:
    Jay Arneja is a mortgage technology veteran with more than 25 years of experience leading strategy, partnerships and innovation across the housing finance ecosystem. As expert relationship manager at nCino, she helps shape the company’s global mortgage partnerships and operational strategy, working closely with clients and fintech collaborators to advance digital transformation across lending. Arneja will discuss how lenders can approach digital transformation in phases to support a smoother, more logical transition into new technologies, including AI.
  • Thursday, February 26:
    Brian Vieaux, CMB, is president of MISMO, where he leads the mortgage industry’s central standards body and its mission to bring greater efficiency, transparency and interoperability to the real estate finance ecosystem. With more than 30 years of experience across origination, fintech and enterprise lending, Vieaux is nationally recognized for championing responsible innovation and advancing a more seamless, data-driven digital mortgage experience. He will discuss recent developments at MISMO, including a new dataset supporting the seamless exchange of title orders and its recent launch of new Communities of Practice.

Mortgage professionals and industry media can register for the webcast and view past episodes at https://www.chrismancommentary.com/the-big-picture.

About The Big Picture:

Co-hosted by renowned mortgage industry leader Rich Swerbinsky and capital markets expert Rob Chrisman, author of the widely acclaimed Chrisman Commentary industry newsletter, The Big Picture webcast offers a weekly deep dive into the forces shaping the mortgage world. Drawing on their extensive expertise and featuring compelling guests, the webcast delivers valuable perspectives and actionable insights for anyone seeking to better understand the dynamics of the mortgage industry. Visit https://www.chrismancommentary.com/the-big-picture to subscribe.

Tags: @nCino @MBAMortgage @MISMOStandards #MortgageIndustry #HousingPolicy #MortgageTech #DigitalMortgage

NEWS SOURCE: The Big Picture Mortgage Webcast


This press release was issued on behalf of the news source (The Big Picture Mortgage Webcast), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/the-big-picture-webcast-to-cover-policy-compliance-lender-strategy-and-digital-transformation-in-february/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132837 NOREL-3B
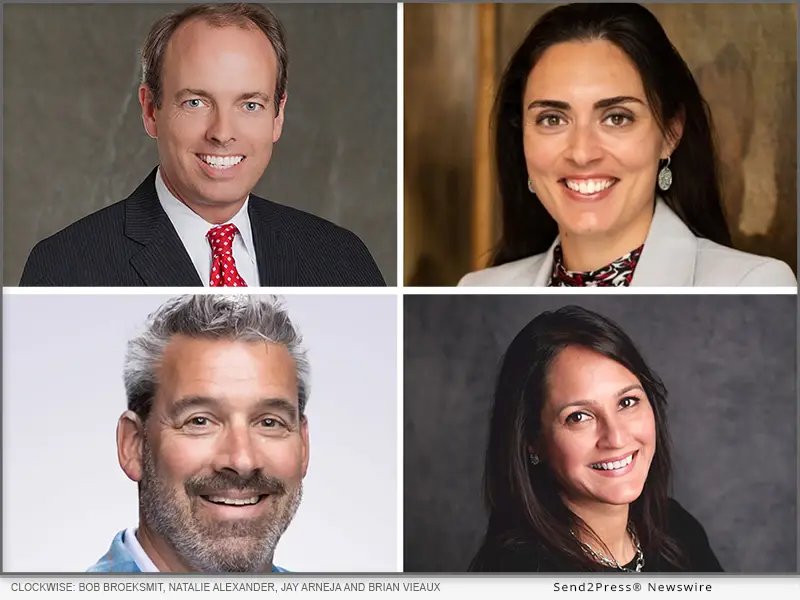
 

Elevate, Dark Matter Technologies’ servicing platform, gains momentum with new signings and technology enhancements

Client growth and ongoing enhancements strengthen Elevate's role across the servicing lifecycle

JACKSONVILLE, Fla., Feb. 2, 2026 (SEND2PRESS NEWSWIRE) — Dark Matter Technologies (Dark Matter®), an innovative leader in mortgage technology, today announced continued client momentum that includes a multi-year renewal with Arbor Bank and a new client signing with Covey Financial, as well as tighter integration of its Elevate℠ Loan Servicing Solution (Elevate) and the Empower® loan origination system (LOS).

Dark Matter Technologies
Image caption: Dark Matter Technologies.

Arbor Bank recently renewed its Elevate servicing platform agreement for an additional five years, citing a strong partnership and the platform’s ability to support evolving servicing needs. Covey Financial selected Elevate to help reduce manual processes, support a small servicing team and accommodate the unique loan products it services, including specialized community-focused programs.

Together, these client wins reflect how organizations are increasingly evaluating servicing technology based on automation, flexibility and vendor partnership, particularly as servicing teams are asked to do more with fewer resources.

Elevate is designed to help servicers operate more efficiently by automating high-effort, time-sensitive servicing activities, including scheduled investor reporting and transmissions, as well as interim servicing workflows. This automation provides servicing teams with clear visibility into what is being generated and delivered.

Elevate includes a native, web-based consumer portal that supports common self-service activities, helping to reduce call volume and manual follow-up. Borrowers can securely make payments and access key account information, while servicers benefit from fewer routine interactions and a more consistent borrower experience.

Designed to support a broad range of loan types, Elevate accommodates mortgage and home equity loans alongside many consumer and commercial products. This flexibility enables institutions to consolidate their servicing operations within a single platform, thereby reducing system complexity and enhancing operational consistency.

Although Elevate is LOS-agnostic, lenders that originate on the Empower LOS and service on Elevate benefit from tighter integration, which supports a more streamlined transition from closing to onboarding and servicing. With borrower, loan, and property data already captured during the origination process, servicers can reduce duplicate data handling and accelerate setup, improving time-to-first-payment and lowering operational risk. The integrated approach also positions lenders to better support retention strategies, using servicing-held loans and borrower context to inform timely outreach for refinancing, home equity or other recapture opportunities, in line with lender-defined rules and compliance requirements.

“We are tightly focused on supporting clients with a proven servicing platform that continues to evolve based on how it is used in real-world operations,” said Sean Dugan, CEO of Dark Matter Technologies. “By integrating Elevate with the Empower LOS, we make it easier for lenders to move loans from origination into servicing without added steps or duplication of effort. Backed by a team that understands servicing firsthand, this integration gives clients greater consistency across the servicing lifecycle.”

Formerly known as CMS Servicing, Elevate moved to Dark Matter Technologies in 2024, following Dark Matter’s acquisition by Constellation Software.

SEE IT ALL AT MBA SERVICING:

Dark Matter will showcase integration of the Elevate Loan Servicing Solution with the Empower LOS at MBA’s Servicing Solutions Conference & Expo, Feb. 16–19, 2026, in Grapevine, Texas. Visit the Dark Matter booth #616 to see demos, explore use cases for full and interim servicing, and learn how to unify origination and servicing on a single technology ecosystem.

ABOUT DARK MATTER TECHNOLOGIES:

Operating with the nimble nature of a startup and the disciplined maturity of one of the industry’s leading providers, Dark Matter Technologies delivers powerful technology with unparalleled automation and relentless innovation to leading mortgage lenders, servicers and companies nationwide. For more information, visit www.dmatter.com.

X: @dmattertech #fintech #mortgage #MBAServicing26

Logo link for media: https://dmatter.com/wp-content/uploads/dark-matter-tech-logo.svg

NEWS SOURCE: Dark Matter Technologies


This press release was issued on behalf of the news source (Dark Matter Technologies), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/elevate-dark-matter-technologies-servicing-platform-gains-momentum-with-new-signings-and-technology-enhancements/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132705 NOREL-3B


Mortgage Collaborative releases Pulse of the Network survey results and analysis

SAN DIEGO, Calif., Jan. 30, 2026 (SEND2PRESS NEWSWIRE) — The Mortgage Collaborative (TMC), the nation’s leading independent cooperative network for mortgage lenders, today released results from the latest Pulse of the Network survey, along with an analysis examining how mortgage lenders are prioritizing technology, operational efficiency, and growth strategies amid continued market pressure. The recent survey reflects insights from 38 member organizations, including independent mortgage banks and depository institutions across the United States.

TMC - The Mortgage Collaborative
Image caption: The Mortgage Collaborative.

“The Pulse of the Network gives us a clear, unfiltered view of what’s shaping lender decision-making right now,” said Jodi Hall, president and CEO of The Mortgage Collaborative. “Our members are balancing cost discipline with long-term competitiveness, and the data shows that technology, people, and partnerships are central to that equation.”

Findings from The Mortgage Collaborative’s November 2025 Pulse of the Network survey show technology implementation as lenders’ top priority for 2025–2026, driven by efforts to reduce origination costs, streamline operations, and improve the borrower experience.

KEY SURVEY HIGHLIGHTS INCLUDE:

  • Technology investment leads strategic priorities. Technology solutions ranked as lenders’ top priority, with many respondents focused on APIs, automation, and digital closing tools to reduce costs and improve efficiency across the loan lifecycle.
  • Automation and AI adoption continue to accelerate. More than half of respondents reported using APIs and automation for verifications and compliance, while lenders increasingly deploy AI-powered platforms to enhance borrower engagement and operational workflows.
  • Leadership development is a growing focus. More than three-quarters of respondents cited leadership development and employee engagement as key initiatives, reflecting increased emphasis on workforce optimization, succession planning, and performance measurement.
  • Revenue diversification remains a top growth strategy. Lenders are expanding into non-QM lending, down payment assistance programs, and home equity products to capture market share and strengthen purchase-focused business models.
  • Secondary market execution is under closer scrutiny. Nearly half of respondents are prioritizing post-close process improvements, investor diversification, and data-driven analytics to reduce execution risk and improve profitability.
  • Compliance remains complex, with fraud prevention a top concern. While compliance ranked lower in overall priority, more than half of respondents identified fraud prevention and cybersecurity as their most significant risk management challenges.

TMC uses Pulse of the Network findings to inform its strategic initiatives, conference programming, and partner solutions, ensuring members have access to relevant insights and collaborative resources aligned with current market conditions.

The full Pulse of the Network survey analysis is now available. Readers can access the published summary here.

ABOUT THE MORTGAGE COLLABORATIVE

The Mortgage Collaborative (TMC) is a membership-driven organization that empowers mortgage lenders nationwide through collaboration, education, and advocacy. TMC brings together independent mortgage banks and depository institutions to share insights, solve industry challenges, and strengthen long-term performance. For more information, visit www.mortgagecollaborative.com.

NEWS SOURCE: The Mortgage Collaborative


This press release was issued on behalf of the news source (The Mortgage Collaborative), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/mortgage-collaborative-releases-pulse-of-the-network-survey-results-and-analysis/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132628 NOREL-3B


Class Valuation names Chris Flynn as Chief Operating Officer

Former chief data officer to lead enterprise operations and execution

TROY, Mich., Jan. 29, 2026 (SEND2PRESS NEWSWIRE) — Class Valuation, a leading real estate appraisal management company (AMC), announced today that Chris Flynn has been appointed chief operating officer. Flynn joined Class Valuation in April 2025 as chief data officer and has since played a central role in advancing the company’s strategic, operational and product initiatives. As COO, Flynn will oversee enterprise operations and service delivery, product development and the firm’s data and automation implementation, helping guide Class Valuation through its next phase of growth and innovation.

Chris Flynn of Class Valuation
Image caption: Chris Flynn of Class Valuation.

During his tenure at Class Valuation, Flynn has led several high-impact initiatives, including advancing data strategies, overseeing the company’s operating platform migration and providing executive leadership to the company’s product organization. His work has helped improve valuation accuracy, speed and transparency while strengthening the company’s operational foundation.

“Chris brings a rare combination of strategic vision, technical depth and operational leadership, and we are excited to see him take on this expanded role,” said John Fraas, CEO of Class Valuation. “His ability to connect data strategy with real operational outcomes has helped us move faster, operate smarter and deliver more value to our clients.”

Flynn brings more than 20 years of leadership experience across real estate, fintech and technology, with deep expertise spanning operations, product development, analytics and enterprise strategy. Prior to joining Class Valuation, he served as head of product and strategy at First American Data & Analytics. He previously held senior leadership roles at First American Mortgage Solutions, CoreLogic (now Cotality) and Black Knight (now ICE).

“Class Valuation has a strong mission and a clear opportunity to lead the industry forward,” Flynn said. “I’m excited to step into this role and collaborate with our teams to drive our business forward through a focus on innovation and operational excellence, which will help our clients navigate a rapidly evolving market.”

ABOUT CLASS VALUATION:

Class Valuation is a leading nationwide appraisal management company (AMC) renowned for its commitment to fast turn times, exceptional quality and unparalleled client service. The company leverages a powerful combination of skilled professionals, innovative products, streamlined processes and advanced technology to empower lenders in fulfilling homeownership dreams. Consistently recognized by top mortgage lenders for its outstanding performance, Class Valuation has also earned accolades as a top workplace and received numerous industry awards. Founded in 2009, Class Valuation is headquartered in Troy, Michigan. For more information, please visit www.classvaluation.com.

Tags: @ClassValuation #appraisal #valuation #lending

NEWS SOURCE: Class Valuation


This press release was issued on behalf of the news source (Class Valuation), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/class-valuation-names-chris-flynn-as-chief-operating-officer/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132592 NOREL-3B


DocMagic executives elected to vice chair MISMO Communities of Practice

Leadership roles reinforce DocMagic's influence on standards that shape lender efficiency and digital execution

TORRANCE, Calif., Jan. 27, 2026 (SEND2PRESS NEWSWIRE) — DocMagic, Inc., today announced that two of its executives have been elected to help lead Community of Practice (CoP) workgroups within the Mortgage Industry Standards Maintenance Organization (MISMO) for the 2026–2027 term.

DocMagic executives elected to vice chair MISMO Communities of Practice
Image caption: DocMagic executives elected to vice chair MISMO Communities of Practice.

Chief eServices Executive Brian D. Pannell will serve as vice chair of MISMO’s Digital Interoperability CoP, and Director of Integration and Technical Services David Garrett will serve as vice chair of the eMortgage CoP. Garrett will also continue serving as vice chair of MISMO’s Origination CoP, a role to which he was elected last year, for the remainder of his two-year term.Leadership within MISMO plays a direct role in how digital mortgage standards are defined, interpreted and put into practice across the industry, making it critical that those standards are shaped by organizations with real-world lending experience. With nearly 40 years in business and more than 700 lender customers, DocMagic brings deep operational perspective to its leadership roles across multiple CoP, helping ensure standards reflect how data actually behaves across complex lending workflows. This alignment supports stronger interoperability, fewer execution gaps and more predictable movement of documents and data throughout the loan lifecycle.

“Digital interoperability is foundational to a functioning secondary market and scalable digital lending,” said Pannell. “The work happening within MISMO’s Digital Interoperability Community of Practice directly affects how documents, data and collateral move between systems. My focus is on helping ensure those standards translate into practical, reliable execution for lenders operating at scale.”

Added Garrett, “MISMO’s Communities of Practice are where many of the industry’s most consequential decisions around eMortgage adoption and origination standards take shape. Serving in leadership roles across the eMortgage and Origination communities allows us to bring lender realities into the standards process and help drive specifications that support accuracy, compliance and consistent execution across the loan lifecycle.”

MISMO is the mortgage industry’s standards organization, responsible for developing and maintaining the data standards that enable lenders, investors, servicers, government agencies and technology providers to communicate efficiently and securely. Adoption of MISMO standards has been shown to lower per-loan costs, reduce errors, improve margins and accelerate the mortgage process.

The Digital Interoperability CoP focuses on identifying and resolving inconsistencies in electronic documents and eVaults while establishing best practices and long-term solutions to ensure seamless interoperability across platforms. The eMortgage CoP, one of MISMO’s largest communities with more than 200 members, develops specifications, document profiles and implementation guidelines for electronic mortgage documents across the loan lifecycle—from application and origination through closing, investor delivery and servicing. The Origination CoP designs and maintains data standards supporting mortgage application, underwriting and closing processes.

About DocMagic:

DocMagic provides end-to-end document generation, automated compliance, eSignature and eMortgage solutions for the mortgage industry. For nearly 40 years, our patented and award-winning innovations have evolved with the industry—from pioneering digital workflows to integrated AI-driven capabilities. We partner closely with lenders, settlement service providers and investors to implement successful eStrategies that drive faster closings, reduced costs and exceptional borrower experiences. For more information, visit www.docmagic.com.

Tags: @DocMagicTech

NEWS SOURCE: DocMagic, Inc.


This press release was issued on behalf of the news source (DocMagic, Inc.), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/docmagic-executives-elected-to-vice-chair-mismo-communities-of-practice/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132519 NOREL-3B


Vertyx Expands Mortgage Servicing Platform with Portfolio Retention and Engagement Measurement Tools for Servicers and Investors

NEW YORK, N.Y., Jan. 27, 2026 (SEND2PRESS NEWSWIRE) — Vertyx, a provider of intelligent mortgage servicing technology built for enhanced portfolio performance, today announced the release of Borrower Relationship Management, a new capability within its end-to-end mortgage servicing platform designed to help servicers and investors identify retention and recapture opportunities earlier, deliver timely outreach through borrower channels and measure engagement.

Vertyx, Inc.
Image caption: Vertyx, Inc. logo.

Borrower Relationship Management is designed around three stakeholders in the mortgage lifecycle — the borrower, the servicer and the investor — with the goal of helping institutions protect portfolio value while delivering a higher-quality servicing experience. This feature surfaces mortgages within your portfolio that may need attention based on a proprietary blend of leading indicators.

Servicing and retention teams can use those signals to create promotional offers, define eligibility criteria, and run outreach campaigns that place targeted messages across all borrower touchpoints, such as online portals and borrower-facing statements. Offer-level tracking, including digital views and clicks, helps teams evaluate effectiveness and refine outreach.

Homeowners can then see those offers through the borrower portal, where offers are presented based on the borrower’s mortgage, including the ability to surface distinct offers for each loan. The same activity drives reporting that helps servicers and investors understand coverage and engagement to adjust outreach accordingly. That feedback loop supports timely, relevant outreach that fits naturally into the borrower experience.

“Servicing teams need tools that help them stay ahead of borrower needs while keeping the experience helpful and human,” said Ayo Opeyemi, co-founder of Vertyx. “Borrower Relationship Management builds on our platform’s foundation to help servicers engage homeowners in the right moments through the channels they already use.”

For investors, Borrower Relationship Management leverages AI to generate analytics that guide the understanding of each mortgage’s return and risk profile. These insights help investors support more informed decisions when loan performance changes, including delinquency scenarios, and provide the visibility needed to boost returns across their portfolios. Investors can also drill down from portfolio-level insights into a specific loan to review underlying servicing details such as payment history and cash received. The platform also considers relationship value at the borrower level, including cases where a homeowner has multiple loans, to help institutions prioritize high-value relationships and identify responsible opportunities to deepen engagement.

“Servicing data has traditionally been difficult for investors to access in a timely, usable way,” said Moyin Opeyemi, co-founder of Vertyx. “By bringing loan-level value signals and engagement insights together with portfolio visibility, investors and servicers can prioritize attention and respond earlier when performance or payoff risk starts to shift.”

Borrower Relationship Management is delivered as part of Vertyx’s end-to-end mortgage servicing platform, composed of Edge, the core servicing system where servicing teams work; myAxis, the borrower portal; and Lynk, the investor portal. The platform was built to modernize servicing operations with a cloud-based, real-time architecture and to support stronger visibility for all stakeholders across the life of the loan. Vertyx is designed to support borrower communications and self-service through secure interactions and configurable borrower experiences.

To learn how Vertyx is helping organizations optimize their portfolios or to schedule an introductory conversation, visit https://vertyx.io or contact connect@vertyx.io.

About Vertyx

Vertyx delivers intelligent servicing with proven results. Designed to transform loan servicing from a cost center into a profit engine, the Vertyx platform streamlines servicing operations through intelligent workflow automation while converting portfolio data into actionable retention and cross-sell opportunities. With intelligence embedded directly into the servicing lifecycle, Vertyx reduces manual work and delays common in legacy environments, lowering cost-to-serve and operational risk. Vertyx also helps teams move faster with confidence by embedding compliance into everyday workflows—supporting stronger outcomes for homeowners, servicers, and investors across the mortgage lifecycle. Visit https://vertyx.io to learn more.

NEWS SOURCE: Vertyx


This press release was issued on behalf of the news source (Vertyx), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/vertyx-expands-mortgage-servicing-platform-with-portfolio-retention-and-engagement-measurement-tools-for-servicers-and-investors/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132533 NOREL-3B


Down Payment Resource finds 2,619 homebuyer assistance programs nationwide in Q4 of 2025

Program count for the year's final quarter is up 6% from last year, holding near record levels

ATLANTA, Ga., Jan. 26, 2026 (SEND2PRESS NEWSWIRE) — Down Payment Resource (DPR), the housing industry authority on homeownership program data and solutions, today released its Q4 2025 Homeownership Program Index (HPI) report, identifying 2,619 programs. While the total count is five programs fewer than the prior quarter, it marked a 6% increase from a year earlier, rising from 2,466 programs in Q4 2024. The year-over-year (YoY) growth reflects continued expansion and refinement of program options amid persistent housing affordability challenges across much of the country.

Down Payment Resource finds 2,619 homebuyer assistance programs nationwide in Q4
Image caption: Down Payment Resource finds 2,619 homebuyer assistance programs nationwide in Q4.

Down payment assistance (DPA) continues to play a critical role in helping lenders expand access to homeownership. On average, these programs provide approximately $18,000 in benefits, reducing a homebuyer’s loan-to-value ratio by 8.8% and strengthening borrower qualification and overall loan profiles. Beyond down payments, many programs also help cover closing costs, prepaid expenses, mortgage rate buydowns and reductions in mortgage insurance costs. In some cases, eligible buyers can layer multiple programs to further improve affordability.

“Affordability will remain the defining challenge for homebuyers in 2026, and down payment programs are one of the most practical tools lenders have to address it,” said DPR Founder and CEO Rob Chrane. “When DPA lowers loan-to-value ratios and helps cover upfront costs, it doesn’t just improve borrower eligibility; it improves loan quality. As prices remain elevated and rates fluctuate, lenders that proactively integrate DPA into their origination strategies are better positioned to turn qualified demand into sustainable homeownership.”

KEY Q4 2025 HPI REPORT FINDINGS:

An examination of the 2,619 homeownership programs on January 1, 2026, resulted in the following key findings:

  • Every U.S. county has at least one DPA program, and more than 2,000 have 10 or more. By state, California has the most with 353 programs from 223 providers. Florida has 196 programs from 128 providers. Texas has 128 programs from 63 providers.
  • Benefits and home income caps are rising. 1,599 programs (62%) have an average income limit exceeding $100k across the program’s footprint. Additionally, 270 programs (10%) do not have income restrictions, thereby increasing the number of buyers who may qualify for assistance. This “income-free” requirement represents a 15% YoY increase, giving lenders a wider box to qualify borrowers.
  • Support for first-time buyers and first-gen buyers. 1,639 programs (63%) are open to first-time buyers, an 8% YoY rise. First-generation homebuyers are supported by 33 programs, a 32% YoY increase. First-generation homebuyers are defined as buyers and their parents who have never owned a home. 980 programs (37%) are available to repeat buyers, a 3% YoY increase.
  • Servicemembers and Veterans are exempted from 246 programs (9%). This exemption allows them to qualify even if they have previously purchased a residence, representing a 12% YoY increase.
  • Buyers of newly constructed homes are supported by 2,113 (81%) of the programs. These programs typically help cover a portion of the buyer’s down payment and/or closing costs, similar to assistance for resale properties. This is a slight increase from Q3 and is a new data point being tracked by DPR with no historical YoY data.
  • Buyers of multi-family housing (1-4 units) are eligible for 923 programs, a 15% YoY increase. Of these, a growing number of programs support purchasing three-unit homes (607) and four-unit homes (580), both of which saw a 13% YoY increase. Investing in multifamily properties can generate cash flow and offer tax advantages to buyers.
  • Buyers of manufactured housing are supported by 1,014 programs, a slight slide from the previous quarter but 14% higher YoY. New manufactured homes cost roughly $85 per square foot, compared with about $166 per square foot for site-built homes, according to the Manufactured Housing Institute, highlighting the relative affordability of manufactured homes.
  • Program types vary widely. The majority of programs (1,461, or 56%) are second-mortgage programs, up 4% YoY, while 242 programs are first-mortgage programs, up 1% YoY. 37 were “other assistance” programs, meaning they consist of components that don’t neatly fit into the other categories, such as an interest rate reduction benefit. Other assistance programs are 85% higher YoY. 273 are combined assistance programs, 18% higher YoY. 207 programs are grants, up 17% YoY. 139 programs are below-market-rate (BMR) or resale-restricted, up 49% YoY, giving low- to moderate-income households more opportunities to achieve homeownership.
  • The majority of DPA loans are structured to be forgivable. 1,035 DPA programs (53%) offer partial or full forgiveness over time — a 5% YoY increase. These programs may require that homebuyers meet specific requirements, such as living in the home as their primary residence for a certain number of years.
  • DPA is offered by a wide variety of providers. 1,027 programs (39%) were offered through municipalities or local program providers, a 6% YoY increase. 562 programs (21%) are sponsored by nonprofits, a 7% YoY increase. State housing authorities (HFAs) accounted for 466 (18%) of programs, 1% higher YoY.
  • Some programs offer special incentives based on the buyer’s occupation or other characteristics. Of the 201 special incentive programs, 71 (35%) support educators, up 4% YoY. 56 programs (28%) assist Native American homebuyers, 19% higher YoY. 54 programs (27%) are available to military Veterans (up 10% YoY).

A more detailed analysis of the Q4 2025 HPI findings, including infographics and examples of the programs described in this release, can be found on DPR’s website at: https://downpaymentresource.com/professional-resource/down-payment-assistance-holds-near-record-levels-in-q4-2025-as-program-flexibility-expands/

For a complete list of homebuyer assistance programs by state, visit: https://downpaymentresource.com/wp-content/uploads/2026/01/HPI-state-by-state-data.Q42025.pdf

Members of the media are encouraged to contact DPR for data specific to their reporting needs.

METHODOLOGY:

Published quarterly, DPR’s HPI surveys the funding status, eligibility rules and benefits of U.S. homebuyer assistance programs administered by state and local housing finance agencies, municipalities, nonprofits and other housing organizations. DPR communicates with over 1,300 program providers throughout the year to track and update the country’s wide range of homeownership programs, including down payment and closing cost programs, Mortgage Credit Certificates (MCCs) and affordable first mortgages, in the DOWN PAYMENT RESOURCE® database.

ABOUT DOWN PAYMENT RESOURCE:

With a database that tracks over 2,600 programs and toolsets for mortgage lenders, multiple listing services (MLSs) and API users, Down Payment Resource (DPR) is the housing industry’s authority on homeownership program data and solutions, helping housing professionals connect homebuyers with the assistance they need. DPR frequently lends its expertise to nonprofits, housing finance agencies, policymakers, government-sponsored enterprises and trade organizations seeking to improve housing affordability. Its technology is used by seven of the top 25 mortgage lenders, two of the largest real estate listing websites and 600,000 real estate agents. For more information, visit www.downpaymentresource.com.

X: @DwnPmtResource #downpaymentassistance #downpayment

NEWS SOURCE: Down Payment Resource


This press release was issued on behalf of the news source (Down Payment Resource), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/down-payment-resource-finds-2619-homebuyer-assistance-programs-nationwide-in-q4-of-2025/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132476 NOREL-3B


Informative Research delivers significant platform innovations and enhanced integrations in 2025

GARDEN GROVE, Calif., Jan. 26, 2026 (SEND2PRESS NEWSWIRE) — Informative Research (IR), a leading technology provider of data-driven credit and verification solutions for the lending industry, today announced that its work in 2025 has introduced significant platform enhancements and expanded its integration ecosystem across credit and verification services. The company introduced new credit and verification capabilities, added multiple data and payroll partners, and enhanced automation through its unified platform, enabling lenders to streamline workflows, reduce manual processes and access borrower data earlier and more consistently across the loan lifecycle.

Informative Research
Image caption: Informative Research delivers significant platform innovations and enhanced integrations in 2025.

“2025 was a year of steady platform advancement and partner expansion for Informative Research. We focused on investments that strengthened how credit and verification data integrates with lender workflows, enhancing operational efficiency, compliance confidence and measurable client outcomes,” said Informative Research President Matt Orlando. “By expanding our verification network and enhancing platform automation, we helped lenders better manage the rising cost of consumer data, and along the way, measured the impact of these initiatives side-by-side with the customer.”

In 2025, IR delivered five new integrations across its credit and verification platform, including Halcyon for automated income validation and IRS tax transcript access, Thomas & Company for wage and employment verification, and The Work Number® Report Indicator from Equifax to surface employment status earlier in the qualification process. The company also expanded its payroll provider network with Freddie Mac’s Loan Product Advisor (LPA) asset and income modeler (AIM), increasing lenders’ access to rep and warrant relief. These enhancements strengthened the company’s credit and verification platforms, increasing lender access to consumer-permissioned income and employment data.

IR also integrated with Vesta, enabling lenders to access IR’s suite of consumer data and verifications directly with the Vesta loan origination system (LOS) to enhance operational efficiency and reduce manual processes. IR continued to enhance its platform experience through expanded automation and operational visibility. Updates to IR’s client-facing workspace, Action Center, gave lenders greater control over orders, audit trails, task management and self-service actions, including the ability to update borrower information, trigger refreshes and review verification results. On the backend, enhancements to the company’s data and analytics layer improved reporting, reliability and transparency across credit and verification workflows.

Underscoring its accomplishments, IR was recognized on the 2025 HousingWire Mortgage Tech100 list. Along with company achievements, IR employees received extensive accolades in 2025:

  • Jooyoung Jung and Praneeth Reddy Saripalli were honored as HousingWire Rising Stars.
  • Craig Leabig was named a HousingWire Marketing Leader.
  • Shannon Santos received Mortgage Professional America’s Elite Woman Award.
  • Mike Hall and Elizabeth Campos were recognized as HousingWire Insiders.
  • Matthew Orlando was named a HousingWire Vanguard.
  • Steve Schulz was honored as a HousingWire Tech Trendsetter.
  • Sriranjini Prabhakara was included on the National Mortgage Professional 40 Under 40 list.

About Informative Research

Informative Research, a Stewart company, is a premier technology provider delivering data-driven credit and verification solutions to the lending community. The solutions provider currently serves mortgage companies, banks and lenders throughout the United States. The company is recognized for streamlining the loan process with its straightforward service model, progressive solutions and cutting-edge technology. To learn more, visit https://www.informativeresearch.com.

NEWS SOURCE: Informative Research


This press release was issued on behalf of the news source (Informative Research), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/informative-research-delivers-significant-platform-innovations-and-enhanced-integrations-in-2025/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132488 NOREL-3B


Class Valuation Appoints Tanya Wright as EVP of TPO and Distributed Retail

Industry veteran brings deep operational expertise and lender-side perspective to support broker and distributed retail clients

TROY, Mich., Jan. 21, 2026 (SEND2PRESS NEWSWIRE) — Class Valuation, a leading real estate appraisal management company (AMC), announced today that Tanya Wright has joined the company as Executive Vice President of Third-Party Origination (TPO) and Distributed Retail. Wright will serve on Class Valuation’s Operations Leadership Team and oversee strategy, operations and client success for the company’s broker and distributed retail channels.

Class Valuation Appoints Tanya Wright as EVP of TPO and Distributed Retail
Image caption: Class Valuation Appoints Tanya Wright as EVP of TPO and Distributed Retail.

Wright brings more than a decade of leadership experience in mortgage operations and financial technology, with a strong background in scaling teams, optimizing complex workflows and supporting growth across TPO, distributed retail and non-delegated correspondent channels. Most recently, she served as Vice President of Non-QM Operations at Kind Lending, where she led operational teams and supported business expansion initiatives. Her prior experience also includes senior leadership roles at Emporium TPO and loanDepot, where she supported wholesale and distributed retail operations at scale.

In her new role, Wright will focus on scalable processes, service excellence and meeting the unique needs of lenders operating across diverse regional and market environments. Her responsibilities will include supporting brokers and distributed retail clients through operational consistency, strong communication and continued investment in technology-enabled solutions.

“Tanya’s background uniquely positions her to lead this critical part of our business,” said John Fraas, CEO of Class Valuation. “She brings a lender-side perspective that gives her a deep understanding of what brokers and distributed retail lenders need to succeed. Her ability to build repeatable, scalable processes while maintaining a high standard of service aligns well with our mission and growth strategy.”

Wright said her decision to join Class Valuation was influenced by both her prior experience working with the company and its leadership position in appraisal technology. “Class Valuation is not only one of the largest AMCs in the country, but also a technology and industry leader. In a market that’s constantly shifting, being on the cutting edge isn’t optional,” Wright said. “My career has focused on rapid growth, building to scale and creating repeatable processes, and Class Valuation is doing exactly that.”

Wright holds a bachelor’s degree in child learning and development from The University of Texas at Dallas and a master’s degree in child development from Texas Woman’s University. She is actively involved in volunteer work supporting local schools in her community.

About Class Valuation

Class Valuation is a leading nationwide appraisal management company (AMC) renowned for its commitment to fast turn times, exceptional quality and unparalleled client service. The company leverages a powerful combination of skilled professionals, innovative products, streamlined processes and advanced technology to empower lenders in fulfilling homeownership dreams. Consistently recognized by top mortgage lenders for its outstanding performance, Class Valuation has also earned accolades as a top workplace and received numerous industry awards. Founded in 2009, Class Valuation is headquartered in Troy, Michigan. For more information please visit https://classvaluation.com.

Tags: @ClassValuation #appraisal #valuation #lending

NEWS SOURCE: Class Valuation


This press release was issued on behalf of the news source (Class Valuation), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/class-valuation-appoints-tanya-wright-as-evp-of-tpo-and-distributed-retail/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132437 NOREL-3B


Moody’s Investors Service affirms Dovenmuehle’s overall rating as ‘above average’ residential mortgage loan servicer

LAKE ZURICH, Ill., Jan. 20, 2026 (SEND2PRESS NEWSWIRE) — Dovenmuehle Mortgage, Inc. (Dovenmuehle), a leading residential mortgage subservicer, announced today that Moody’s Investors Service (“Moody’s”) has affirmed its servicer quality (SQ) assessment as a servicer of prime residential mortgage loans at SQ2-. Moody’s assessment highlights Dovenmuehle’s strong performance and disciplined execution across key areas of mortgage servicing.

Dovenmuehle Mortgage
Image caption: Dovenmuehle Mortgage, Inc.

“Moody’s assessment reinforces the strength of our servicing capabilities and our focus on continuous improvement,” said Dovenmuehle Senior Vice President Matthew Budy. “As we invest in innovation and operational efficiency, we remain committed to delivering dependable, high-quality service for our clients and borrowers.”

In its assessment, Moody’s highlighted Dovenmuehle’s focus on technology innovation and information security, noting the company’s recently implemented mobile notary service and digital enhancements. The key areas considered in the review include:

  • Collection: Dovenmuehle’s collection abilities were above average, using notable multi-channel outreach to engage customers.
  • Loss Mitigation: The company’s loss mitigation abilities were rated above average, with improved processes and enhanced efficiency.
  • Enforcement Abilities: Dovenmuehle’s enforcement abilities were above average, noting compliance enhancements in bankruptcy processes.
  • Loan Administration: The report highlighted the company’s effective mobile functionality and enhanced quality control on its loan boarding process.
  • Servicing Stability: Dovenmuehle’s experienced senior management team prioritized strategic technology investments with a focus on information security to enhance long-term stability.

In addition, Dovenmuehle has consistently demonstrated strong loss mitigation performance, supported by solid cure and recidivism rates.

Moody’s assessment reflects Dovenmuehle’s dedication to continuous improvement and adherence to best practices in mortgage servicing. The company remains committed to delivering exceptional service to its clients and borrowers, upholding the highest standards of professionalism and integrity.

About Dovenmuehle

Founded in 1844, Dovenmuehle (Lake Zurich, Ill.) is a mortgage subservicer for commercial banks, credit unions, independent mortgage lenders, MSR investors and state housing finance agencies nationwide. The company subservices portfolio loans, as well as loans sold to Fannie Mae, Freddie Mac, Ginnie Mae and the Federal Home Loan Bank with servicing retained. Using a combination of best-in-class and proprietary technology, Dovenmuehle helps lenders reduce servicing costs and deliver consistently high levels of service to homeowners while maintaining compliance with investor and regulatory requirements. Learn more at https://dovenmuehle.com/.

NEWS SOURCE: Dovenmuehle


This press release was issued on behalf of the news source (Dovenmuehle), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/moodys-investors-service-affirms-dovenmuehles-overall-rating-as-above-average-residential-mortgage-loan-servicer/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132415 NOREL-3B


FirstClose Caps Transformational 2025 With Faster Closings, Platform Expansion and Strong Market Momentum

AUSTIN, Texas, Jan. 16, 2026 (SEND2PRESS NEWSWIRE) — FirstClose™, a leading fintech provider of data and workflow solutions for mortgage and home equity lenders nationwide, today announced 2025 results showing faster closings and measurable efficiency gains as lenders used its technology to meet rising home equity demand in a high-interest-rate environment. The company reduced closing timelines, expanded key integrations and strengthened its operating foundation to support scalable growth in 2026.

FirstClose Caps Transformational 2025 With Faster Closings, Platform Expansion and Strong Market Momentum
Image caption: FirstClose Caps Transformational 2025.

By year’s end, lenders using FirstClose signed disclosures in as little as five hours, completed borrower tasks within two days and funded loans in as few as four days. The platform helped reduce closing timelines by up to 74%, with 38% of applications instantly approved via automated decisioning workflows.

“We were deliberate in 2025 about building a durable foundation rather than chasing short-term growth,” said Tedd Smith, co-founder and chief executive officer of FirstClose. “That work is paying off in faster outcomes for lenders today and positions us well for the opportunities ahead.”

Those performance gains came as home equity lending continued to accelerate nationally. FirstClose has supported over 225 financial institutions and contributed to $129 billion in funded loans since 2015, while lenders using its digital prequalification tools have reported 30-40% increases in application volume.

A major milestone in 2025 was the launch of a certified integration with Optimal Blue, which connects FirstClose’s point-of-sale platform directly to Optimal Blue’s product, pricing, and eligibility engine. The integration brought lender-specific pricing into the borrower application flow, helping to compress home equity closing timelines from roughly 45 days to 10 days or fewer.

FirstClose also secured additional equity funding in October, led by existing investor Lateral Investment Management. The investment reinforced confidence in the company’s strategy and supported continued product development, integrations and operational initiatives across home equity and mortgage lending.

Internally, 2025 was a year of restructuring to prepare the organization for its next phase of growth. FirstClose strengthened leadership in sales, professional services, and client success to improve coordination among teams and reduce implementation times for lenders. The changes focused on operational durability rather than rapid expansion.

The year also coincided with FirstClose’s 25th anniversary, underscoring its long-standing role in modernizing mortgage and home equity lending. From its early days as a property data and settlement services provider to its current end-to-end lending platform, the company has continued to evolve alongside lender needs and market shifts.

With faster funding, deeper integrations and a strengthened operating model in place, FirstClose enters 2026 positioned to help lenders capture growing home equity demand while delivering a more transparent and efficient borrower experience.

About FirstClose

Headquartered in Austin, Texas, FirstClose, Inc. provides fintech solutions to HELOC and mortgage lenders nationwide. The company’s mission is to increase profitability and reduce costs for mortgage lenders. FirstClose makes this possible through offering systems and relationships that enable lenders to assist their borrowers more effectively, reduce closing costs, and ultimately shorten closing times. For more information, visit firstclose.com.

NEWS SOURCE: FirstClose


This press release was issued on behalf of the news source (FirstClose), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/firstclose-caps-transformational-2025-with-faster-closings-platform-expansion-and-strong-market-momentum/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132356 NOREL-3B


ACES Quality Management Grows Audit Volume and Market Share, Advances AI Innovation and Industry Leadership in 2025

DENVER, Colo., Jan. 13, 2026 (SEND2PRESS NEWSWIRE) — ACES Quality Management® (ACES), the leading provider of enterprise quality management and control software for the financial services industry, continued to support its customers through a challenging mortgage market in 2025 by sustaining audit scale, advancing AI-driven quality control innovation and delivering trusted regulatory and defect trend insight.

ACES Quality Management
Image caption: ACES Quality Management.

Even as origination volumes remained subdued, ACES clients processed millions of loans during the year, reinforcing the platform’s place in day-to-day quality control, compliance and risk management operations.

In 2025, ACES:

  • Processed approximately 8.6 million loans through the ACES platform, reflecting sustained audit scale during a low-volume mortgage market.
  • Grew client base by adding many financial services industry leaders, including multiple top 20 credit unions, top 20 international banks, and leading service providers.
  • Reviewed 245 regulatory publications, a 38% increase year over year.
  • Published 379 Compliance NewsHub articles and 81 regulatory calendar items to help financial professionals track evolving requirements.
  • Made almost 20,900 changes to the ACES Managed Questionnaires, maintaining alignment with GSE and Agency eligibility requirements, along with federal and state regulatory changes.
  • Continued to deliver its free Mortgage QC Industry Trends Reports and QC Now webinars, providing lenders and servicers with data-driven insight into defect trends, underwriting performance and emerging quality risks.
  • Launched ACES Intelligence™, the mortgage industry’s first AI-powered quality control engine, enabling natural-language loan selection, automated exception writing, executive audit summaries and real-time PII detection to significantly reduce manual review time.
  • ACES advanced its enterprise data strategy with the general availability of ACES DATABRIDGE, enabling customers to extract, manage and report on their ACES data using their own tools and environments.

“Every market cycle tests whether systems, processes and partnerships can hold up under pressure,” said Trevor Gauthier, CEO of ACES Quality Management. “Our focus has always been on building technology and expertise that our customers can trust. When scrutiny increases and margins tighten, quality becomes even more critical. That’s where disciplined execution, transparency and proven solutions make the difference.”

ACES hosted its annual ACES ENGAGE conference in 2025, bringing together quality control, risk and compliance professionals for peer learning and collaboration. Separately, the company continued to advance its “I Stand for Quality” movement, which promotes a shared commitment to elevating lending standards across the mortgage industry.

Additional 2025 achievements for ACES include:

About ACES Quality Management

ACES Quality Management is the leading provider of enterprise quality management and control software for the financial services industry. The nation’s most prominent lenders, servicers and financial institutions rely on ACES Quality Management & Control® Software to improve audit throughput and quality while controlling costs, including:

  • Over 70% of the top 20 independent mortgage lenders;
  • 7 of the top 10 loan servicers;
  • 11 of the top 30 banks; and
  • 3 of the top 5 credit unions in the United States.

Unlike other quality control platforms, ACES Flexible Audit Technology® enables independent mortgage lenders and financial institutions to easily manage and customize the system to their specific needs without relying on IT or outside resources. With ACES’ AI-powered capabilities, audit teams can translate complexity into clear insights and accelerate performance.

Using a customer-centric approach, ACES clients get responsive support and access to our experts to maximize their investment. For more information, visit www.acesquality.com or call 1-800-858-1598.

NEWS SOURCE: ACES Quality Management


This press release was issued on behalf of the news source (ACES Quality Management), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/aces-quality-management-grows-audit-volume-and-market-share-advances-ai-innovation-and-industry-leadership-in-2025/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132220 NOREL-3B


Optimal Blue report: December lock volume closes 2025 on a firm footing

Refinance momentum drives year-end activity despite holiday headwinds

PLANO, Texas, Jan. 13, 2026 (SEND2PRESS NEWSWIRE) — Optimal Blue today released its December 2025 Market Advantage mortgage data report, showing that mortgage rate-lock activity ended the year on a firm footing, bucking typical holiday-driven seasonality. Total lock volume rose 2% month over month (MoM) from November and finished 30% higher year over year (YoY), driven primarily by rate-and-term refinances, which climbed 13% from November and more than 170% compared with December 2024. Cash-out refinance volume rose a modest 1% MoM but remained up a strong 35% YoY. Purchase activity dipped just 1% from November despite holiday headwinds to end December up 7% YoY.

Optimal Blue's December 2025 Market Advantage mortgage data report
Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report.

Mortgage rates were largely stable in December. The Optimal Blue Mortgage Market Indices (OBMMI) 30-year conforming fixed rate, the benchmark for CME Group’s Mortgage Rate futures, finished the month flat at 6.14%. Meanwhile, the 10-year Treasury yield rose 14 basis points (bps) to 4.14%, reversing November’s spread widening and pushing the 10-year-to-OBMMI spread to 200 bps at year-end.

“Finishing the year with higher lock volume in December is a clear signal that borrower demand has adjusted to today’s rate environment,” said Mike Vough, senior vice president of corporate strategy at Optimal Blue. “Refinance activity continues to do the heavy lifting, but the fact that purchase volume held essentially flat month over month and finished the year higher than last December speaks to a market that is more durable than many expected.”

Lenders also made notable adjustments on the secondary side as pricing dynamics and execution strategies evolved. Best-efforts-to-mandatory spreads widened across products, bulk aggregator execution regained share, and mortgage servicing rights (MSR) values increased despite flat primary rates.

“December’s secondary data shows lenders actively recalibrating execution as spreads widened and pricing discipline remained tight,” Vough said. “The shift back toward bulk aggregation, combined with stable top-tier pricing and rising MSR values, reflects investor demand that is focused on end-of-year balance sheet management and long-term value as we head into 2026.”

Key findings from the Market Advantage report, derived from direct-source mortgage lock and secondary market data, include:

Volume trends and market composition

  • Refinance share expands: Refinances accounted for 37% of all locks in December, up 224 bps MoM and 1,354 bps YoY. Rate-and-term refinance volume increased 13% MoM and more than 170% YoY, while cash-out refinances rose 1% MoM and 35% YoY. Overall refinance pull-through improved 194 bps from November to 69.2%.
  • Purchase market remains resilient: Purchase locks slipped just 1% MoM despite typical holiday-driven seasonality and finished December 7% higher than a year earlier. Pull-through for purchase loans increased 199 bps MoM to 85.7%.
  • Non-QM sets another record: Non-qualified mortgage production maintained its upward trajectory, finishing December above 9% of locks, up 50 bps MoM.
  • Government and non-conforming gain share: Conforming loans accounted for 51% of locks in December, down 86 bps MoM and 18 bps YoY. Non-conforming share rose to 17%, up 17 bps MoM and 141 bps YoY. FHA, VA and USDA loans each gained share during the month.
  • PUD share remains sizable: Planned unit developments (PUDs) accounted for 29% of locks by property type, up 123 bps MoM but below year-ago levels, when PUD share was higher.

Rates and pricing

  • Rates largely unchanged: The OBMMI 30-year conforming fixed rate ended December flat at 6.14%. FHA rates declined 1 bp to 5.98%, VA rates fell 6 bps to 5.71% and jumbo rates dropped 3 bps to 6.41%.
  • MSR values move higher: MSR values for conforming 30-year loans increased 5 bps to 1.14%, representing a 4.57 multiple, rising despite largely stable primary rates.
  • Treasury yields rise as spreads widen: The 10-year Treasury yield increased 14 bps to 4.14% in December, compressing the mortgage–Treasury spread to 200 bps. Best-efforts-to-mandatory spreads widened across products, including a 2-bp increase for conforming 30-year loans and a 3-bp increase for government 30-year loans.
  • Top-tier pricing holds: The share of loans sold at the highest price tier remained flat at 79%, while second-tier share was unchanged at 11%, reflecting continued pricing discipline across the market.

Channel and execution

  • Execution mix shifts back toward aggregators: Lenders adjusted hedged execution strategies in December as bulk aggregators regained share at the expense of agency securitization and cash window channels.
  • Bulk aggregator share rebounds: Hedged loan sales to bulk aggregators increased 200 bps MoM to 29%, reversing a multi-month decline.
  • Securitization and cash window ease: Agency mortgage-backed securities (MBS) executions and cash window sales each declined 100 bps during the month.
  • Investor participation increases: The number of active investors rose to 12 in December after holding steady at 11 for four consecutive months, modestly expanding execution options for lenders.

Product mix and borrower profiles

  • Credit scores edge lower: The average borrower credit score declined to 732 in December from 733 in November, extending a gradual pullback from 746 in September.
  • Loan sizes rise as leverage varies by market: The average loan amount increased to $394,502 from $391,323 in November. Loan sizes ranged from $812,240 in Los Angeles to $315,735 in San Antonio. Loan-to-value ratios ranged from 68.85% in the San Francisco–Oakland Bay Area to 87.69% in San Antonio, with a national average of 80.10%.

To view the full December 2025 Market Advantage report, complete the free subscription form: https://engage.optimalblue.com/market-advantage. Subscribers receive a report PDF each month with the latest data. Members of the press are eligible for special, advance access each month and should contact Olivia DeLancey to be added to the media list.

About the Market Advantage Report

Optimal Blue issues the Market Advantage mortgage report each month to provide insight into U.S. mortgage trends and drivers of lending profitability. Data is sourced from the Optimal Blue PPE, which is used to price and lock more than one-third of all mortgages nationwide, and Optimal Blue’s hedging and loan trading system, which supports approximately 40% of loans hedged and sold into the secondary market. As the leader in mortgage capital markets technology, Optimal Blue has a direct view of both origination and secondary market activity and the interconnectedness of the two. Unlike self-reported survey data, Optimal Blue’s direct-source data accurately reflect the in-process loans in lenders’ pipelines and secondary market executions. Visit Optimal Blue’s website to subscribe to receive the free report each month.

Nothing herein shall be construed as, nor is Optimal Blue providing, any legal, trading, hedging or financial advice.

About Optimal Blue

Optimal Blue powers profitability across the mortgage capital markets ecosystem. As the industry’s only end-to-end capital markets platform, our technology, data and integrations bridge the primary and secondary markets to help lenders of all sizes maximize performance – from pricing accuracy to margin protection and every step in between. Backed by over 20 years of proven expertise, our modern, cloud-native technology delivers the real-time automation, actionable data and seamless connectivity lenders need to navigate market volatility and scale for growth. To learn more about how Optimal Blue delivers measurable ROI, visit OptimalBlue.com.

MULTIMEDIA:

Image link for media: https://www.Send2Press.com/300dpi/26-0113-s2p-opbluedec25-300dpi.webp

Image caption: Optimal Blue’s December 2025 Market Advantage mortgage data report

NEWS SOURCE: Optimal Blue


This press release was issued on behalf of the news source (Optimal Blue), who is solely responsible for its accuracy, by Send2Press Newswire. Image, if any, was provided by the news source and not this website or the wire service. Information is believed accurate, as provided by the news source, but is not guaranteed.

To view the original story, visit: https://www.send2press.com/wire/optimal-blue-report-december-lock-volume-closes-2025-on-a-firm-footing/

Copr. © 2026 Send2Press® Newswire, Calif., USA. -- REF: S2P STORY ID: S2P132225 NOREL-3B